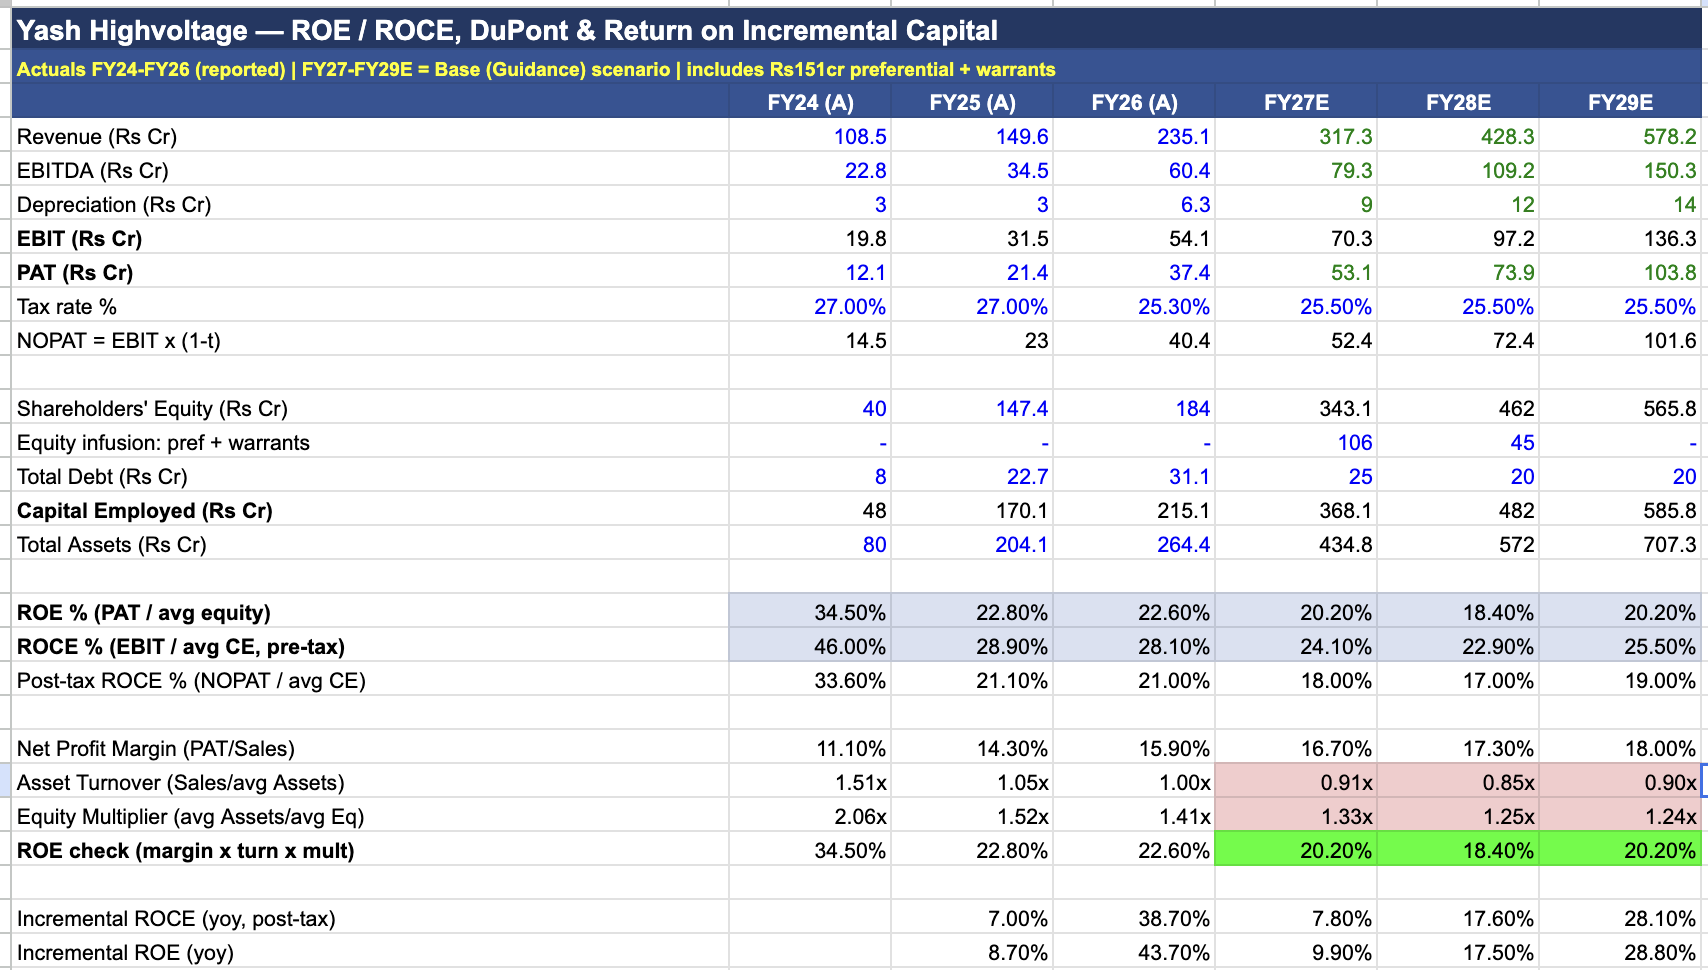
Impact on ROE due to Pref Issue + Warrants Conversion in next 3 years.
9 Likes
Good explanations of business and it’s evolution (starts at : 7:50)
2 Likes
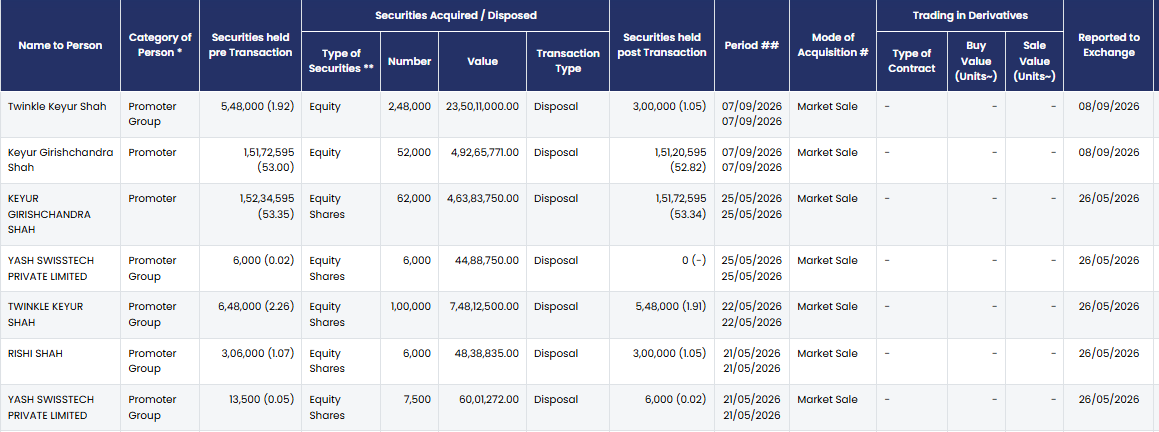
One of my core criteria for holding a stock is the promoter’s skin in the game. Any regular promoter selling shares, especially in the open market is something I personally dislike; hence, I exited the stock with decent gains. Of course, it may just be their personal decision, but do you guys have any insights into why they are selling? Latest selling by promoters is a couple of days back.
5 Likes
- although negative, but since holding is above 50%, personally i feel ok
- my probable guess for selling is, Keyur Shah has mentioned of inorganically acquiring companies similar to Sukrut in future. So they might reinvest this cash
- valuation are quite rich now, so it’s best time to book profit, given the next half yearly result might be on the weaker side as new capacity will not start fully.
1 Like
Well, for an SME company, I expect higher % of promoter holding in the company.
The money is going to their personal accounts, so how that will be used for inorganic acquisitions??
3 Likes
It’s my bias talking. You are right on this fact. Hopefully it’s for personal reason, exiting at a good valuation.
Let’s see if there are further dilution in future.
1 Like
Thanks for sharing this information. A general question - from where did you source this data? Could you share the name of the particular website?
@rohitshastri LIVE Stock/Share Market | Indian Stock/Share Market LIVE | BSE SENSEX | BSE (formerly Bombay Stock Exchange)
My views could be biased but in my opinion, it is not a point of concern of we see the overall holding. This is usual behaviour when stock runs up in a short time.
I queried gemini on the same and agree with below reasons -
Open market selling by core promoters means they are pocketing cash directly, rather than the company issuing new shares to raise expansion funds.
The primary reasons for this distinct open-market sale involve several key factors:
1. Partial Profit Booking After Multi-Bagger Runs
Exchange disclosures show core promoters Keyur Girishchandra Shah and Twinkle Keyur Shah sold a combined 3,00,000 shares. The stock has delivered a staggering 160%+ gain from its 52-week low and trades at a steep price-to-earnings (P/E) multiple of roughly 76x. In micro-cap and small-cap stocks that experience massive runs, promoters occasionally liquidate a tiny sliver of their holding (roughly 1% of the total equity in this case) to unlock personal liquidity or book partial profits.
2. Making Room for Institutional Entry (Liquidity Rebalancing)
For micro-cap companies like Yash Highvoltage, bringing in large funds like Malabar India or WhiteOak Capital requires sufficient trading liquidity. If a promoter group hoards the entire float, large funds cannot easily buy their targeted stakes without sending the stock into upper circuits. Promoters sometimes choose to pare down a tiny fraction of their holdings in the open market to absorb the heavy buying demand generated by inbound institutional funds.
3. Maintaining Absolute Skin in the Game
Despite the open-market sale, there is no threat to the company’s leadership alignment. Core promoter Keyur Girishchandra Shah alone continues to hold a massive 151.73 lakh shares, keeping over 53% control of the company. Total promoter skin in the game sits securely at 57.21%. This indicates a minor liquidity adjustment rather than an exit or a lack of confidence in the business.
3 Likes
Where are you getting these 57.21% numbers? As per exchange filing (as of 14th Aug 2026) LIVE Stock/Share Market | Indian Stock/Share Market LIVE | BSE SENSEX | BSE (formerly Bombay Stock Exchange), the promoter & promoter group holding is 52.9%. After this, they have further sold about 3 lakh shares on 8th Sep 2026.
1 Like
Please ignore the %. It’s not accurate. AI sourced it from some website. I rely on Screener data which is not real-time but is fairly recent. It shows around 54%. I won’t be concerned unless it drop to below 40% in a short time.
Screener also shows that from June 2026 to Aug 2026, FII holding from .62 to 2.17%. so it is imp to see where the sold shares are going. I would be worried if promotors are selling large % of their total holding and all that is going to retail investor. That maybe a point of concern, but it DII or FII is buying that, it is actually a green signal.
My hunch is - promotors knows the upcoming results. H1 is generally light and might trigger profit booking as valuations are rich. Promotors may buy back then, maybe just booking short term profit.
Or this is being sold for the reason 2 mentioned above of increasing the liquidity, as analyst coverage as increased for yash in recent past.
As of now, I do not see any reason for concern atleast. Will wait for results and concall. This question will surely be asked.
1 Like
We don’t know who they sold this to. It could be to a predetermined institutional entity via bulk/block, which may be a plus.
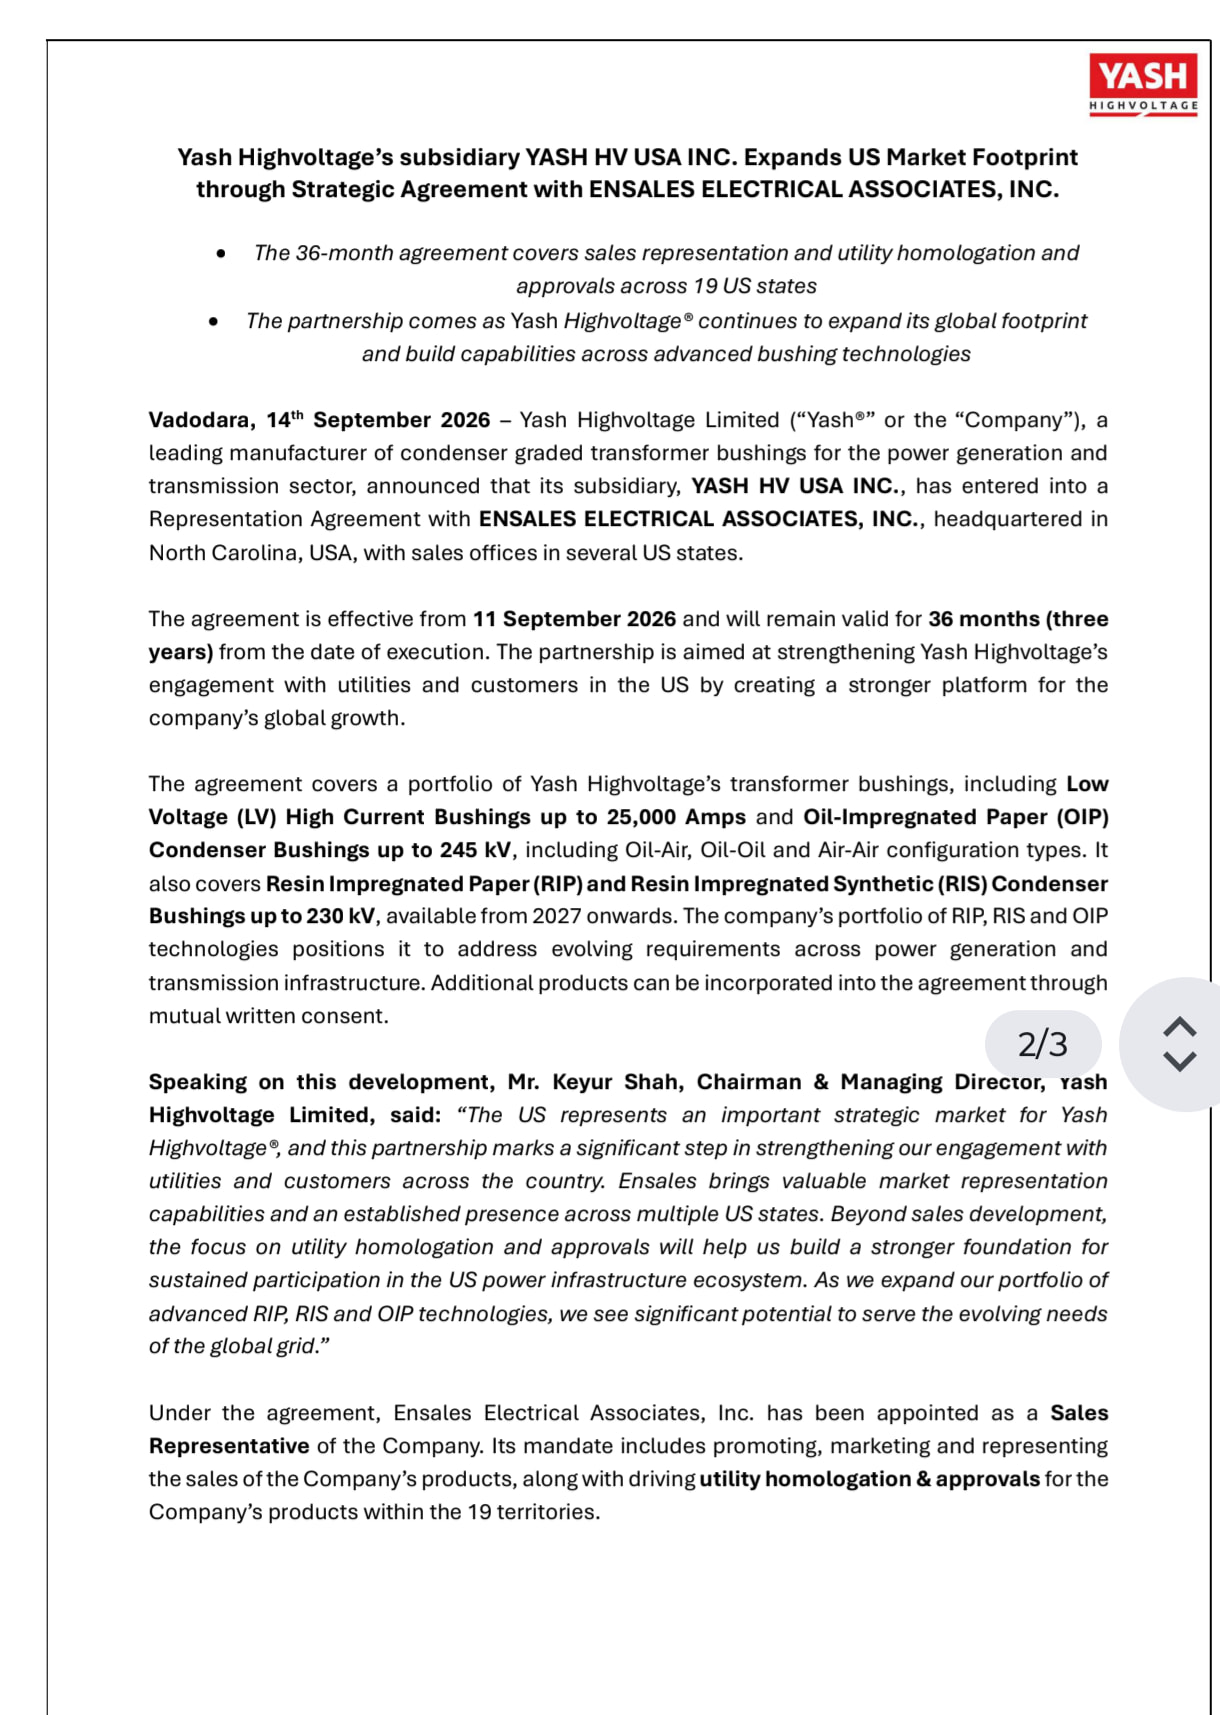

Power is good sector having long-term growth story. However, market has given significantly high multiples considering strong future growth. However, if sentiments changes, overcapacity/over supply scenario and slowdown in power sector could impact negatively and de-rating of multiples could result correction or time correction.
5 Likes
no of transformer players in world>>> far greater than Bushing players
concern is valuation for sure reg Yash high voltage
all power equipment like quality power/hitachi /cg power all trade at very high valuations
3 Likes
out of park nos from yash high voltage as mentioned no of unique specialised bushing players with absolute dominance are far less.. without RIP core and US sales this has been achieved see X full of Yash tweets
6 Likes