
True, but I am not worried. The Ramp thesis was also what led me to “ramp up” shares in the company (pun intended). When I feel down about the price, though, I remember Zomato in 2022  . Still very bullish and still a regular buyer
2 Likes
The valuations are definitely starting to look attractive at this point.
Have few questions, would be great if someone could answer.
- The software engineer salaries are way below market. How would they be able to hire and retain top tech talent with these salaries.
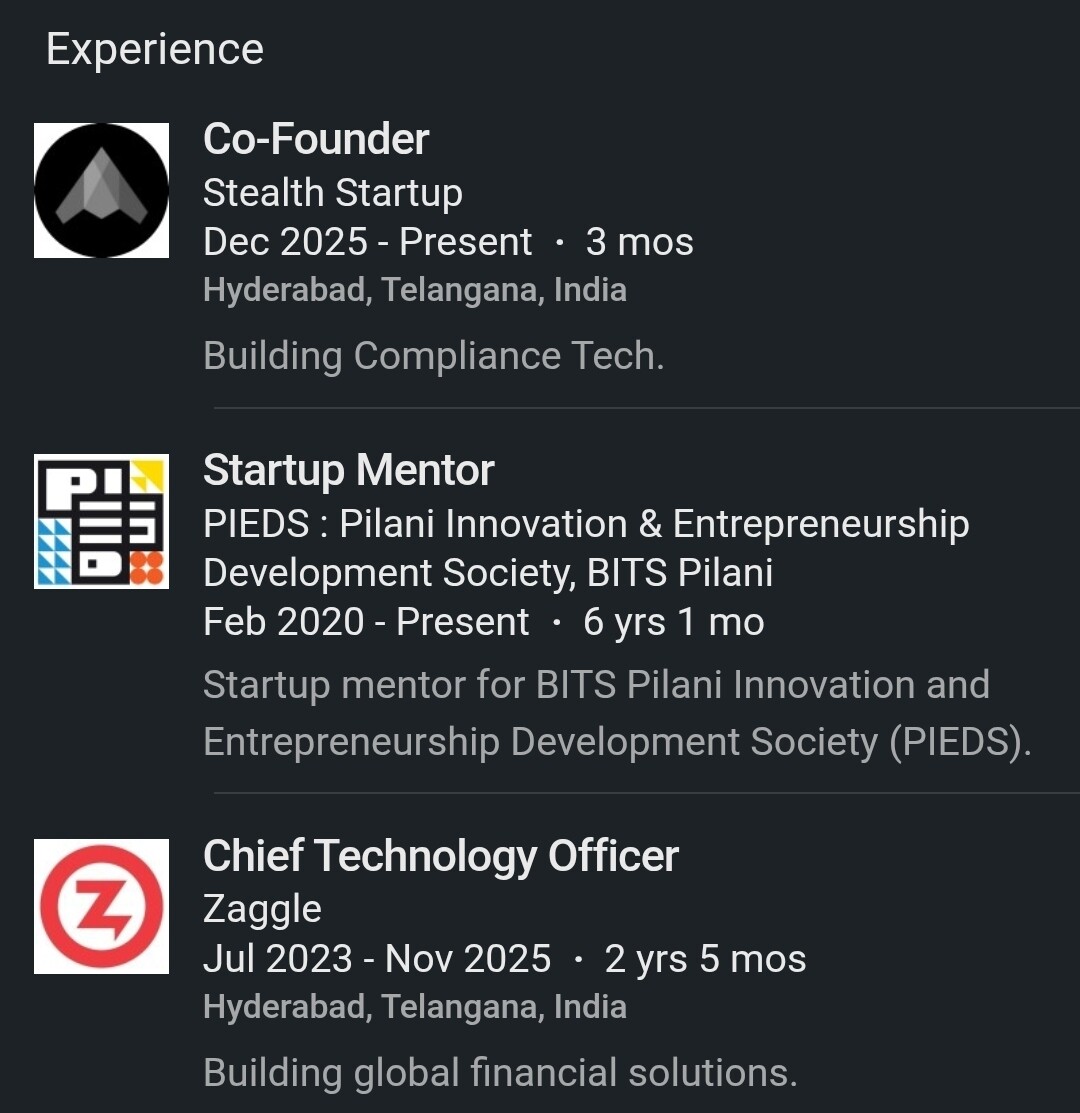
- The LinkedIn profile of CTO of zaggle says, his tenure ended November last year. Do we have a new CTO. Not able to find people with head of engineering/ Vp engineering/ CTO etc. How would they able to build and maintain a tech platform without a good experienced engineering leadership?
- If the core SAAS software is truly useful and is used extensively. Why is it not growing as fast as other segments ?
- Is there any metrics that they have given which points to good adoption of core software such as eg: number of invoices posted via ghost flow, NPS of zoyer platform etc.
4 Likes
- Is it really below the norms? Does not seem too low honestly when I just checked now. What you would expect in an Indian fintech company. Do clarify though
- Software is the sticking point, not the monetization tool. The main source of revenue will be program revenue where they basically monetize the flow of cash by taking a share of the interchange fees through Zaggle cards. But why do companies and banks allow zaggle to take a cut? Zaggle provides companies with their SaaS suite at very low costs … 100 rs per user per year which becomes a huge incentive to tie up with zaggle for their various expense needs. Banks get access to various salaried employees too this way. Zaggle has enough supply on both sides as they have done tie up with many banks so I dont envisage a dreamfolks like situation happening. (If one bank wants to modify the interchange fee or eat zaggles share, zaggle will give their business to another bank and a smaller bank will be more than happy to be cooperative). Ramp also does the same and management has tried to highlight this too. The incentive business is also a decent product but it’s low margins and very competitive which is why margins have been falling over the years. If anything there is an opportunity for SaaS revenues to scale up… if their software is truly value, no company would think twice about spending 10 dollars per employee per year from 1 dollar per employee per year. Companies pay such amounts on a monthly basis for so many SaaS tools. I think Zaggle wants mass adoption (Jio strategy) before monetizing other areas. The interchange fees themselves are so lucrative!
5 Likes
This CTO thing is a big red flag if true. Did some quick search and not able to find any disclosure regarding the same. Srikanth has definitely exited as per his linkedin profile:
Again surprised such questions are not asked in concalls. Analysts are busy saying ‘thank you for the opportunity sir’.
6 Likes
IMO problem is not with CTO resignation.
It’s the Quality of Engineering heads even in the past. This along with software engineer salaries gives me an impression that they see software as a cost center rather than a core offering.
For now it’s Ok because for payments they might be using underlying bank/card provider infra.
But as the number of interactions with core software increases eg: uploading an invoice after transaction wouldn’t it require a top tech team to manage scale?
If the experience is not good enough wouldn’t people go for competitors or even peripheral softwares ?
1 Like
Good read.
Also @rookie_investor_1 , please elaborate a bit more on the employee salaries that seem less as I found them normal. I am seeing 8 lakhs and beyond with 8 lakhs being for starting roles. That does not seem too bad.
Also why you feel the engineering team has been lacklustre in the past. Thanks
1 Like
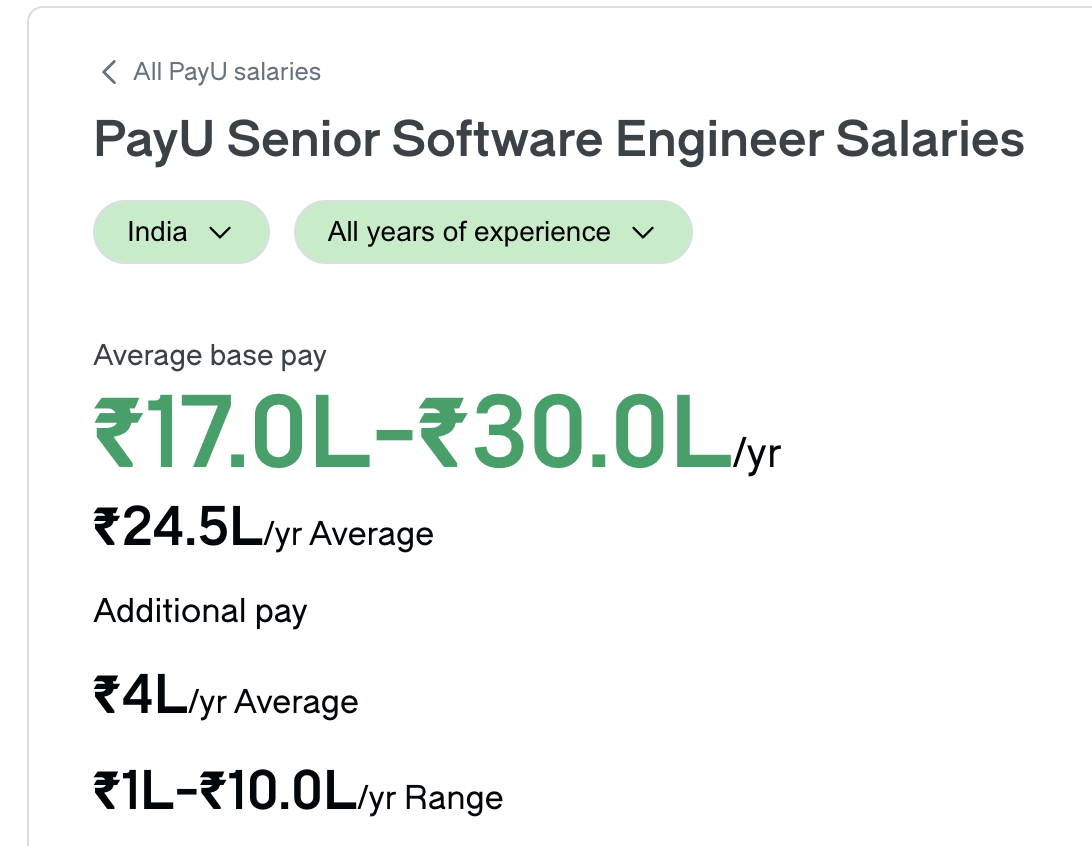
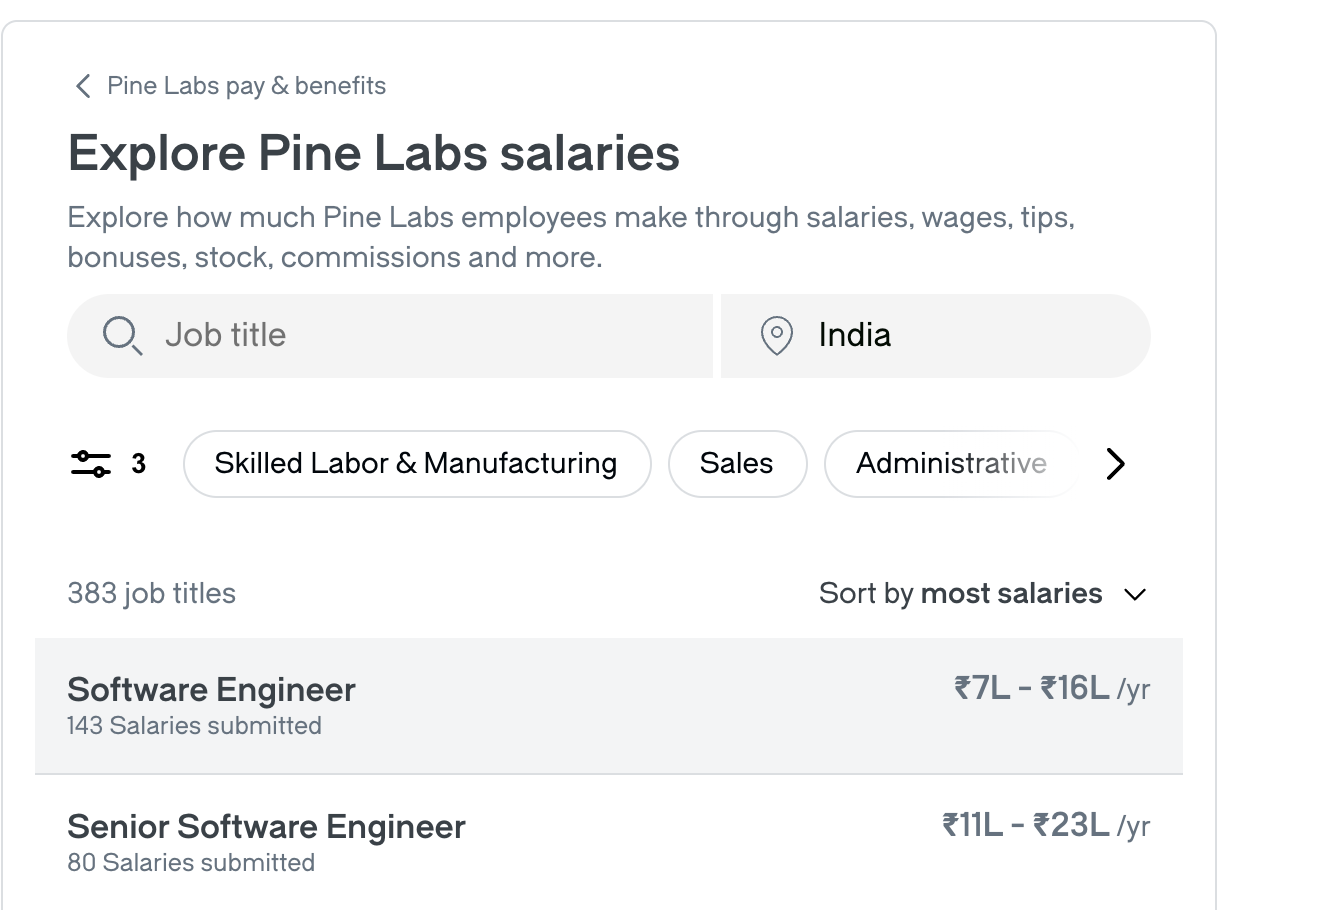
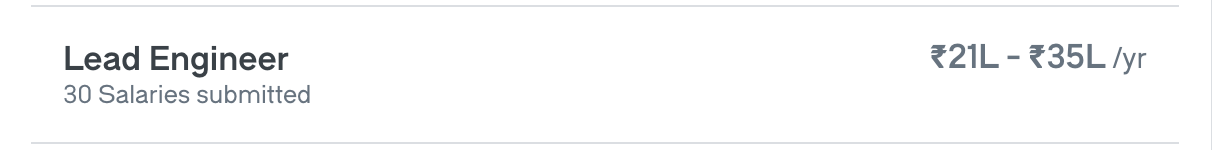
Engineer salaries don’t seem low at all. Starting salaries are upto upto 10 lakh and senior engineers upto 30 lakh according to glassdoor.
This is not FAANG or VC funded startup level, but definitely on par with the regular companies.
2 Likes
Since there was no direct comparison data just used Gemini to create this. But ball park looks accurate to me.
Pine Labs
Fresher / SDE 1: ₹12 – ₹18 LPA
Mid-Level (2–5 yrs): ₹21 – ₹35 LPA
Senior (5+ yrs): ₹35 – ₹55+ LPA
Lead / Architect: ₹60 – ₹90+ LPA
PayU
Fresher / SDE 1: ₹10 – ₹16 LPA
Mid-Level (2–5 yrs): ₹18 – ₹32 LPA
Senior (5+ yrs): ₹32 – ₹50 LPA
Lead / Architect: ₹55 – ₹85+ LPA
Zaggle
Fresher / SDE 1: ₹7 – ₹11 LPA
Mid-Level (2–5 yrs): ₹13 – ₹20 LPA
Senior (5+ yrs): ₹22 – ₹35 LPA
Lead / Architect:
₹40 – ₹60 LPA
From what I know senior engineers in most product companies earn upwards of 30 lakhs.
I am not at all talking about FAANG
2 Likes
These are the figures I found on glassdoor. If you include “additional pay“ and all one can make a case that these do pay a bit more, but the margin is just tiny, which doesn’t bother me at all.
3 Likes
This looks less like giving insights on business and more about pushing stock price.
Edit: removed the accounting part
That did not seem the case, he spoke about delivering the guidance (which zaggle did) and how AI is a beneficiary. No question about why share price is down.
Secondly why do you feel zaggle will cook their books? You need to substantiate your statement else you are just creating unnecessary fear in a free fall environment
6 Likes
Do you have any proof for this or are you just making this up? If it’s the latter, refrain from doing so.
3 Likes
A very good piece I read on twitter/X written by Varun Iyer (https://x.com/VPSIyer?s=20)
Zaggle Prepaid Ocean Services
Mcap 3k | TTM PE 24x | 5 Y PAT 60% CAGR
Over the past year the stock has corrected significantly owing to fears of AI Disruption. In fact the market believes that AI tools can allow the customers of Zaggle to do all the work by themselves and not require any external organization like Zaggle.
Lets for once ask, will it be so that with AI, there would be no need for ownership of processes. AI would replace all the requirements for systems integration and process coordination and regulatory compliance and hence the end user would do it all by himself.
If the answer is yes then Zaggle and other companies are worth nothing otherwise they are at a cusp of a major earnings upcyle.
Think of this way, instead of AI replacing Zaggle if it becomes a tool which Zaggle can itself use to create a faster to deploy product suite. I could speed up the time to market and increase the range of services it offers its customers in the same platform.
Zaggle can offer more products to its customers to become a 360 degree solution provider.
Lets see what the management said about it
I always wonder, if AI has really reduced cost of creation they why sould more US and European companies establis GCCs in india?
Another point worth noting is that Zaggle is adding products in Finance. Mainly lending and payments. This offerings comprise of services which are subject to RBI audits and SEBI complinace.
If an AI tool is used by the client automates it then they are answerable to the audits undertaken by the regulators.
When an enterprise vendor like Zaggle proveds these services, they take ownership of the process adn are hence answerable. I don’t think any client organization wants to get into the process of owning something they don’t consider their core function.
There are also no signs of any customers reducing business to Zaggle in fact if any the existing clients have bought more of theri products and services
If the new product is offering GST benefits, that tells you that the system ownership and ERP integration amtters more than saving few dollars therough an AI tool.
The above post is a contra view of the current situation where anything and everthing is getting butchered in the name of AI. Lets take a step back and think what is the real impact on a business and what is overstated.
In Conclusion
FY 27 Zaggle amy witness more business from high amrgin products like Zagg money and another servies involving procurement and leasing of mobile to enterprise customers
Hence, this should result in an improved margin of 8.5% at PAT level in FY 27 (7.2% this year)
FY 26 Topline Rs 1800 crs expected
FY 27 est Rs 2700 Crs | PAT est Rs 230 crs
Its trades 13X FY 27 PE.
Disc: Not biased but Heavily Invested.
6 Likes
In latest disclosure, RAN ventures (promoter entity) bought 30K shares on friday/monday. could be around worth Rs 0.7Cr . They also bought 65K shares in Feb 2025 right around when share price was hitting lower circuits (prob worth around Rs 2Cr that time)
I have a feeling they will buy more in coming days to send more of same message
4 Likes
He said they will be the biggest beneficiary of AI which seems far fetched. Tech costs are not their significant expense that would be cashback and reward points. What AI will do is currently a grey area to me and I have already expressed my views on the same.
The anchor mentioned share price is up due to the commentary which seems for TRP purposes. Anchor should maybe zoom out a bit and see >60% fall from ATH.
@ishaanS
I did get the information regarding 30k purchases (https://bsmedia.business-standard.com/_media/bs/data/announcements/bse/19022025/A4786156_120C_4792_9063_1A3D9133F4B5_101332.pdf).
But i didnt get any infor. regarding the 65k open market purchase which you mentioned. Can you share the link to that data ?
1 Like
I guess, Beneficiary of AI is not in-relation to tech cost.
Its in relation to product development, product deployment, feedback loops, & faster product updates. ( they drastically viewing to get it under 10 days, which they managed to lower from 75+ days to 30 days with the use of AI) & (Entry level tasks from 4 days to 10 minutes).
Also not to mention less employee cost.
1 Like
Its from Feb 2025. I looked and found more actually. All these are from Feb 2025:
1.15L shares: https://www.bseindia.com/xml-data/corpfiling/AttachHis/8964435C_9972_4403_A40C_F88E404A4666_172454.pdf
30K shares: https://www.bseindia.com/xml-data/corpfiling/AttachHis/1671A1F0_1863_4010_9F60_5E8F27FA0421_110304.pdf
30K shares: https://www.bseindia.com/xml-data/corpfiling/AttachHis/A4786156_120C_4792_9063_1A3D9133F4B5_101332.pdf
65K shares: https://www.bseindia.com/xml-data/corpfiling/AttachHis/64E71802_8DA5_4F6C_BDD3_9A1E257D9CB4_123717.pdf
25K shares: https://www.bseindia.com/xml-data/corpfiling/AttachHis/4DCB4B9A_BA14_45BF_81B2_2B78239AAA28_165627.pdf
5 Likes
Hi Vivek, Can you help me explain why is the company not able to generate cash?
2 Likes
Hi Aayush.
It has been discussed many times in this thread.
So I will try explaining in-short.
Its not that company isn’t generating cash.
It’s a matter for what company wants & it’s their conscious decision : Growth v/s showing Cash at the expense of growth.
Now if you ask, that if company is generating cash, why doesn’t it gets shown in balance sheet.
For that you need to know what company primarily does.
Its the largest corporate Prepaid Card issuer in India.
As the word prepaid suggests, they need to reload the cards well in advance.
And such Advances, deposits, prepaid balances increases with scale. These consumes operating cash.
Since Program fees + interchange recognized are on accruals, but cash only when its received it feels like they aren’t generating cash. But its wrong. It is just Cash timing mismatch between client collections and payouts.
Had they been not able to generate cash for the business they are into, you would have start seeing high write-offs, bad loans or NPA’s.
Its just that right now they are in high growth phase & Growth in volume requires higher working capital funding. As well as since you need to maintain a healthy relation to corporates, sometimes they even had to load higher amounts to their clients (higher than what was sanctioned) before festive seasons, or year end disbursements at the request of their corporate clients.
Though they had been guiding OCF breakeven by ‘26 & OCF positive by ‘27.
If you are just planning investing on that metric, you need to follow the above timelines.
I hope it clears the doubt.
10 Likes