Thanks Bhai. What are the other stocks that you are supper bullish on if you can share?
Thanks once again for your guidance and valuable inputs.
Thanks Bhai. What are the other stocks that you are supper bullish on if you can share?
Thanks once again for your guidance and valuable inputs.
My pleasure @tbhavesh . I don’t want to deviate from this thread too much, but in short, I am not looking at anything new right now. I am more interested in protecting the gains I have made so far.
Back to ASM, I am curious to see what the actual asset turn number will look like for the ₹760 cr in new capital investments that the company is going to make over the next two things.
And patiently waiting for updates from the ASM-HHV joint venture.
Ok - Thanks. Please keep the group posted with any new updates you get on ASM
ASM Technologies Ltd has taken a 20% stake in Myelin Foundry Pvt Ltd to embed **edge AI directly into ASM’s machines and manufacturing systems.
ASM is adding an AI “brain” to its equipment:
Predictive maintenance
Real-time machine health
Vision + sensor analytics
Smarter, more autonomous factories
Seems like a futuristic aquisition agentic AI sace.
Seems some big investors are exiting - price has already corrected by more than 50% from top. Technically price is moving in an downward sloping channel and if it does not reverse at current prices then it can go down to 2175 and deep down till 1500. Seems some fundamental issues that the market knows in advance.
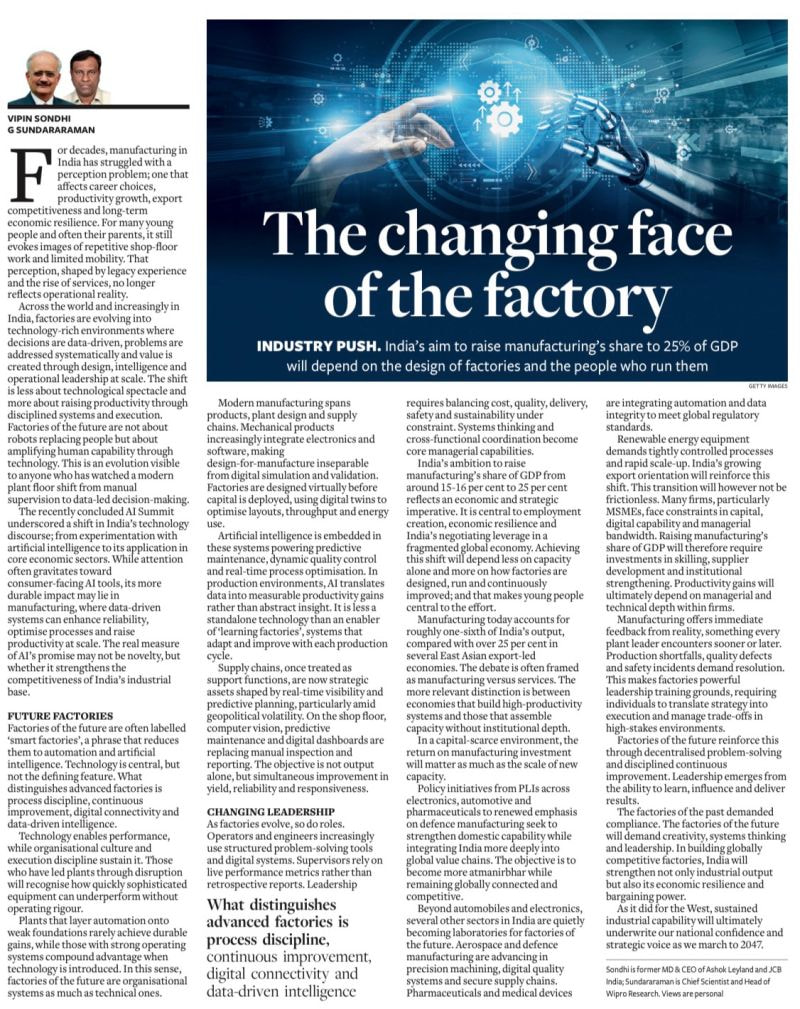
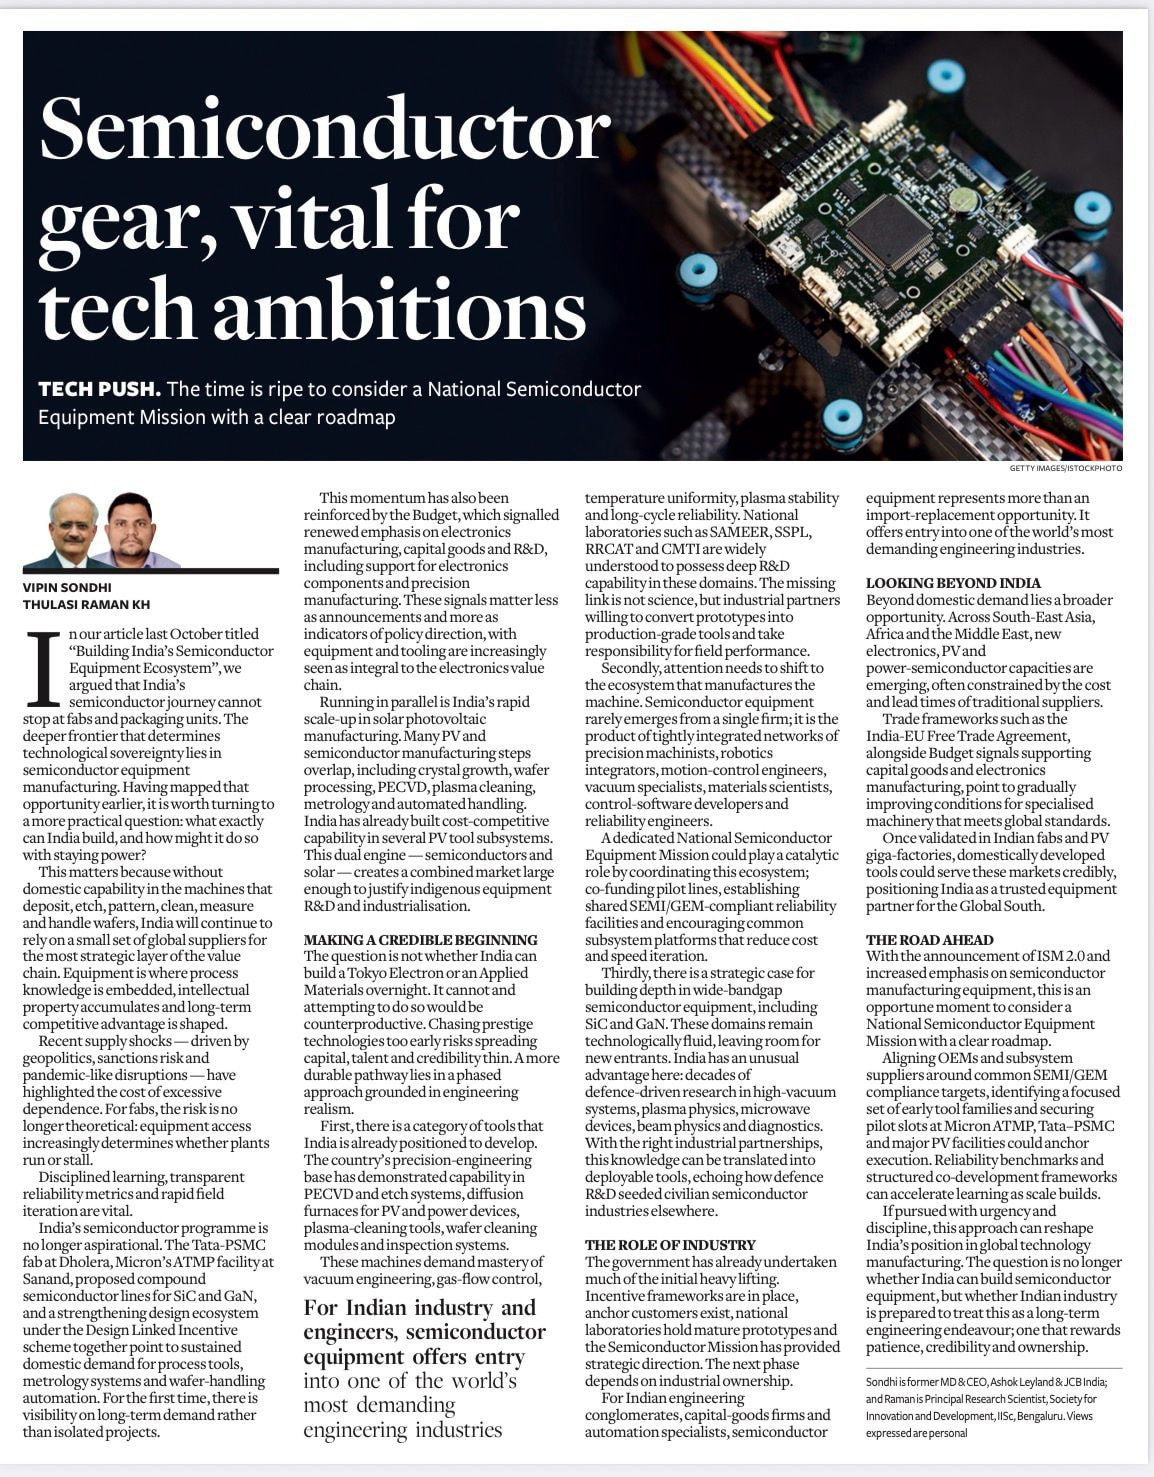
A casual look https://www.linkedin.com/in/vipinsondhi/ profile Ex MD of JCB & Ashok Leyland and hairperson, National Board for Quality Promotion and lets see his last 2 posts.
It seems ironical that most of the areas which are being talked about in these 2 posts are the areas which ASM Technologies are already into .
ASM is just not another ERD company but the biggest proponent of the next wave of Industry 4.0 India manufacturing story.
Another way to look at ASM is it a Deep Tech Info edge of sorts but in manufacturing domain.
I also keep comparing ASM to another portfolio company of mine Laurus Labs albeit in a different field
Look at the quality of the recent Acquisition of 20% stake in Myelin Foundry https://www.linkedin.com/in/gkatragadda/details/experience/
Gopichand Katragadda CTO of Tata Group as well as the MD of GE JFWTC .
It must be commended that Rabindra Srikantan is building something special . This company may not be for the short term investors but I believe whatever ASM is building is something special and the business 5 years down the line will be completely different than what it is today.
Disclosure : Heavily biased and my top PF holding for a long term perspective.
Would love to hear from others who have been holding this company way longer than me what are their views.
I have been tracking this company for some time now - but my holding decisions are driven based on technicals. I agree with all that you have mentioned - but there is one more thing - price factors everything and at this point of time, ASM is in full bearish mode - will not be suprised if the price corrects back to 1800 odd levels.
Founder and CEO at Myelin Foundry; Independent Director for Bosch Ltd, Asian Paints, and ICICI Securities; Past Group CTO, Tata Sons; Past MD, GE JFWTC; Chartered Engineer (UK)
February 24, 2026
AI in manufacturing is frequently sold as a “plant-level” transformation—a world of cloud analytics, centralized monitoring, and sleek executive dashboards. Yet, this framing misses a fundamental shift. The real opportunity isn’t layering AI on top of factories; it is embedding it directly within the equipment.
Most manufacturing plants are built for stability, not experimentation. Technology teams focus on ERP systems and automation integration, while AI initiatives often float in a “no-man’s land” between IT and Operations. When a predictive model fails or produces ambiguous data, accountability is diffused.
Equipment manufacturers operate differently. They understand the machine’s physics, the nuances of its failure modes, and the limits of its firmware. For them, AI isn’t an “add-on”—it is a core engineering requirement.
When intelligence is embedded at the equipment layer, AI becomes part of the machine’s nervous system. The advantages are immediate:
Data Integrity: Raw sensor data is accessed directly, and signal quality is calibrated at the source.
Precision: Models are tuned to specific mechanical tolerances and usage patterns, rather than generic averages.
Security: Update cycles and security frameworks are controlled end-to-end, reducing the “attack surface” created by external software layers.
There is a profound economic advantage to this shift. Currently, plants purchase uptime, treating predictive maintenance as a discretionary “retrofit” evaluated on local ROI.
However, when AI is embedded, the OEM (Original Equipment Manufacturer) can sell assured performance. Predictive maintenance becomes part of the capital purchase, backed by warranties and service agreements. This transforms the business model from selling hardware to selling guaranteed output—a shift that opens the door to performance-based contracts and recurring analytics revenue.
The technical architecture for this transition must be edge-native. Industrial environments cannot rely on cloud latency or bandwidth. They demand deterministic response times and cyber-resilience.
The collaboration between ASM Technologies and Myelin Foundry is anchored in this philosophy. By combining ASM’s deep engineering services and global manufacturing expertise with Myelin Foundry’s Edge AI operating architecture, the goal is clear: to move beyond analytics dashboards and enable AI-native manufacturing equipment.
This approach positions India uniquely in the global value chain. Rather than exporting software overlays, we can export intelligent machines.
Self-Diagnosing: Equipment that understands its own health.
Continuous Learning: Machines that improve across deployments via federated models.
Sustainability: Intrinsic optimisation of energy and resources.
The future of manufacturing will not be defined by centralised dashboards alone; it will be defined by machines that understand themselves. For AI to deliver structural value rather than incremental optimisation, it must migrate to the machine.
ASM Technologies Ltd’s acquisition of Asmaitha Wireless Technologies is mainly about adding the electronics and control layer to its capabilities. While ASM already had strength in mechanical systems (Forms & Gears), process technologies (HHV), and AI (Myelin), it lacked embedded systems, control electronics, and connectivity. Asmaitha fills this gap by enabling ASM to build machines with in-built control systems, IoT connectivity, and real-time data handling, which are essential for modern industrial and semiconductor equipment.
Strategically, this moves ASM closer to becoming a full-stack intelligent equipment company, rather than just a subsystem manufacturer. With hardware + process + AI + electronics now coming together, ASM can design and deliver complete, connected, and smarter machines, improving margins, IP ownership, and global competitiveness. While this won’t immediately boost revenues, it is a key step toward ASM’s long-term goal of evolving into an OEM for advanced equipment in solar, semiconductor, and eventually photonics/quantum infrastructure which is used by the cutting edge technology used in present day top notch equipment companies.
Asmaitha_Wireless_Technologies.pdf (346.8 KB)
Appreciate your thought process and thank you for connecting the missed links.
Basically Asmtech is a play on the promoter who have done out of the box actions to bring unique capabilities and capacities under this company. He has a vision and skills to bring various stake holders together and make efforts to get desired result where everyone is beneficiary. In the past also promoter done a series of merger and acquisitions, later years most of these have turned up as great success. So i trust promoter and leave it to him and not making any judgmental remarks on these aquisitions.
Hope for the best.
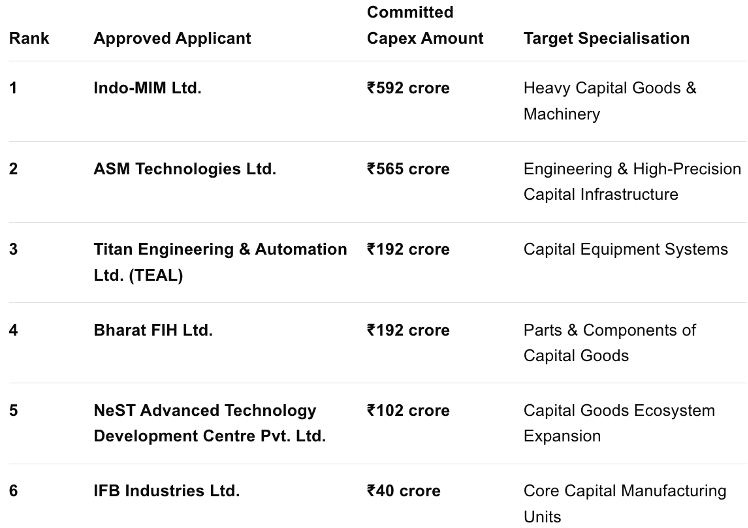
Government for the 1st time approved capital equipment makers to participate the Electronics Component Manufacturing Scheme (ECMS) . And ASM was in the 1st set of companies to receive grants under the Capital Goods category with a massive Capex of 565 crs
https://www.pib.gov.in/PressReleaseIframePage.aspx?PRID=2247040®=3&lang=2
Now they have given the notification for raising of funds .. Interesting developments and times ahead..
Disclosure : Invested and biased . Part of my top 2 positions
Indeed, interesting times indeed.
What I found really interesting from the Government of India was the following: The application window for SPECS officially closed on March 31, 2024. Looks like SPECS has been replaced with the Electronics Components Manufacturing Scheme (ECMS).
Now there’s a lot of fine print, but unlike SPECS, I believe that the ECMS program has clear employment thresholds to obtain the full capex incentive of 25%. In addition, ECMS also has a production linked incentive, which I am assuming is in the 1-10% range.
Given that ASM is near the top of the list of companies when it comes to the capex commitments under this scheme, I am excited for what comes ahead. And let’s see what comes out of the fundraising discussion tomorrow.
Disclosure of holding: I kept buying shares in ASM Technologies from 2021 to 2023, with an overall cost basis of ₹227. I have a fairly concentrated portfolio and do not own more than 10 companies at any given time.
a simple Claude probe on Corporate governance produces the below :
Two of the MD’s sons draw remuneration. Akhil Rabindra is designated “Executive Director” in senior management (he’s also a professional racing driver) and was paid ₹2.97 crore in FY26 — more than his father the MD (₹2.83 cr), and up ~3.5x from ₹0.84 cr the prior year. Nikhil Rabindra was paid ₹1.17 cr. The CFO’s relative (Nirmala Rathod) is also on the payroll. Total promoter-family compensation is roughly ₹7 crore against ₹64 crore of PAT (~11%), with the fastest-growing line being the son’s pay.
RV Forms & Gears LLP — historically the MD’s own LLP (he’s a designated partner), now consolidated as a subsidiary — is a large intra-group exposure: ~₹30.5 crore loan outstanding, a ₹20 crore loan-to-equity conversion this year, interest receivable that collapsed from ₹6.4 cr to ₹0.9 cr, and a ₹5.17 crore corporate guarantee the parent gives for its credit facilities. The CARO report (below) confirms the interest wasn’t being serviced. When a parent capitalises loans to a promoter-linked entity because it isn’t repaying, that’s the pattern to watch.
Auditor’s substantive flags (CARO + Emphasis of Matter). The consolidated report formally marks the holding company as qualified/adverse on two CARO clauses: inventory verification (the auditor says the company “needs to increase the frequency” of physical verification given its size — relevant, since inventory built sharply as the business shifted into manufacturing) and loans (interest of ₹0.22 cr from a foreign subsidiary overdue more than two years, and ₹2.13 cr from an Indian subsidiary overdue). PPE was also not physically verified during the year. Separately, the Emphasis of Matter is the one I’d underline: the fair values of two strategic investments — EclecticIQ (formerly Polylogyx) and Lavelle Networks — are carried above cost, but management could not obtain the data to perform a formal Ind AS 109 valuation and the auditor relied on a management representation that value has “substantially increased.” The amounts are small (~₹6 crore combined), but it’s a “trust us” valuation, exactly the kind of thing your via-negativa filter should note.
at least Orange Flags ? also the third generation - already an Executive Director in the company is a professional car racer, nothing bad with that but why in business as Executive Director?
ASM Technologies – 34th AGM Summary
The 34th AGM provided much better execution clarity compared to previous years. Management focused on progress made over the last year, current execution status, and clear milestones for the next 2–3 years.
Business Performance:
Strong FY26 growth in revenue, EBITDA, and PAT.
Growth driven by both Engineering Services and Design-Led Manufacturing (DLM).
Manufacturing capacity utilization is above 90%, indicating healthy demand.
Manufacturing Expansion:
Three new facilities commissioned during the year (including Vietnam).
Total manufacturing facilities increased to seven.
Karnataka DLM expansion received land allocation and government approval.
Overall investment roadmap of approximately ₹1,200 crore planned over the next 2–3 years for manufacturing expansion, buildings, strategic investments, acquisitions, and technology.
ASM-HHV Engineering Progress:
First solar equipment prototype has been completed and is under testing.
First commercial invoicing expected in Q2 FY27.
Repeat orders and regular revenue expected from Q3–Q4 FY27.
Crystal puller demonstration facility targeted by Q4 FY27.
Commercial revenue from crystal pullers expected from FY28.
Dedicated manufacturing facility planned for crystal growth equipment.
Semiconductor & Solar Roadmap:
Focus continues on indigenous semiconductor equipment development.
Solar manufacturing equipment is being used as the initial commercialization path before expanding into advanced semiconductor equipment.
Development work is progressing on low-cost polysilicon processes, silicon technologies, and crystal growth equipment.
Management believes these initiatives align well with India’s semiconductor ecosystem and future government programs.
AI & Strategic Investments:
AI is now integrated across engineering, manufacturing, testing, software development, and project delivery.
Strategic investments completed in:
Myelin Foundry (Industrial AI)
Asmaitha Wireless (Embedded Systems, Firmware & Wireless Technologies)
These acquisitions are intended to strengthen both engineering capabilities and Design-Led Manufacturing.
Global Expansion:
Vietnam manufacturing facility is operational.
Expansion intended to support global customers locally and strengthen the international manufacturing footprint.
Customer Visibility:
Management indicated healthy business visibility ranging from approximately 18 to 36 months.
Customer names and specific order values were not disclosed due to confidentiality agreements.
What Was Achieved:
Manufacturing expansion progressing as planned.
ASM-HHV manufacturing facility commissioned.
Solar equipment prototype completed.
AI and wireless capability acquisitions completed.
Government-backed manufacturing expansion approved.
Strong manufacturing utilization and continued growth in DLM.
Key Milestones Ahead:
Q2 FY27: First invoicing for solar equipment.
Q3–Q4 FY27: Repeat orders and regular revenue from solar equipment.
End of FY27: Demonstration of polysilicon process and crystal puller facility.
FY28: Commercial revenue from crystal pullers.
Next 2–3 years: Execute ₹1,200 crore expansion plan and scale manufacturing capabilities.
Overall Assessment:
The AGM strengthened the long-term investment thesis by showing tangible execution rather than only future plans. Management provided clearer commercialization timelines, demonstrated progress in manufacturing expansion, and reaffirmed its strategy of moving from engineering services toward design-led manufacturing, semiconductor equipment, AI-enabled industrial solutions, and proprietary technology development.
The next major proof points will be successful commercialization of solar equipment, execution of the manufacturing expansion, commercialization of crystal pullers, and eventually meaningful revenue from semiconductor equipment and proprietary products.
Thank you Priyatham, for writing the updates from AGM.
One thing i want to point out here, this company have massively scaled up their DLM segment in last 2 years. They achieved this vertical growth without investing much capital in manufacturing segment. Most of the investment in manufacturing was trial and qualification expenses happend over last 4-5 years , not a one time capex model expenses. Even recent fund raising also mostly used for acquisition in different segments.
Finally now they are going to invest big for manufacturing segment, i believe this massive capex will take this company to a different trajectory. Few years back a friend visited semicon india exhibition and enquired about this company to a official from a semicon equipment behemoth. Officer replied Asmtech is our competitor.
Story is just beginning.
@shanid, it really amazes me how the company has seen a massive step change in its revenue, with a very small addition to its asset base. I then wonder what the asset turns will be on their newly commissioned assets once this large phase of capex is completed in say two years. I agree that the story is just beginning.
@Priyatham, thank you so much for putting together that summary. It helped clear a few doubts that I had from the AGM. The future looks bright.
I wish to share my notes from the AGM below
ASM Technologies intends to play a critical role in India’s manufacturing and automation journey. It intends to deepen its presence in the solar, semiconductor, electronics, automotive and medical industries.
Also, when it comes to applications of AI, whether it’s physical AI, or industrial AI, ASM is keen to play ball. Its AI Assist serves as the company’s foundational intelligence layer, which can be used to assist engineers, operators and service teams by extracting valuable insights using natural language (with ever increasing multilingual capabilities).
The 20% investment in Myelin Foundry is generating great returns for ASM with its cutting-edge stack for Industrial AI.
The 51% stake in Asmaitha Wireless, a leader in embedded systems is increasing ASM’s expertise in hardware-software integration. It also gives the company access to the growing medical wearables market, and helps the company add smart wireless communications systems to its industrial equipment.
Over the next few years (2-3?), the goal is to complete a ₹1,200 crore expansion plan (both capex and opex) and scale up manufacturing.
The company has acquired 10 acres of land from the Karnataka Industrial Areas Development Board (KIADB), which will be used to create a design-led manufacturing (DLM) campus, that is slated to be operational next year.
The Ministry of Electronics and Information Technology (MeitY) has approved a ₹565 crore capex plan by ASM for the Electronics Components Manufacturing Scheme (ECMS). Contingent on the project meeting certain criteria, the central government will provide a 25% capex subsidy. Additional subsidies and incentives are being sought from state governments.
By the way, note how ASM is making a big push in the capital goods category of the ECMS. I was pleasantly surprised to see that their committed capex was greater than TEAL’s (whom I see as a real competitor in the solar/semiconductor/electronics space).
It was nice to see Prasanth Sakhamuri from Hind High Vacuum speak about the progress of the ASM-HHV joint venture. The JV is working on building a completely indigenous ecosystem for the solar value chain. They’re actively working on lower cost and more efficient ways to synthesize/manufacture polysilicon and monocrystalline silicon.
The equipment for polysilicon synthesis is considered to be ready to go. The goal is to manufacture this equipment and scale up its production in the next FY. By the way, as far as I know, there is no company in India that does commercial scale synthesis of ultra-pure polysilicon in India. Indosol is planning to commission a plant in late 2027, Adani is targeting FY28, and Reliance New Energy hasn’t firmed up its timeline yet.
Monocrystalline silicon work is at an earlier stage for the company. The JV is hard at work on crystal-pulling techniques and equipment. This sort of work is critical for India to become self-sufficient in this domain. There can be a lot of valuable intellectual property (IP) creation for the JV as a result.
Prasanth sir mentioned that client commitments were already in place, but he did not share client names, amounts, and I wasn’t sure if he was referring to equipment for polysilicon or monocrystalline silicon. He also shared a few milestones:
· Q2FY27 - Invoicing for solar industry capital equipment is expected
· Q3/Q4FY27- Repeat orders and recurring revenue opportunities (spares, service, etc.) for solar equipment
· Q4FY27 – Doing demos of the crystal pulling equipment (monocrystalline silicon)
· FY28 – Expecting revenue for crystal pullers, and the manufacturing of this equipment will require a brand new and exclusive facility
He also did mention how the first ASM-HHV plant has been commissioned. It was clear to me how the ASM-HHV JV is planning to build competence and credibility in the solar industry equipment space first, and then “move up” to the semiconductor industry, which uses similar equipment, but requires much higher levels of precision and expertise.
A ₹500 cr QIP is being planned.
The management didn’t disclose specific numbers or clients, citing NDAs, but Rabindra sir mentioned how the company’s order book is robust, and how the management has visibility in the 18-36 month range, depending on the vertical. He also mentioned that Q1 results are a clear indicator of how the business is faring.
ASM Technologies is getting a lot of visibility after the MeitY event, and is getting a lot of support from the government.
The company commissioned a new facility in Vietnam near Hanoi. The intent is to locally support customers there.
The MoU with the Tamil Nadu government has been signed. The next step is land acquisition, and this land will either be close to Chennai or Bangalore.
The company is having a J-curve moment as its investments in manufacturing are now starting to yield great results. I am of the view that this is just the beginning, and to be honest, I am very impressed with how this pivot to design-led manufacturing is going.
ASM still leans on its staff in its services business to help with DLM work.
SmartFix 4.0 is an industrial IoT and AI-enabled precision workholding device and fixture system. It collects, transmits, and analyzes real-time manufacturing data to improve factory throughput. Its patent is still pending.
While ASM Ventures hasn’t invested in companies that have had unicorn like outcomes, ASM has learned a lot from the companies that it has invested in. These companies are often working at the cutting edge of technology.
Disclosure of holding: I kept buying shares in ASM Technologies from 2021 to 2023, with an overall cost basis of ₹227. I have a fairly concentrated portfolio and do not own more than 10 companies at any given time.
Hello Priyatham, Thank You for the AGM notes, very detailed indeed. I was trying to model FY27 revenue, your notes mention current capacity are already 90% utilization and new facilities + products will slowly ramp up from Q2FY27 onward. Can the company grow 60%+ for entire FY27?
Hi Ankit, Congratulations on your journey and wealth creation with ASMtech, I went through the ARFY26 and all insightful notes here, it seems they are gearing for something much bigger and lot of optionalities at play here. Since you are have been tracking this company for long, would be great if you can share your thoughts on management execution with so many new technologies at play here and do you see they requiring another fund raise down the line? Lot of money stays stuck in inventory in this businesses. Have you been able to model a northstar number in next 2 years once everything they have outlined starts contributing, current business for this year might take them to about 800 cr for FY27? Certainly with all put together in 2 years the number could look much bigger, isn’t it?