Warrants have 25% upfront payment meaning 15 Crores is already given. Now obviously they can’t convert those warrants if price stays depressed. But I have another theory.
Why would the promoters go for warrants when price has fallen 60% from ATH. Surely it is to keep up the morale on street. But no one cares for retail investors. Why would the owner care to go at such lengths instead of buying directly from open market? He already has >400 crore in the bank and can weather all storms. I think the institutions who participated in the QIP are not taking this fall lightly. They have access to the management and can easily ask them to explain why their investment is cut in half. Retailers may continue to hold on even in such dire situation but institutions cannot. I forsee a forced selling by the smart money if price remains depressed for too long. And this is the reason why management is going to all tv news channels and spinning yarn out of thin air with statements like we are biggest beneficiary of AI. They are under tremendous pressure to deliver at this point.
Above is just my theory which may be wrong. I can further average my price but I refuse to put money in a hole now. Will only average if signs of bottom formation emerge.
So, the main argument of the management against AI is that they are a product company and not a service company, so AI will only help them making products and reducing requirements of time and manpower in medium term.
I am not from software or IT background and I find the explanation to be explicit.
I’m a developer in a fintech company, and that explanation is a very valid one. After adopting AI assistance, the pace has definitely increased, things that would usually take 2 weeks to implement now takes 3-4 days.
My guess is that the market is concerned about people losing their jobs because of AI , which will affect the economy badly.
I’m of the opinion that AI will only help people do more, which will lead to increase in productivity.
People shift to extremes. Same people who though AI will greatly increase productivity and help IT companies with AI led business are now fully pessimistic. Poor Zaggle is caught in the crossfire being neither an IT company nor a SaaS company and yet punished by both kinds of fearful investors.
Did the Industrial Revolution cause everyone to lose their jobs? Did the internet or digital revolution do the same? Old jobs will go and new ones will take their place. Does Zaggle only provide services to IT and SaaS companies? These arguments do not make sense.
SEBI considering use case of prepaid instruments to be allowed for MF investments. Don’t see major adoption here unless tax benefit is allowed which is not going to be case with IT Act trajectory.
I liked the rest of your argument, however I could not understand this part about looking like an aggregator and not able to demonstrate their value to customers. could you clarify/ elaborate?
This one’s an unnecessary nudge & over-scrutinising a company.
Acc to the IAS they are doing what govt rules have mentioned.
The end result matters when capitalising something. If the software were developed for internal consumption, your point is an valid argument.
But, if this software is developed to through which they gonna have monetary benefits, it should be included in assets rather than an expense.
Pls refer IND IAS 38.
(Under accounting standards (like IFRS IAS 38 or US GAAP ASC 350-40), companies cannot expense all development costs immediately if the software is expected to provide economic benefits over a long period.)
In such cases only research cost are to be treated as expense.
One piece for the many “AI doom proponents”. India may not have the best AI models, but it sure as heck has many AI native engineers and talent.
”On the panic in software stocks, LinkedIn founder Reid Hoffman dismissed the idea that everyone will write their own software as “a distinct flavor of foolishness.” Hoffman adds that “Jevons’ Paradox will do what it always does” — as software gets cheaper, people will use disproportionately more of it.
That should mean more work for software engineers, not less. (A recent HBR study seems to confirm this intuition.)
Also this week, Walter Isaacson noted that “AI has created about 1.2 million new jobs over the last two years.” He expects that to continue: “It’s going to create more jobs than it destroys.”
An aggregator is essentially in a way similar to wholesaler. If you look at the Propel business related to gift cards they are buying from Amazon/Flipkart and selling to Corporates. This is essentially nearly 40-50% of thier reported topline with 6-7% Gross Margin. They value add in managing the channel reward process throught thier software- so its not pure wholesale. However, the market perceives it like that as they are not able to demonstrate value of the software either by driving SaaS revenue or higher gross margins in this business. Prepaid cards too show similar phenomenon. It is not reported at transaction value but at take rate, which according to management is around 1.8%. Of this thier gross margin is 33% if you take out the cost of incentive (accounting wise it is below the gross margin, but for practical purpose it is essentially like cost of sales only). Here too its extremely competitive and to acquire customers they need to give out high incentives and business wise they buy from banks and sell to enterprises. Again the value of software is not visibily demonstrated in terms of returns.
Thus valuation suffers. To be honest, without stickiness created from software, they could lose this business too and have even more deeper price wars, and hence there is value. But that value as measured in terms of ROCE, ROE, gross margins, EBITDA margins etc - the typical measures used by analyst, it doesn’t cut it. So they get aggregator kind of valuations. As they improve their EBITDA on reported basis to 12%+ and become decently operating cash flow +ve at that level, their valuations should rapdily improve.
If you look at thier guidance of FY27, standalone growth to 25-30%,I think they are trying to reduce the growth in gift cards and drive up EBITDA margins. This could be partially because they want to show the street better operating cash flow and also could be because at consolidation - the subsidiaries are likely to be in cash burn situation, so they want margin to absorb that burn at consolidated level. Or maybe its also their inability to grow the business at volumes beyond that while maintaining profitabilty. Most likely a bit of all. Management should be questioned in the Q4 concall on these matters to get better clarity.
Zaggle provided notification to stock exchanges about resignation of its CFO and cancellation of its 51% acquisition of Effiasoft declared last year on 27th March 2025. Not sure if these 2 events are connected to each other. But its good to know that company is assessing its priorities in the changed environment
Canr comment much on CFO. Regarding canceling the acquisition, it kind of fits with the “rapidly iterate and deliver” new SaaS products with the help of AI which can be done internally at a cheaper price than acquiring Effiasoft.
Company in the future should focus on acquisitions that expand the customer network, increase bank relationships .. I.e, distribution
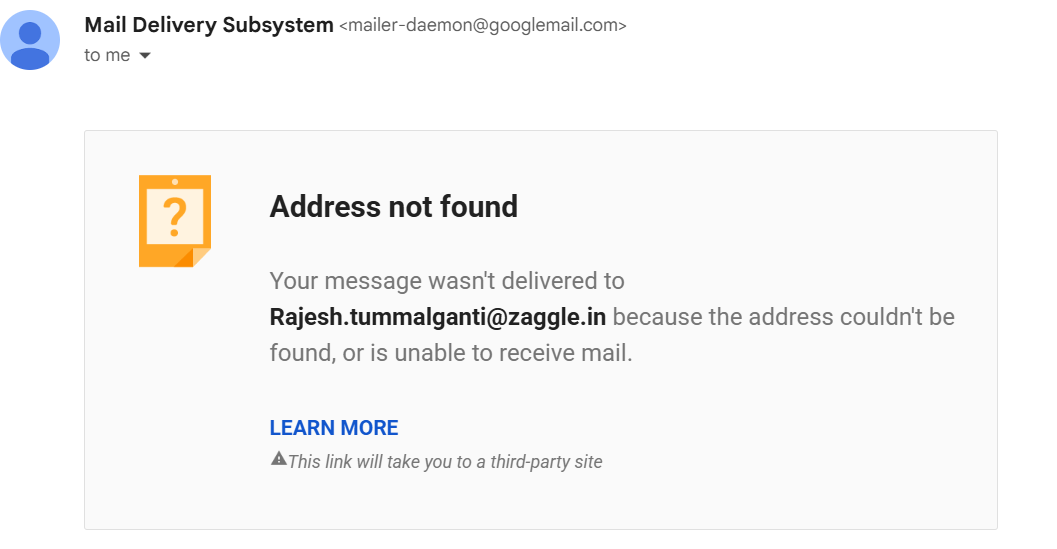
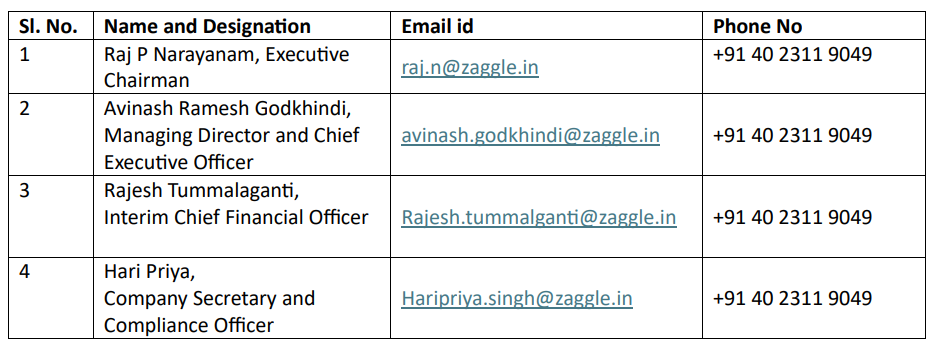
Its been a month and no response from investor relation. I decided to escalate the matter to top management. Lo and behold the email id of interim CFO mentioned in latest announcement does not work.
Software with embedded workflow is a moat, because it raises the cost to change - there isn’t enough incentive for companies to change. Some time stickiness is not just desire to keep, but could be lack of incentive to move away. Zaggle with cheap software provides that. Yes some enterprises could always churn, but not a significant lot and not together.
Relationship is not a moat, it’s an enabler for cross sell - you have a foot in the door and can get an appointment more easily. If an enterprise has good reason for change, believe me, relationship is the least of the worry. Most of these are transactional and not strategic anyway. Everytime a new manager takes charge, the deal is always questioned and to some extent relationship is reset. At that time not having a sufficient reason/incentive to change and/or a high dis-incentive to change is the greatest enterprise moat.