This seems to be old article dated May 28, 2010
1 Like
Poor set of results for tatva chintan.
Y on Y sales down from 123 cr to 90 cr. Op profit down from 35 cr to 11 cr . And net profit down from 32 cr to 7 cr.
Consistent q on q decline in net profits since Sep 21 quarter.
Stock price still holding firm inspite of many poor quarters.
One of the reasons could be low retail holding at 6% with promoters holding 79% stake and rest held by DII/FIIs. In fact DIIs have consistently raised their stakes in past few quarters.
I remember similar excitement post listing in advanced enzymes, where market participants were excited a lot and results did not come through. Stock price corrected and has not rewarded shareholders till now. Here too FIIs stake has gone up from 11% in Dec 2019 to nearly 22 % as on Sep 22. And the big fund raising stake is Nalanda India fund. Nalanda stake was 4.74 % from Sep 2020 to Dec 21 post which they kept increasing stake each quarter and now it stands at 8.91%. Stock price consolidating above 61.8% retracement level (at 252) to the previous rally from low of 98 in March 2020 to a high of 503 in May 2021.
30 Likes
Tatva chintan Q4 & FY 2023 concall highlights:
Results:
Q Sales of 124 cr. Rise of 22% yoy, yearly sales of 423 cr, a degrowth of 2%.EBITDA margins at 13% vs 22% in q422.
My take: poor show continues despite management’s earlier forecast of good growth from q423. Reason being stockpile of high cost inventory and low demand for SDA which was further aggreviated by drop in RM cost leading to drop in realisation.
Product wise performance & forecast:
SDA:
Contributed 30% to revenue, a decline of 43 % yoy.
Entire old inventory will be consumed by may end(this made me believe that Q1 should also be lackluster). SDA demand to improve from H2fy24. Submitted commercial trial order to large customer for 4 different applications. Expect full scale commercialisation from jan 2024.
PTC:
Grew 46% yoy( as sda demand was almost zero in q2, q3, they sold more ptc).
Electrolyte salt:
Now contributes 4% to revenue compared to 1% during ipo. This year many customers will go for trial order and full scale commercialization from fy 25.expect revenue to double by fy25.
PASC:
In q424, all three products using continuous flow chemistry (1.product for metal extraction. 2.dehydrated monoglyme for battery. 3.agchem intermediate which is key RM for many advanced agchem intermediate) to go into full scale production so expect exponential growth from q4.
BFR:
got commercial approval from 2 large customers. More approvals are in progress. But due to sudden drop in bromine proces and low demand, customer uptake is verylow. Initially we will go for low margin base products and then move to more advanced, higher margin FR.
Projections:
Will grow 20% in value terms fy24 with 18-20%
(Their ideal margins are 22-26 % but as current FR are low margins, they will consume some gain and secondly new capex is adding to cost as currently plant is running at very low levels. It will run at optimum levels only from q3/q4)
margins. Actually in volume terms, growth will be much higher but recently, realisations have dropped by 18-20% due to fall in key RM prices. So taking this drop in realisation into count, we will grow 20%.drop in revenue will not have any impact on ebitda margins.
Expect to grow by 75-80% in fy 25 from current levels.
Segment wise fy 24 growth forecast:
SDA: In value terms, it will be flat due to low realizations. Might be some volume growth. Euro 7 norms will increase demand for SDA.
PTC:likely to be flat.Have submitted for new applications. If that materializes, might see some growth.
Electrolyte salt:will see growth close to 100%.
PASC:management did not mention but my take is it will show good growth as this is rhe only segment that has shown consistent performance.
BFR: Sales can be near 50cr.By fy25, expect sales of about 200cr.
My take:current poor performance is not likely to last long . It appears to be a case of good company in bad times which is what i look for. But valuations are stretched. At cmp there is no margin of safety even if company beats management forecast for fy24. So for me its wait and watch.
Disclaimer: I do not have any holding in company as of now.
9 Likes
Tatva Chintan reported sales growth in June quarter and marginal improvement in operating margins. But its below the line items like depreciation ( related to higher capex) which are acting as a dampener on the results at net profit levels.
This company is a classic example of a hot stock in a hot sector. When chemical sector was the rage, this company was touted as a company with competitive edge, and entry barriers etc. These terms are very important to understand and apply. By themselves they are not a license to pay crazy valuations. And Tatva Chintan began its listing journey enjoying crazy valuations. When its valuations were at peak,
I guess peak market cap was around 6500 crores plus. And sales were a mere 400 crores. A lot of extrapolation was done about capex coming on stream by X number of years and sales figure being double that of the sales at that time. And then margins were also extrapolated based on management guidance. And based on that, a lot of experts predicted that at ABC valuations, it would be justified to buy this company.
As of now valuations have nearly halved ( still not there, but just about there. ) And still no clear light at the end of the tunnel. While it may be one of the better chemical companies with some kind of moat, or competitive advantage, the key take home learning for us is that it was a " Hot stock in a hot sector" … A classical example of what Lynch preaches in his book.
Maximum money is made when a company is bought at cheap (read commodity type company valuations) valuations, and it reports growth and profits that are expected from a speciality or niche company. Majority of the money is made from re rating, and the other big chunk from actual growth.
Now apply exactly reverse logic to above paragraph. Imagine a company bought at 100 PE (according to screener this used to quote actually at 100 PE or close to it), delivering negligible growth, and swift contraction in valuations to sub 40 ( as seen during April 2023) . The key thing to note here is that even if the company starts delivering growth at a reasonable clip, one cannot expect valuations to reach levels of 100 PE…
The other tell tale sign was an extremely appealing IPO happening during sectoral fancy. One needs to beware of these kind of IPOs. We have seen this kind of history being repeated off and on … In 2006-2008 era it was infra and real estate companies. In the run up to 2015 pharma peak it was pharma companies. Nowadays its railways, defence, power etc. And these things will keep on repeating with old wine in new bottles.
So starting valuations matter a lot while evaluating a company. For a time being they do not matter in a hot sector and a hotter stock. But after market wearies of lacklustre results, prices tend to correct or go sidways. Either case the capital invested does not produce any return.
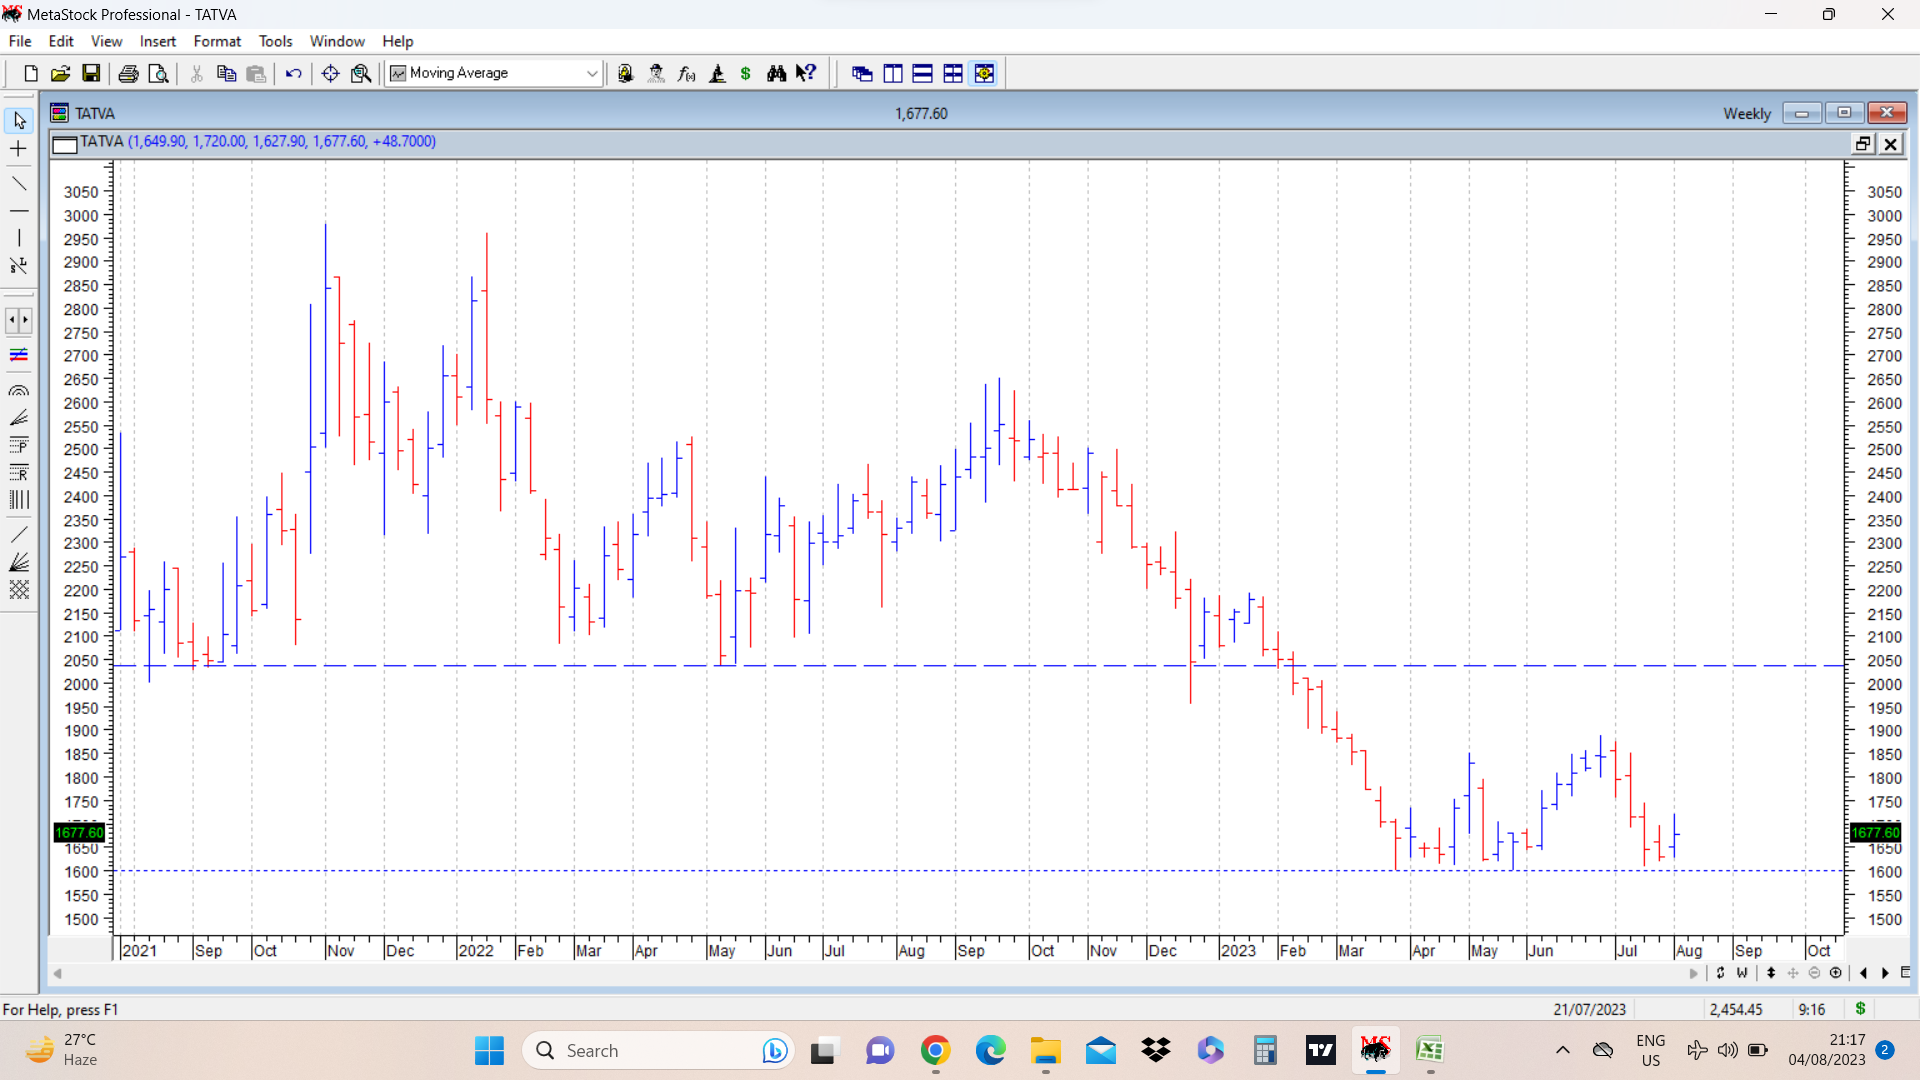
Attaching a simple chart where breach of post IPO lows was an indication to exit. That level was around 2000. After that stock price has not gone close to those breakdown levels. New next level to watch is level of 1600 or thereabouts. Just for record, stock listed on bourses in July 2021 and its more than 2 years since then. Folks who bought post IPO and listing, considering this as a company with moat etc are still sitting in losses and their capital has not produced anything for more than 2 years, and while a lot of other stocks have doubled or tripled or more.
24 Likes
@hitesh2710 may I know view on this technically, please? Seems to be forming a bottom at around 1620?
Disc: taken positions at 1620-1650 levels.
As of now there is no evidence of change in trend, (stock is in downtrend.) Need to see if recent bottom holds and any rally materialises. I think level of 1600 remains crucial . One also needs to review fundamental prospects of the company.
5 Likes
Can’t agree more with @hitesh2710 sir on valuations. No doubt tatva has differentiated products that are not easy to manufacture.I have liked the company because of its technical expertise, technocrat promoters and expanding product portfolio but did not enter due to crazy valuations. Margin erosion led to decline. Main reason for erosion is low demand for SDA’s.Although now demand has stabilised to an extent, but their current SDA’s find use mainly in auto emission control. Auto being highly cyclical, i think such margin erosion can repeat. They are trying to add non auto application but it will have limited scope.
On positive side, if management guidance of 100% revenue growth from next year onwards with stable margin holds true, i feel company should rerate.
Disclaimer: Have a tracking position at 1486.
3 Likes
hi folks! haven’t seen you all discussing the stock quite much in recent times.
I came across this stock when it IPOed but I didn’t invest although liked its characteristics.
I recently bought the stock at around 990rs.
Why now? Let me introduce you’all to my thought process
I have an experience of around 3 years in the markets, and when I started in the markets at that time the hot stocks were pharma and chemicals, so invested a lot of money there and on net levels didn’t make any return.
Things I learnt from my first sectoral cycle :
1.Valutions matter
2.Brokerage reports are sales reports
3.Never invest at peak margins, peak earnings, peak valuations (even if its a structural business, look for temporary headwinds to invest so that you can get a good valuation multiple)
“Its the earnings that break or make the narrative. I like to be placed in a stage where the earnings start the narrative. and its the narative that gives you speculative returns alongside earnings growth” ~ me 
Lets apply my learnings to Tatva Chintan while looking at some ratios:
- The business is trading at 3.25x Price to Book , Average ~ 7x
- RoCE less than 10% for 2 years now.
- OPM (17%) lower than average ~ (20%)
Now it clearly shows that the stock is going through an earnings downcycle and the stock is falling continuously but I believe enough pessimism has been built enough around it. I have made a tracking position.
How I think differently from the market at this point is:
- I think the revenue has bottomed out in FY24 (0.9x asset turns, 2.6x asset turns bull times on a much smaller asset base)
- I could be completely wrong with the first point so let’s check survivability - the business has no debt (due its recent equity dilution xD) and lil cash too so I think it can survive in one year of downturn.
Now lets look at optionalities :
- A large part of revenue can come from the other part of business (PASC - molecules commercializing) in next 1 year (biggest and only optionality for me) (management has guided for next 6 months but I have also taken a cushion of another 6 months in my assumption), one must note that in the previous bull run of the stock it was the SDAs (major part of business) which gave a splendid performance. it would be a blue-sky situation if both PASC and SDAs do well from here.
- Euro 7 norms to tentatively start from next 1.5 years.(good for SDA business division)
- China’s GDP showing signs of lil recovery. (GDP growth and Commercial Vehicle sales are correlated) (good for SDA business division)
Risks:
- The working capital cycle is very baddddddd. (which makes me not be a permanent owner of the business) (I just want to play out the cycle in this business)
- Change in end use of the application (I am unaware on this, neither the management has told me anything about it. sus)(still let’s hope for the positive)
- PASC molecules do not commercial (I will sell immediately)
I have used simple principles of a cyclical investing approach for this business because I know my circle of competence. I cannot understand the chemical business because of their complexity.
fingers crossed, I am optimistic about the stock performance 
16 Likes
Red sea crisis over & now better logistics cost & new plant is operational this month. Debt almost 0 & reserves, capex got improved in whole history of business. EV battery solid part is getting tractions.
1 Like

Plant Closer Notice
VS

Hoping this will reduce the impact! but I’m not sure about what they are producing in Ankleshwar Plant
TC recently popped up in one of my bottom-up screeners
Know very little about this but this laggard could just be a reversal candidate - may be all can benefit from turnaround story
Looks like only patient IPO investors would have survived this 2 year long price / time / earning correction
@darwin_ate_my_dcf - good note, do share any new views / assessment since your post
@vinayakanet & @xplorechintan - sounds like one cancels another
3 Likes
Helloooo! We are back again at this comp. It did pretty bad, though. It recently went into net loss, which makes it even more interesting
I went through their Q2FY25 concall and here are the updates:
Weak Demand Environment
They are primarily dependent on 3 Global industries since most of their revenues come from export. These industries are :
- Heavy Duty Commercial Vehicle (demand for SDA is correlated to this)
China HDCV Sales (22% down), UK (9% down), EU (5% down) - Agrochemicals (PTC and PASC is correlated to this)
- Polymers (because their products find application in polymers)
All 3 of these are doing pretty bad and facing headwinds. Management expects a turnaround by Q2FY26. Management says that Q3 will be bad and from Q4 gradual pickup will be seen. but its just a guesstimate by them. Nobody knows when things will turn around. One can simply follow management’s commentary for demand revival.
I believe that when information will be clear on demand revival, many mutual funds are gonna come and buy because the triggers are placed, its just that we need the demand to come back.
I am attaching a screenshot for updates on each line of business

I am not saying its a brilliant business. IDK. All I know is that it will be a good trade. Triggers are placed , all I am waiting for is the demand to revive. And believe me, its not only me, there are many others (be it institutions or individuals) who are waiting for the same. Because the business listed at P/B - 12x. which demonstrates that it has been a very popular stock among investors. Currently its trading at P/B - 2.6x. Demand revives and people will come pouncing on this one!
Disc : Invested (3% of PF) (Will be increasing allocation as information becomes clear)
7 Likes
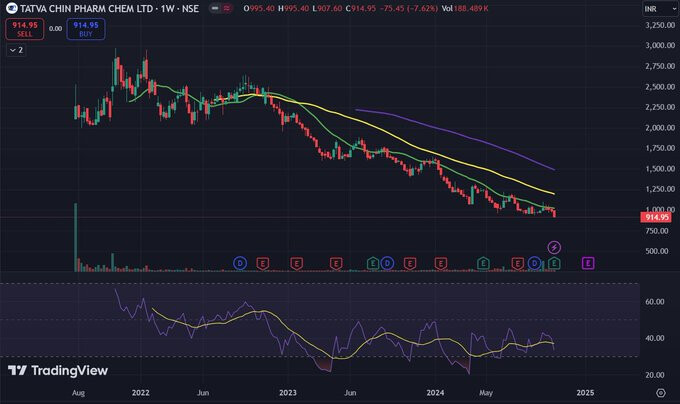
the trend still looks weak
Theoretically yes, somewhere in medium or long term things will likely turn again (everything is cyclical). It was ‘cheap’ at 1200,1100,1000. Now cheap has gotten ‘cheaper’. Too early is indistinguishable from wrong is what folks say.
Question is why is this a good investment to invest money NOW?
2 Likes
I used to track this co., in the past and used hold few from the IPO allotment. Although a small/swing account holding, i booked out early sometime in 2022. The business was IPO’ed at the peak of chemical upcycle, and was priced to perfection i believe and is stuck in the headwinds across chemical sector. Now, the bottom is anyone’s guess, but i believe the business/segments they operate worth tracking and one has to analyze how their expansion plans including new molecules perform, along with the general chemical sector’s rebound.
I just put together last few AR’s and latest Q’s result to get some idea on its product segments revenue trend and performance.
Q2 PERFORMANCE/EARNINGS QUALITY
Continuing Challenges: TCPL’s financial performance in Q2 FY25 and H1 FY25 reflects the continuation of the challenges observed in FY24. This is evident in the decline in consolidated revenue from operations, which contracted by 13.92% in Q2 FY25 and 10.48% in H1 FY25 compared to the respective periods in the previous year.
Margin Pressure in PTC: The Phase Transfer Catalysts (PTC) segment continues to face margin pressure. The segment’s revenue declined by 30.1% in Q2 FY25. While specific segmental EBITDA margins for the quarter are not available in the provided sources, the overall decline in profitability suggests ongoing challenges in this segment.
SDA’s Resilience: Despite the challenging market conditions, the Structure Directing Agents (SDA) segment continues to demonstrate resilience, with revenue growing by 22.4% in Q2 FY25. This reinforces the segment’s strength and TCPL’s strategic focus on SDA as a key growth driver.
Profitability Decline: The consolidated profit after tax (PAT) declined significantly in both Q2 FY25 and H1 FY25. The PAT margin contracted to -0.80% in Q2 FY25, a substantial drop from 8.19% in the same quarter of the previous year. This decline is attributed to a combination of factors, including lower revenue, pricing pressures, and potentially higher operating expenses.
Cash Flow Impact: The decline in profitability has impacted TCPL’s cash flow generation. The consolidated cash flow from operating activities was negative in H1 FY25. This could limit the company’s ability to invest in growth initiatives or necessitate additional financing in the near term.
Table 1: Segmental Revenue Contribution (%)
| Segment | FY23 | FY24 | Q2 FY25 |
|---|---|---|---|
| Phase Transfer Catalysts (PTC) | 34.02 | 27.33 | 30.23 |
| Structure Directing Agents (SDA) | 30.32 | 42.38 | 32.45 |
| Electrolyte Salts & Solutions (ESS) | 3.93 | 1.29 | 1.49 |
| PASC | 31.73 | 28.93 | 35.56 |
| Others | 0.15 | 0.07 | 0.60 |
Table 2: Segmental Revenue (₹ Million) and Insights
| Segment | FY23 | FY24 | Q2 FY25 | Observation |
|---|---|---|---|---|
| Phase Transfer Catalysts (PTC) | 1,432 | 1,067 | 252 | Declined in all periods due to aggressive pricing competition and lower raw material prices impacting realization. |
| Structure Directing Agents (SDA) | 1,276 | 1,655 | 270 | Showed resilience and growth, driven by robust demand and TCPL’s position as the second-largest global manufacturer and the largest in India. |
| Electrolyte Salts & Solutions (ESS) | 165 | 50 | 12 | Experienced a steep decline due to a weak Chinese market and delayed procurement by a major customer, underlining the segment’s susceptibility to market-specific fluctuations. |
| PASC | 1,335 | 1,129 | 297 | Remained relatively stable in FY24 but declined in Q2 FY25, suggesting resilience but not complete immunity to broader industry challenges |
| Others | 6 | 2 | 4 | Consistently contributed minimally to overall revenue |
| Total | 4,208 | 3,904 | 834 | Reflects overall industry challenges in FY24 and a more pronounced decline in Q2 FY25, primarily driven by pricing pressures in PTC and demand fluctuations in ESS. Despite this, SDA emerges as a growth driver. |
KEY OBSERVATIONS
SDA’s Ascendancy: SDA’s contribution to revenue significantly increased in FY24 and continued to grow in Q2 FY25. This is noteworthy given TCPL’s prominent market position and the niche nature of the SDA sector.
PTC’s Vulnerability: The sharp decline in PTC revenue across all periods highlights its vulnerability to pricing pressures and fluctuations in raw material costs.
ESS’s Dependence: The ESS segment’s performance is heavily influenced by specific customer and market dynamics, particularly in China, making it prone to volatility.
MANAGEMENT STRATEGIES
Continued Product Development: TCPL’s ongoing focus on developing new products across various stages may help counter revenue declines in certain segments and drive future growth.
Capacity Expansion: The expansion of the Dahej SEZ facility is expected to enhance operational efficiency and support future demand growth, potentially benefiting all segments.
Overall, while Tatva Chintan faces challenges due to industry dynamics, its focus on SDA, coupled with product innovation and capacity expansion initiatives, suggests a strategic approach to navigating the volatile market and seizing emerging opportunities.
Note: The report is filtered through AI tools; please correct me if there are any errors or omissions.
Disclosure: Not invested. Post purely for study purposes. Do not take any investment decisions without consulting a registered advisor. thanks.
4 Likes
Only insiders know if it’s good for “NOW”. I am no god or insider. I am simply looking for more information about things turning around for this company.
One recent revival optionality can be Trump focussing on infrastructure and oil (as specified in his manifesto). This can be a good news for their SDA division. I am awaiting management commentary on this in their next concall.
Thinking probabilities. nothing else. Only the future will tell if it was “Wrong” or it was “Too early” or “Too late”
3 Likes
Hi Guys , I recently started reading about this company. Any idea what’s the peak revenue they would be able to generate with all the capex put so far ?
In Q1FY25 call they said their max quarterly runrate could be 150cr-170cr provided prices remain stable.
I want to understand whether this is including the Monoglyme plant for which they are spending 105cr.
Also they have said that the pharma products alone would be 250-300cr opportunity by 2026.
So anyone can help me get a broad picture on the overall peak revenue potential of PTC, SDA , PASC , Monoglyme & Electrolyte plant all put together ?
Thanks!
2 Likes
I have gone through the entire thread, and a couple of investor conference calls for both the half-yearly and yearly periods, and all I see and hear is a disappointment. While I consider myself a fundamental investor, I find it difficult to trust the moats, business strengths, or opportunities in this case. There have been too many execution mishaps, excessive commentary, and a tendency to push narratives rather than deliver results.
My goal was simply to identify investment ideas in this market. However, after all this effort, I realized that for this particular stock, it’s best to leave it to price action. If it decisively crosses 950, one could consider a buy trade with a small stop loss, aiming for short-term gains before moving on to other opportunities. That holds if it does not drop to even a newer low of 500 levels.
Disclosure: Not invested.
7 Likes
Q3 FY 25
Sales flat qoq and yoy at 85 CR. Ebitda margin at 8%. Negligible PAT. Company continuous to under perform. I have been tracking this company since listing and I have no doubt about its moat but promoter need to communicate more honestly with market. Since Pass 2 years company has been under performing but during every con call management paints a Rozy picture.
conference call highlights:
Phase transfer catalyst: onboarded 2 new MNC customer for newer application. this application is potentially largest that we have got in PTC till date.
Structure directing agents:
Demand is still muted but we are seeing early signs of recovery. 2 new customers have started placing orders.2 more new customers will start the orders from April 2025. Raw material prices are not dropping further. the issue is on demand side .
Electrolyte salt: our customer in energy storage application has stabilized his new assembly line we expect good orders going forward. For electrolyte solution to be used in zinc battery customer has asked us to initiate pilot plant. Approval for super capacitor to be used in hybrid cars is also going well.
PASC:
3 new Pharma intermediate have been formally approved. Fourth intermediate will be approved in next financial year.
1 Agro intermediate has already been approved while 2 will be approved in this quarter.
We expect existing plant to run at full capacity around June 2025.New plant at existing site will come up in January 2026 .with this new plant we can reach total revenue of 900 crore.
Monoglyme: 1000 kg plant will be installed by June 2025. Once commercialised, we will have monoglime installed capacity of 2000 tonnes.market size is 12 to 15000 tons per year. Realisation In monoglyme is around $4 per kg.
Polymers: plant trial of one product completed. trial for second product is ongoing .approval process will start in February 2025.
Photochlorination: approval is proceeding well. Customer will visit in February. supply will start from April 2025.
Flame retardant market is currently very challenging due to very low prices of raw material. we will enter the market only when input prices stabilize.
We are working on product for semiconductor sector. But primary requirement is to develop Ultra high purity water with impuriity levels of less than one parts per billion. We have been working on this for past 3 years and we have reached 30-60 ppb. If we are able to achieve less than 1 PPB we will be first company in India to achieve this.
My take:
It’s a niche company with primary revenue from SDA.There are only 2 companies making SDA for zeolites globally .(Other one being sachem with 85% market share).But heavy truck sales slowdown has hit SDA sales badly over past 2 years.PTC’s are low margin.Electrolyte salt is promising vertical but it’s all still R&D which mgmt.is trying to publicize.
Pharma and agchem is a segment which will now contribute to revenue and profits in a big way.6 molecules are getting commercialised by april-may along with polymers.mgmt is very confident of good growth from next year but this mgmt is known for tall claims.PASC will definitely grow from next year but SDA’s must also grow for turnaround.Euro 7 is expected to increase SDA demand by 50%.
Disclaimer:Have a tracking position at 946.
5 Likes
-
Phase Transfer Catalysts (PTCs): PTC sales rebounded sequentially (Q4 ~₹389 m), driven by new adopters. Global PTC demand is growing (~5–6% CAGR)grandviewresearch.com, supporting Tatva’s leadership.
-
Pharma & Agro Intermediates (PASC): Generated ~₹327 m in Q4, up ~10% QoQ and 17% YoY (steady growth). A major commercial order and new facility for key agro intermediates (capable of ~1,000 TPA) to come online by Q3 FY26. Each new agro molecule has 3–5 year ramp‐up, providing multiyear growth (targets ~₹30–75 cr annual per product).
-
Structure-Directing Agents (SDAs – catalyst for diesel engines): Q4 SDA sales were ~₹346 m (+51% QoQ but –15% YoY). Chinese demand was suppressed by LNG truck fuel substitution but expects recovery as fuel economics change. Historically ~40% of SDA was sold into China; a cyclical switch back to diesel trucks should restore volumes (at peak 2022, China comprised ~40% of SDA sales).
-
Electrolyte & Battery Chemicals (ES): New energy segment is emerging. Tatva is commercializing high-purity electrolyte salts/solutions for EV/ESS batteries. Customer trials are progressing and commercial volumes are expected from H1 FY26 (pilot samples approved; electrolytes ramping up). The global electrolyte additives market is booming (projected to grow ~16% annually to 2033businessresearchinsights.com), and Indian peers (e.g. Ami, Neogen) are aggressively investing in battery chemicalsndtvprofit.comndtvprofit.com.
-
Geography: ~61% exports (Q4). Largest markets include China, North America and Europe (as inferred from product end-uses), though Chinese demand has been cyclical.
-
Capex & New Plants: Investing ~₹105–110 cr in brownfield expansions (new plant to be ready by Jan 2026). This will raise capacity especially in PASC (agro) and SDA lines. Tatva’s Dahej site has grown to a 48,000 TPA multi-purpose facility after 3 phases of expansiontatvachintan.com. (Plans for Pakhajan were not detailed on the call.) These expansions are timed to meet upcoming customer orders.
-
New Product Rollouts: Several new intermediates are entering commercial phase: two agro products started shipping in Q4, plus a polymer/PASC project that will launch by FY26. Each to contribute ₹30–75 cr annually once fully ramped (over 2–3 years). They are simultaneously developing two more agro molecules (pilot stages now).
-
R&D & Innovation: Specialized R&D (75,000 ft² in Vadodara) for high-purity and green chemistries. They are pioneering an “alternative route” for a major semiconductor chemical, claiming to be first globally to commercialize it and this capability opens a “game-changing” semiconductor chemicals vertical .
-
Sustainability & New Markets: Targeting sustainable industry trends (battery, semiconductors) and has onboarded key EV/battery customers (pilot supplies, approvals). Tatva plans to expand its electrolyte business from salts into high-purity electrolyte solutions. Digitization and biotech were not emphasized; no M&A was announced.
Industry & Macro Trends
- Energy & Trucks: A major swing in China’s heavy‐truck market: cheap Russian LNG made >50% of new trucks gas‐fueled in 2024, cutting diesel‐engine (and SDA) demandreuters.com. They note LNG prices are rising and expect a “reversion” back to diesel engines soon (this cycle has happened ~3 times before).
- Global Chem Markets: The broader specialty chemicals demand remained soft this year, reflecting subdued industrial activity. (Deloitte notes chemical production grew ~3.5% in 2025 after weak 2024 demandwww2.deloitte.com.) Tatva management said “the worst is behind us” but is cautiously watching market conditions and inventory destocking in customers.
- Semiconductor & Electronics: A semiconductor upswing is anticipated. (Deloitte forecasts ~19% global chip industry growth in 2024www2.deloitte.com, and semiconductor chemical markets are tightening.) Ultra-pure specialty chemical entry as timely, given the electronics recovery and clean energy trends.
- Inflation & Pricing: Input cost volatility remains a concern. Raw‐material price drops have hurt Tatva’s realizations (management cited 20–35% Y/Y price slides in core catalysts). Conversely, modest RM inflation into 2025 could help margins.; no specific regulation as a near-term risk.
- EV & Battery Push: Government support for EV/battery production is a tailwind. The domestic battery market is projected to grow from ~20 GWh (2022) to ~220 GWh by 2030ndtvprofit.com. Tata’s focus on battery chemicals aligns with industry momentum (peers like Ami, Neogen are investing ₹300–1500 cr in electrolyte/additive plantsndtvprofit.comndtvprofit.com).
Analyst Q&A – Noteworthy Qs & Responses
- Fixed Costs & Margins (ASK): Q4 margins remained flat despite higher volumes. Producing four agro intermediates simultaneously (to meet urgent customer needs) caused “operational inefficiencies” – wasted solvent, suboptimal conversions and utility bottlenecks. They did not give detailed fixed‐cost breakouts or new margin guidance, but stressed these issues are being resolved over the next 3–4 months.
- SDA Demand & China (Mirabilis): Chinese SDA demand (noting a surge in LNG truck sales). LNG trend (citing exactly the 3× increase in LNG trucks) and customers expect a rebound as gas prices risereuters.com. They noted that ~40% of Tatva’s SDA once went to China – so any switch back would sharply boost volumes.
- Future Margins (Crown): Asked about 20% EBITDA margin guidance, MD Shah clarified that full‐year FY26 is targeted at ~20%. They expect H2 FY26 to be much stronger (bookings are back-end loaded as new products ramp). Follow-up on 2–3 year outlook elicited that the new agro products and other segments provide “a multi-year runway” (each could be ₹30–75 cr/year at scale).
- Capex Utilization (Reliance): On asset use, two classes of assets: an SDA‐dedicated assembly line (expanded recently) and conventional reactors (used for all other chemistry). The SDA plant was underutilized (~30% in 2024) but is now ~60% in use and should run ~60–70% through FY26. Other plants are ~80–85% utilized. Struggled to quantify the SDA‐line’s share of gross block (citing tricky math), but conceded current ROCE is low until volumes rise.
- Volume Miss & Strategy (Retail Investor): FY25 growth guidance was missed. Realizations/volume issue: they had expected ₹410–415 cr top-line but fell short (~₹385–390 cr) due to price declines. Global raw‐material prices are now stabilizing/upward. Another question on PASC guidance got a firm answer: “at least +40% growth in PASC and +40% in SDA” is targeted, driven by new commercial volumes.
Forward Guidance/Outlook
- Revenue & Margins: FY26 revenue to grow >25%, assuming robust H2 ramp-up. They aim for EBITDA ~20% of sales by year-end (full-year). Key drivers are the coming volumes from new agro intermediates, recovering SDA orders, and electrolyte sales.
- Capacity Utilization: Expect plants to run near capacity by FY26 Q2–Q3. The new agro plant (from Apr’26) should add to topline in H2. The SDA line is already improving utilization (~60%). Improved operating leverage is expected once scale is reached.
- Segments: Qualitative outlook is very positive – H2 FY26 is seen as a “turnaround”. No numerical guidance beyond mentioning each major new product ramps over ~2–3 years. They noted long-term drivers (EVs, semis, specialty pharma) remain intact, which should support multi-year growth.
2 Likes