
Just listened to TARIL conference call
Chinese needs to manufacture in India and
Tbea is the only company and they are already booked.
So Shilchar shouldn’t be impacted from this news atleast.
3 Likes
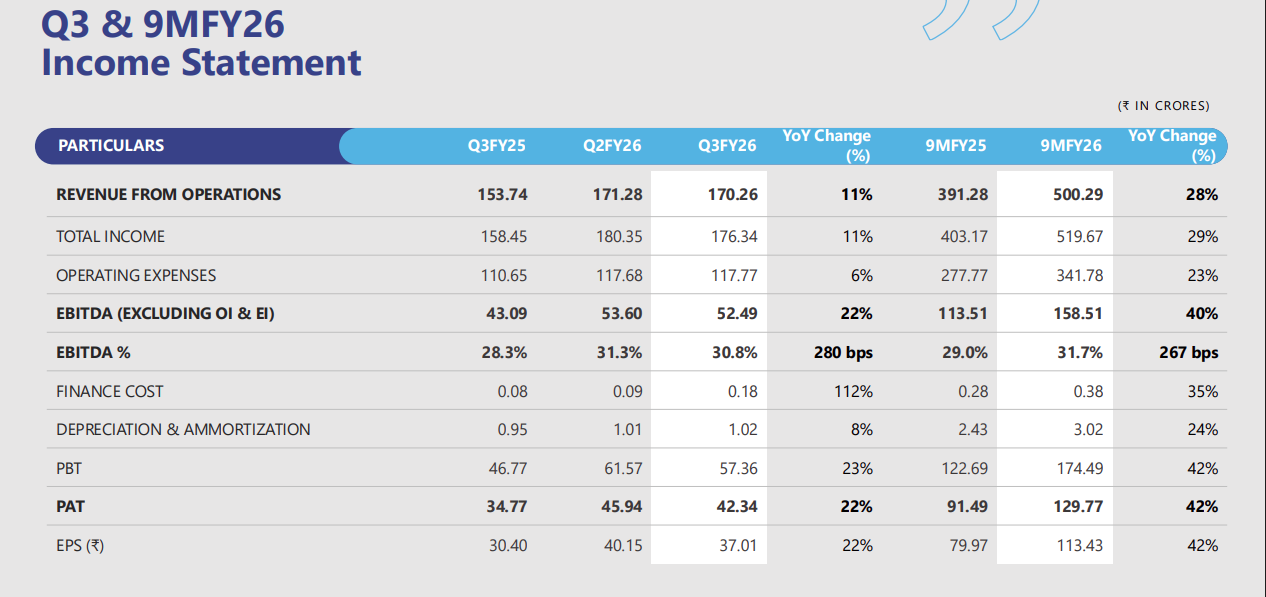
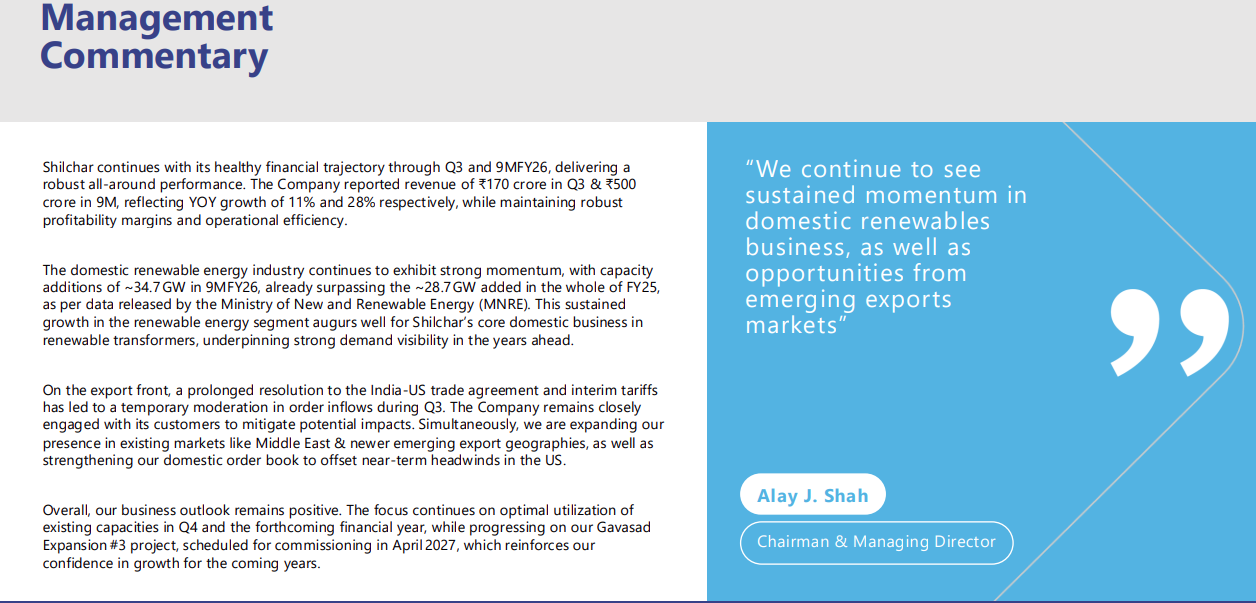
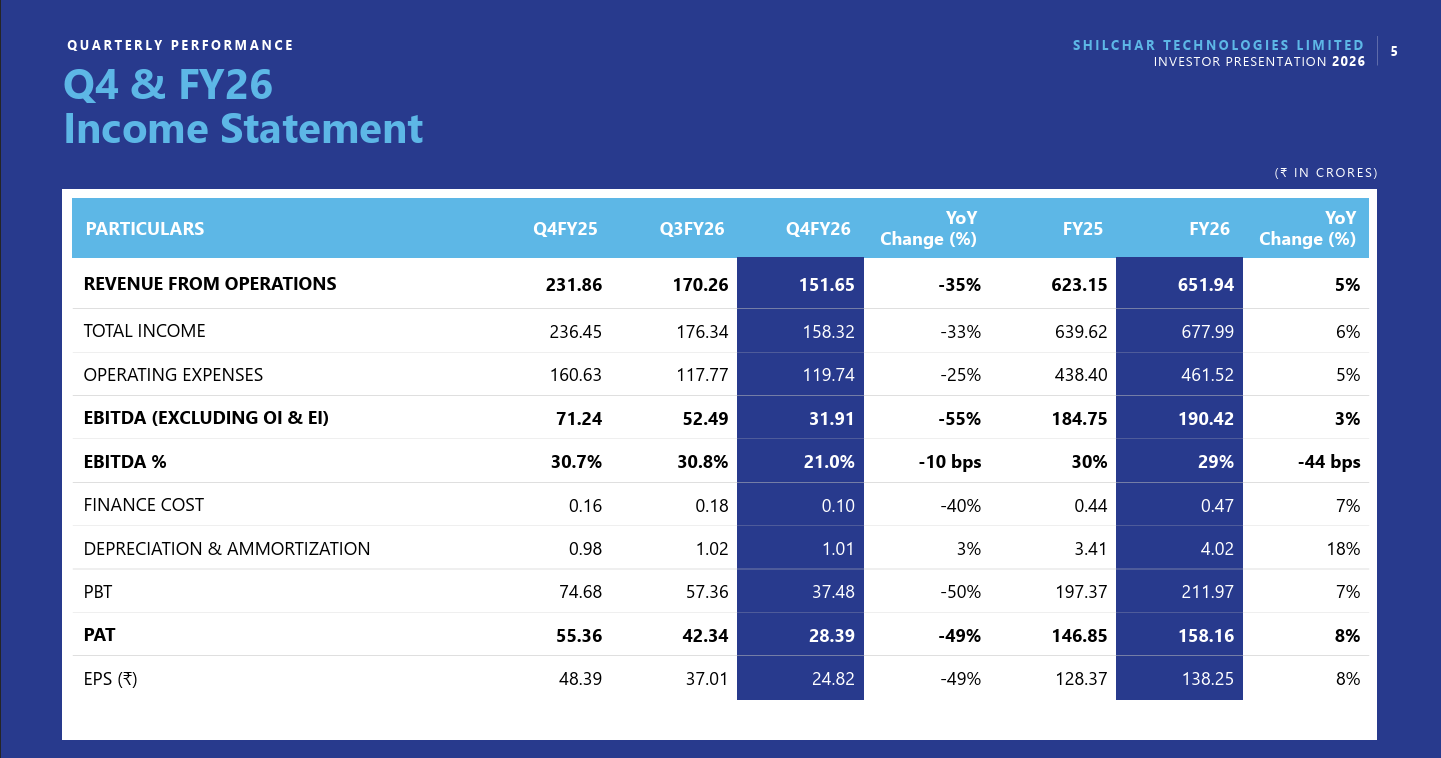
From the concall it is clear that the Sales and compression in margins is due to not being able to export and drastic increase in commodity prices.
The management states that they will be passing on the increased RM cost to the customer and they aim to do OPM margins in similar levels of 28-30% in the next financial year.
A conservative sales target of 800cr for FY27 was given.
4 Likes
Forward view: FY27 targets and key sensitivities to watch
-
Revenue target: management anchored INR800 cr for FY27; also stated conservatism and upside: “It will be INR800 crores to INR850 crores… It can reach to INR900 crores also.”
-
Margin stance: intent to normalize toward prior levels, contingent on (1) export mix normalization and (2) passing through input inflation via repricing/new quotes.
-
Key near-term sensitivities explicitly highlighted:
-
Middle East logistics normalization (dispatch catch-up already started in April).
-
Commodity inflation persistence (oil +100%, others +10–25% “nothing” has subsided yet).
-
Export order cadence (US demand recovering after tariff reduction; Middle East disruption described as temporary).
-
3 Likes
Although the margin compression was because of west Asia war crisis, can the margins really go back to normal in the next quarter?
Have been reading a lot of narrative around IDT transformers soon becoming commodity transformers, and only High voltage transformers , and equipment manufacturers like Bushing will be able to sustain pricing power. Is it true?
1 Like
Could you please share the link of those articles or reading material
Can someone ask this question in tomorrow concall.
”In May you said shipments had resumed, conditions had normalized considerably, you were confident about Q1 and did not expect major issues. However, the geopolitical situation itself does not seem to have materially improved since then. So what specifically had changed at that time that gave management confidence about Q1? Was that confidence based on actual shipment/order visibility and customer confirmations, or was it largely an anticipation that conditions would normalize? And what has changed now that gives you greater confidence that Q2 will be notably better?”
5 Likes
I listened to the Q1FY27 concall and below are my brief take on it:
- On the questioning about why they said Q1 will be better they explained that “ some shipments resumed in early April which led them to beleive situation will normalize but it all changed afterwards”. It sounds like an excuse to me.
- They are repeatedly saying the export orders are deferred, not cancelled so there’s no revenue loss as such. As soon as the shipping costs normalize, the exports will start flowing out. This is being hopeful because the current orderbook of 500 crores only have 30% export mix and that’s the hard data pointing towards margins being compressed for next 3-4 quarters atleas irrespective of currently deferred orders. Either the next quarter comes with meaningful order inflow on the export side or else Shilchar’s margins are compressed for good.
- Their current expansion plans and shifting focus to high voltage seem quite late and this also points toward their margins being an artifact of export mix majorly and design complexity of their custom made transformers secondary.
All in all, I feel very confused about the stock right now. Either it’s at the trough margin and it can bounce back superbly once logistics disruptions clear (that’s being hopeful) or the margins are structurally being squeezed given orderbook (leading indicator) shows changing export mix.
Please share your thoughts and views after this result season for this.
1 Like
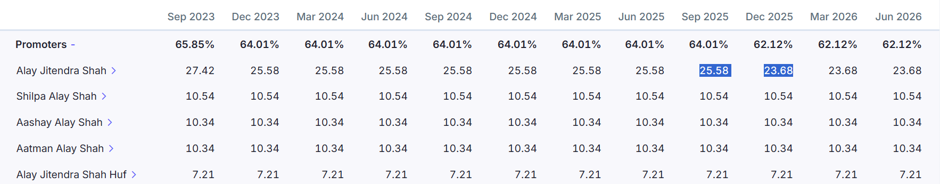
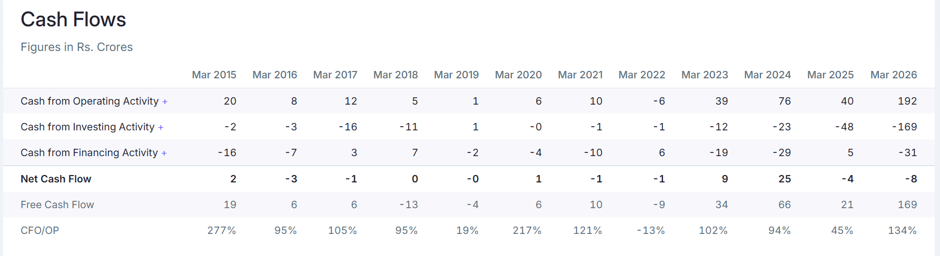
Between March of 2024 and 2025, Cash flow to operating profit dropped from 94% to 45%. So its clear, less of the profit was translating into cash flows. During that period, company’s sales grew 59%, they issues bonus shares and got listed on NSE. Also, this was the period Promoter sold 1.9% of his stake. Since then, revenue growth has slowed down but CFO/OP has recovered. Granted that company also expanded capacity, but I think it was a case of aggressive revenue recognition. DISC: INVESTED+PARTIALLY EXITED
2 Likes
If you don’t mind, can I ask what led you to exit partially? Is the export mix being down in last 2 quarters or some other cracks you could see in the business?
I had to put money elsewhere. I am aware of the competitive advantages that Shilchar has, and the sectoral tailwind. However some factors made me apprehensive;
- Balooning receivables (as highlighted above) 2. Valuation. At the time, they had operating cash flows of 40 cr & 76 cr and a market cap of close to 6000 crore. So from there, I did not see a massive upside. 3. Comparision with JSHP: This isnt exactly a perfect benchmark, but it was something I used while analysing a low cost producer. I thought scaling beyond a point would require a) entering into new categories b) significant capex, which might result in future dilution (At the time I was analysing solar stocks as well and sold them foir the same reason. 3)Glassdor reviews: Promoter/ Ownership has too much involvement in day to day operations. Tbf, they have got them till here, but to move forward from here, I think you need an independent CEO with a corporate work culture.
1 Like
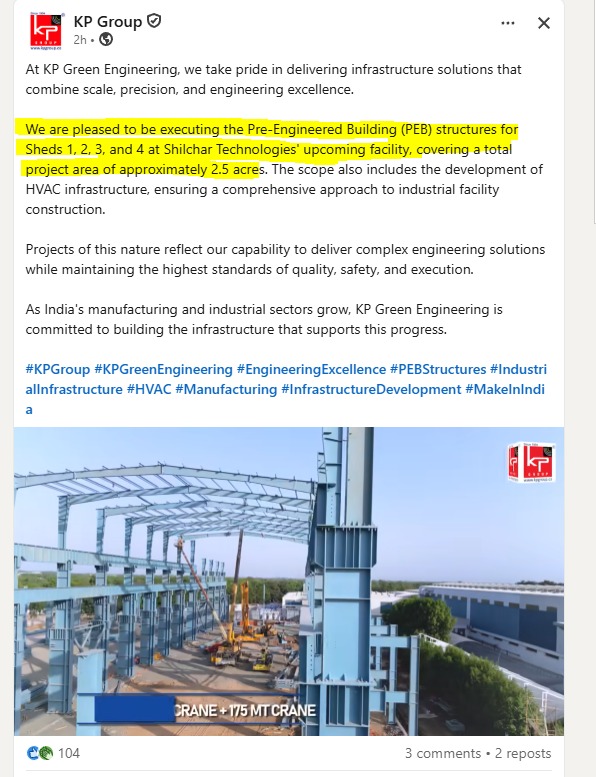
Zerodha broking buys Shilchar, do they know something?
2 Likes