Could anyone who has been tracking this company share the current capacity, on going capax, and how much capex incurred in previous 2-3 years (with line to capacity increase)?
This will be really helpful.
Could anyone who has been tracking this company share the current capacity, on going capax, and how much capex incurred in previous 2-3 years (with line to capacity increase)?
This will be really helpful.
Only look for Total as the previous CAPEX has been realized, and capacity is on the stream already… There have been some small acquisitions in Germany (Not sure about capacity) and the Acquisition of Ravi Technoforge (Not sure about capacity). Other than these, major capacities are already mentioned.
Company reported solid numbers. 40% sales growth with humongous PAT
But there is one pain point
Company’s debt stands at 237 croree and board has approved another 500cr fund raise via NCDs. Possibly, NCD proceeds will be used to refinance the debt. Current interest rate > 12%.
Company announced 12rupees per share as dividend.Thats about 80crores as dividends expense. With 60% of company resting with promoters, 48 crores is going back to promoters as dividends. Why not use this money to repay the debt and lower the borrowing envelope. As per FY 22 annual report, promoter family already took remuneration of 35cr all members put together.
Is this not value destructive for minority share holders? Views are invited. My analysis may be wrong.
Future growth in the oil & gas and power sectors could positively impact earnings and EPS, but the extent will depend on sector developments and the company’s strategic positioning within these industries
Ratnamani Metals & Tubes Ltd.’s success in a competitive market is attributed to its comprehensive product range, high-quality standards, advanced manufacturing capabilities, and strong customer relationships. By leveraging these strengths, Ratnamani effectively positions itself as a leading player in the stainless steel and carbon steel manufacturing sector.
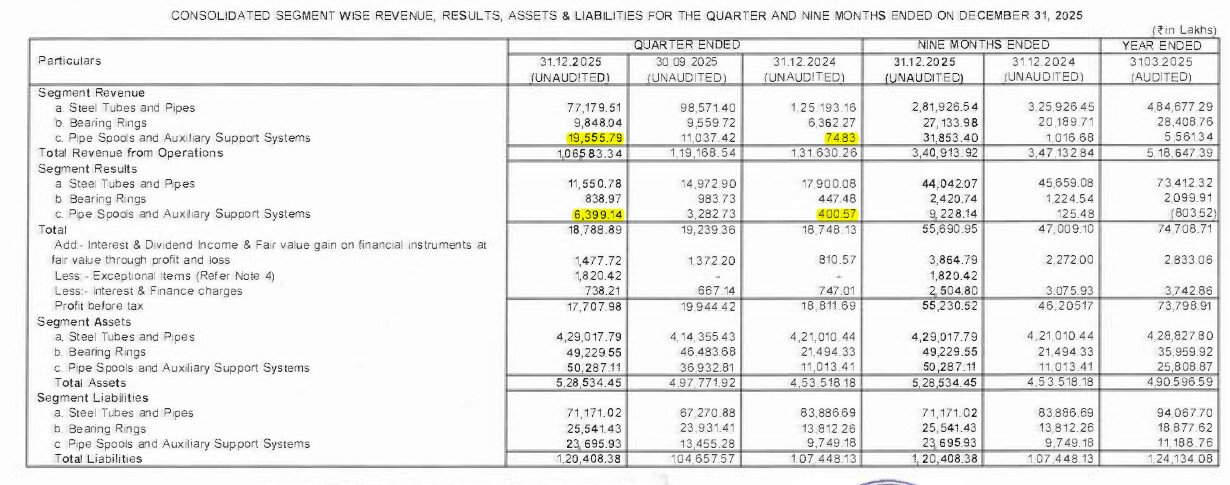
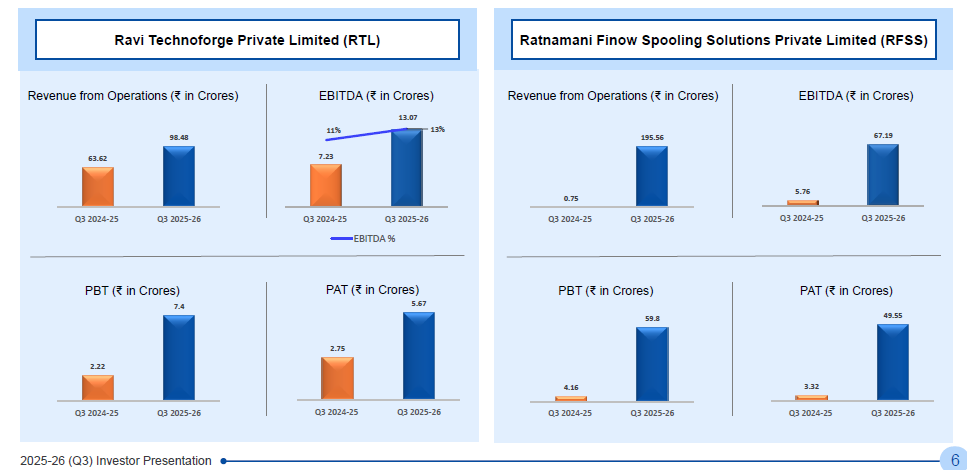
Ratnamani Metal result for Q3FY2026 indicates growth slow-down in main business of Steel tube and pipes, subsidiary turnarounds were excellent. Enclosed are consolidated segmentwise financial and presentation slide showing recent acqusition performance. The turnaround Pipe/spool and Auxiliary support system sgement is very good. During FY25, this segment report revenue of Rs 55.6 Cr and PBIT -8.03 Cr (Loss). In 9M FY2026, revenue improved to Rs 318 Cr (with Q3FY26 revenue at Rs 195 Cr) and PBIT profit of Rs 92.2 Cr (with Q3FY26 PBIT of Rs 64 Cr). If such turnaround continues, the company may moved in another horizon for future growth.
Fully agree with you Dhiraj, in fact words used by you in last line here , are exact words used by Prakashbhai Sanghvi in Annual Report 2024 taking about this subsidiaries, he used the word ‘next orbit’ instead of horizon…. more upwardly bullish 
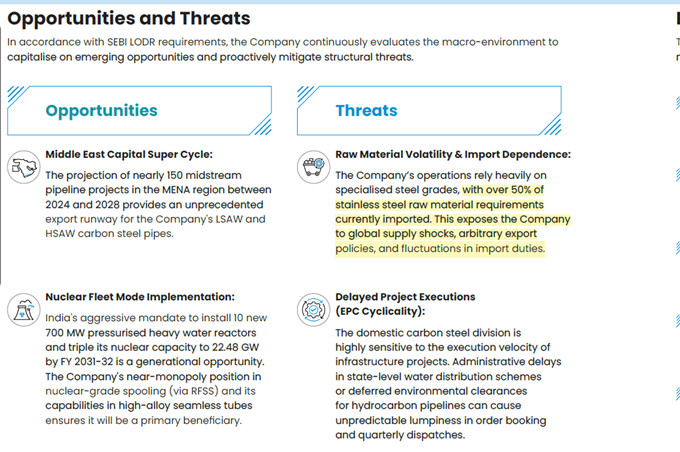
Now the steel tubes and pipes business will also have a positive impact due to Middle East projects. Already announced by UAE. You build up more and more oil gas infra in Middle East and India and Ratnamani main business also will perform along with subsidiaries.
Clearly demand is expect to move up given the broader rebuild phase expected to begin in Middle East + refineries damaged in & around Russia/Ukraine border, also pipeline connections may become a strategic part of inter country diplomatic relations. Importance of the sector may induce strong backward integrated (mine ownership) Jindal to venture downstream especially how higher RoCE clearly suggests enough space for more entrants those not vulnerable to geopolitical twists, just trying to look at this from a different perspective.