Good follow-up analysis of Northern Arc after the latest results.
See his point on risk-based pricing.
Good follow-up analysis of Northern Arc after the latest results.
See his point on risk-based pricing.
Interesting reading in the context of Northern Arc.
Today’s Business Standard, Page 17: Wanted: A new model for microfinance as MFIs explore secured products
Interesting development from RBI’s end
Great detailed blog on NAC
well if that is the case, stock could have reacted but price action is not encorging at all
I will enter once they start reducing their provisions, in Q3 again credit cost started to jump as compared with Q2. Q3 credit costs include the ECL on digital biz, but lets see how they will end Q4.
Their NPA numbers are always misleading since listing, NPA numbers are always on lowerside and credit cost is used to be on higher side.
Northern Arc consistency continues in Q1 FY 27. (disc: invested )
In line with most similar companies, particularly the microfinance bunch, stock has corrected post results. How to interpret this price action on the back of good results is something investors need to do on their own.
Presentation for q1 fy 27, concall transcript for q1 fy 27 attached.
I feel this is a slightly differentiated business model as compared to other run of the mill NBFC in similar space. Even during past 5 years where a lot of other companies suffered massive write offs and defaults, Northern arc remained a model of consistency. If and when markets recognise this company for what (I feel) it is, one can see good returns. For that we need the markets to agree with us. 
For some one wanting to understand the company better, Digant Haria of Greenedge wealth has put up the details on his blog post.
northern arc q1 fy 27 presentation.pdf (7.4 MB)
Northern Arc q1 fy 27 concall transcript.pdf (270.3 KB)
I think everyone here agrees northern arc is a good company. why doesn’t market reward it like one then? I refuse to believe business is complicated enough for market to understand it narrative. Is it because they don’t have promoters? Would like to know your thoughts on this @hitesh2710
Disc: invested and biased
Northern arc business mix is changing. Now they are lending directly from their books more which obviously have higher NIM. Market always give higher valuation to those who lend on its own books rather than generating AUM and then selling to some other finance institutions where NIM are obviously less.
Disclaimer: Holding and biased.
The cos. has 2 business segements- D2C leding and providing lending solution to other Financial Institutions.
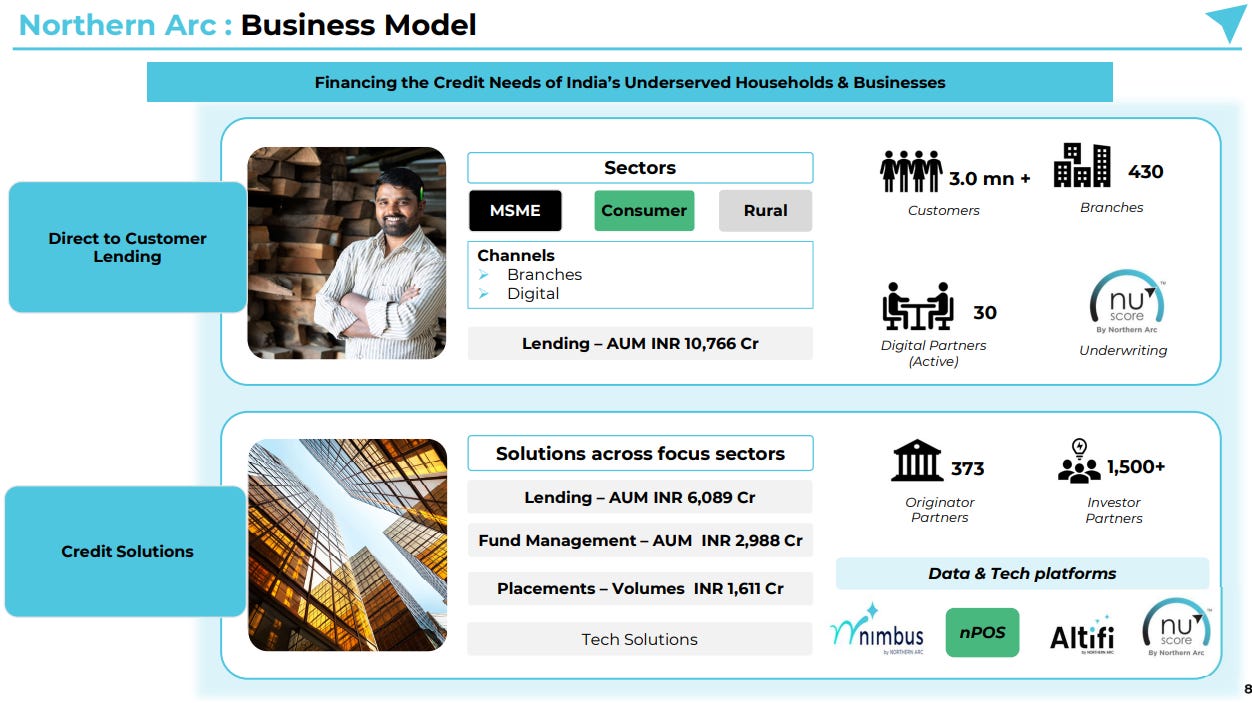
Lending AUM is up 26% and D2C customer is up more than 50% YoY at 64% of total AUM which is of higher margin.
Gross txn volume is down 5% YoY in Credit solution business.
The focus of the co. is moving from Credit solution to D2C lending which is a good sign given they keep asset quality in check.
94% of the MFI book is CGFMU covered.
“AltiFi”- their retail platform crossed 1 lakh subscribers. (Retail bonds platform)
Currently at 430 branch network, and we will add another 50 to 60 branches this year.
Targeting 3% ROA this year, 2.6-2.7% credit cost, NIM guidance intact (10%), current- 9.4%.
We’ve added about 250 people between the LAP and the MFI to push towards greater Northern Arc Capital Limited July 27, 2026 Page 10 of 14 productivity and to push toward expansion in it. So, I think all that puts us in a pretty strong position to continue to build on this momentum we have……………..We’ve added about 250 people between the LAP and the MFI to push towards greater Northern Arc Capital Limited July 27, 2026 Page 10 of 14 productivity and to push toward expansion in it. So, I think all that puts us in a pretty strong position to continue to build on this momentum we have.
No dilution for next 2 years, Current debt/equity is at 3.1x and have head room to gro till 4-4.5x.
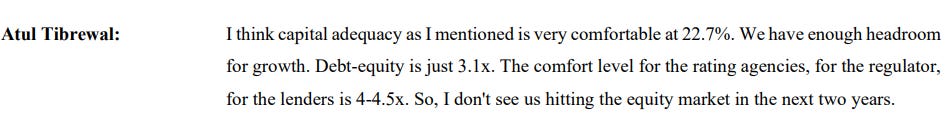
Targeting for 22-23% growth over next 2 years.
In latest concall, an analyst asked for the reason for increase in stage 3 provisioning and management replied that "The majority came from reclassification of an old purchased exposure received in settlement of a trade transaction.
I am failing to understand:
Can anybody have view on this? Disclosure: Invested and holding and biased and trying to learn more.