Mahindra & Mahindra Ltd. - a federation!

The UK FTA trade agreement once signed will make luxury car import duty reduced in India.
Is this risk already baked in the price for M&M? Maruti ideally should not be affected much given that they are still majorly a people’s car producer. Tata Motors may infact benefit since they can import their JLRs.

But the reduction of import duty is expected to be gradual over 5-10 years plus there are some quota talks aswell… India's carmakers back zero duty on limited British imports under trade deal: sources - The Economic Times

There is a huge gap between M&M and JLR prices. Reduced duty won’t impact this gap considerably. Different market segments altogether.

Though i dont know which models might compete with our Indian car maker models but I believe there will be some market share loss. Else the association would not seek terms like a) gradual duty reduction b) quota system for the import numbers…

But I think maybe its already built in the price, why else would it trade at 12 EV/EBIDTA while Maruti trades at 18! Even though Last 5 yrs M&M Revenue has been above Maruti and avg 5 yr OPMs have been almost 70% more…

M&M Q4 Results: Profit spikes 32% YoY to Rs 2,038 crore, revenue jumps 11%

1 Like

Anyone tracking M&M?

Good times ahead, with:

  1. robust sales performance especially XUV700 where sales jumped 40% in July following price cut.
  2. good operational performance in Q1 and most brokers upgraded targets and EPS expectation,
  3. Thar much anticipated 5-door launch on 15th Aug,
  4. tractor performance will get a boost due to budget allocation.

While the stock has rallied along with other Auto companies, I expect outperformance in near-term, primarily driven by upbeat SUV performance and company gaining market share across segments.

1 Like

M &M -All round growth seen in October Sales. Total Sales up by 20%, SUV grows by 25% , Tractor growth by 30%.

3 Likes

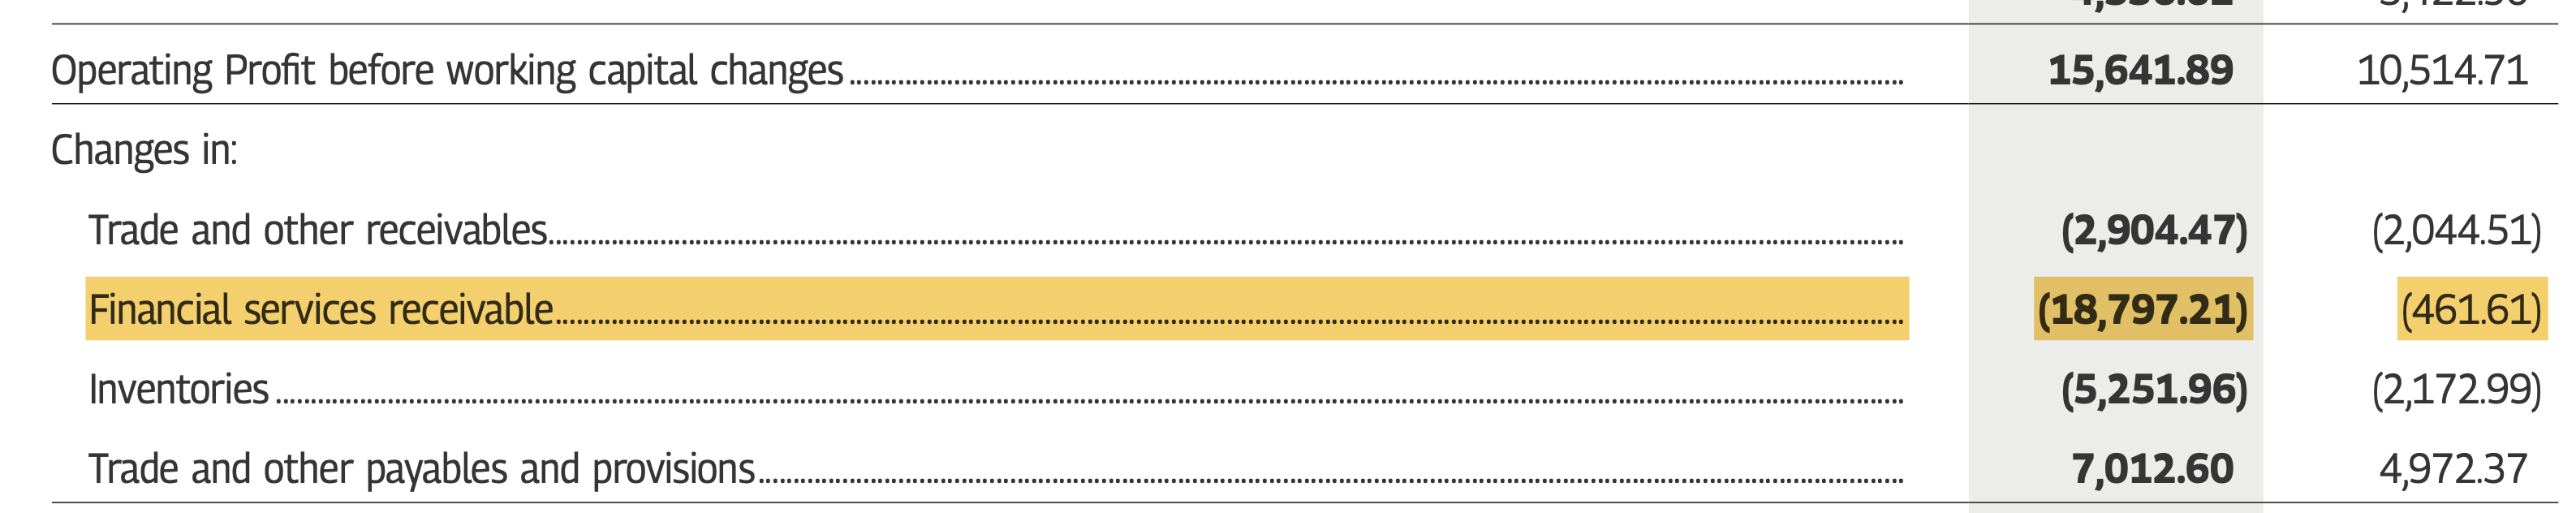
Pardon if this is some accounting nuance I am not aware of, but
Can someone explain, what is the reason behind sudden rise of receivables since FY23 onwards?
I do not see such anomaly in the receivables in the balance sheet

I also dont see them in the annual report though :

https://www.bseindia.com/xml-data/corpfiling/AttachHis/09ee6a86-fe09-444c-baf3-b7e68b0775ee.pdf

So, probably something wrong with screener.

Sharing this just to highlight the increased competitive intensity that one can expect in the PV 4W category in India going forward , which could impact volumes and margins for all players.

1 Like

BYD in India would be bad news for M&M. However, according to this video, they have been denied permission to setup plant in India. So, I guess, till the permission isn’t coming, we need not worry.

BYD is importing cars in India though. And import duty has been reduced to just 15%. That means major selling price impact?

2 Likes

so the import duty reduction is for premium EV cars i.e above 30.5lacs that too for 8000 units only. So the only M&M model which falls in this category would be XEV 9e but this is the model which saw 56% of the total bookings on the first day so the arrival of tsla can hurt but don’t think it would be that much especially in the initial couple of years on the other hand this could encourage the Indian brands for improving more and coming up with a more spectacular models.

1 Like
3 Likes

PPFAS on M&M

2 Likes

Hi Pranshu,

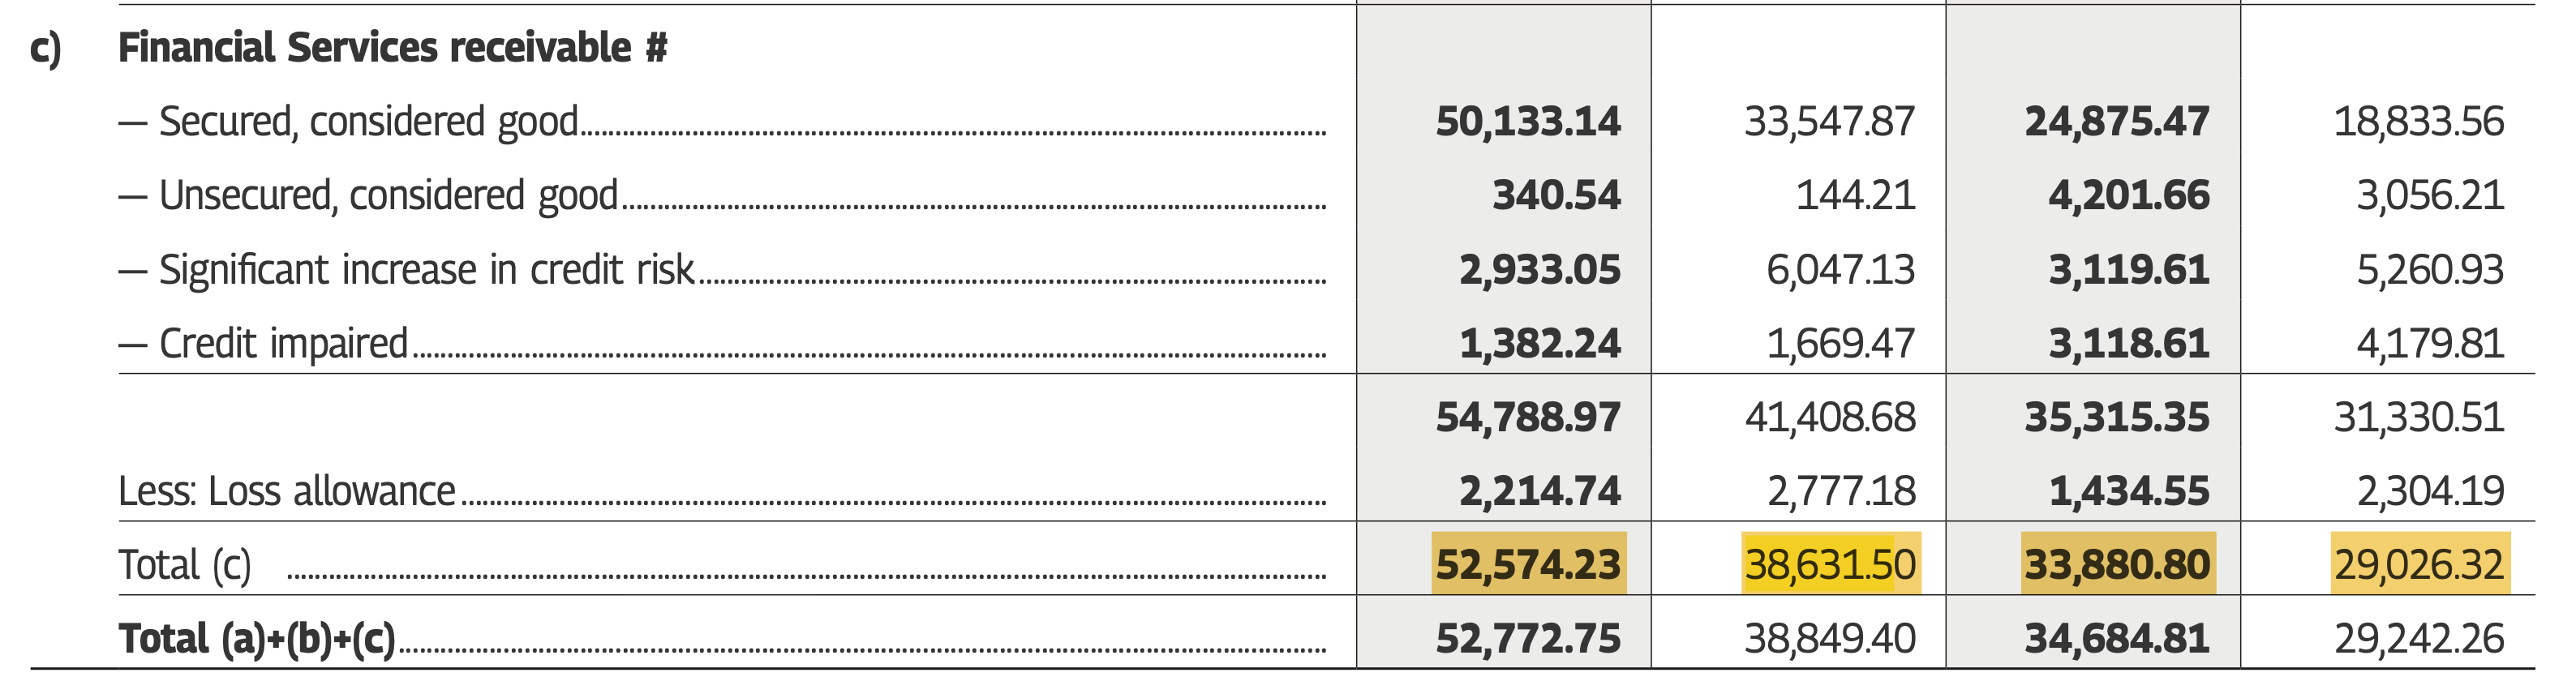
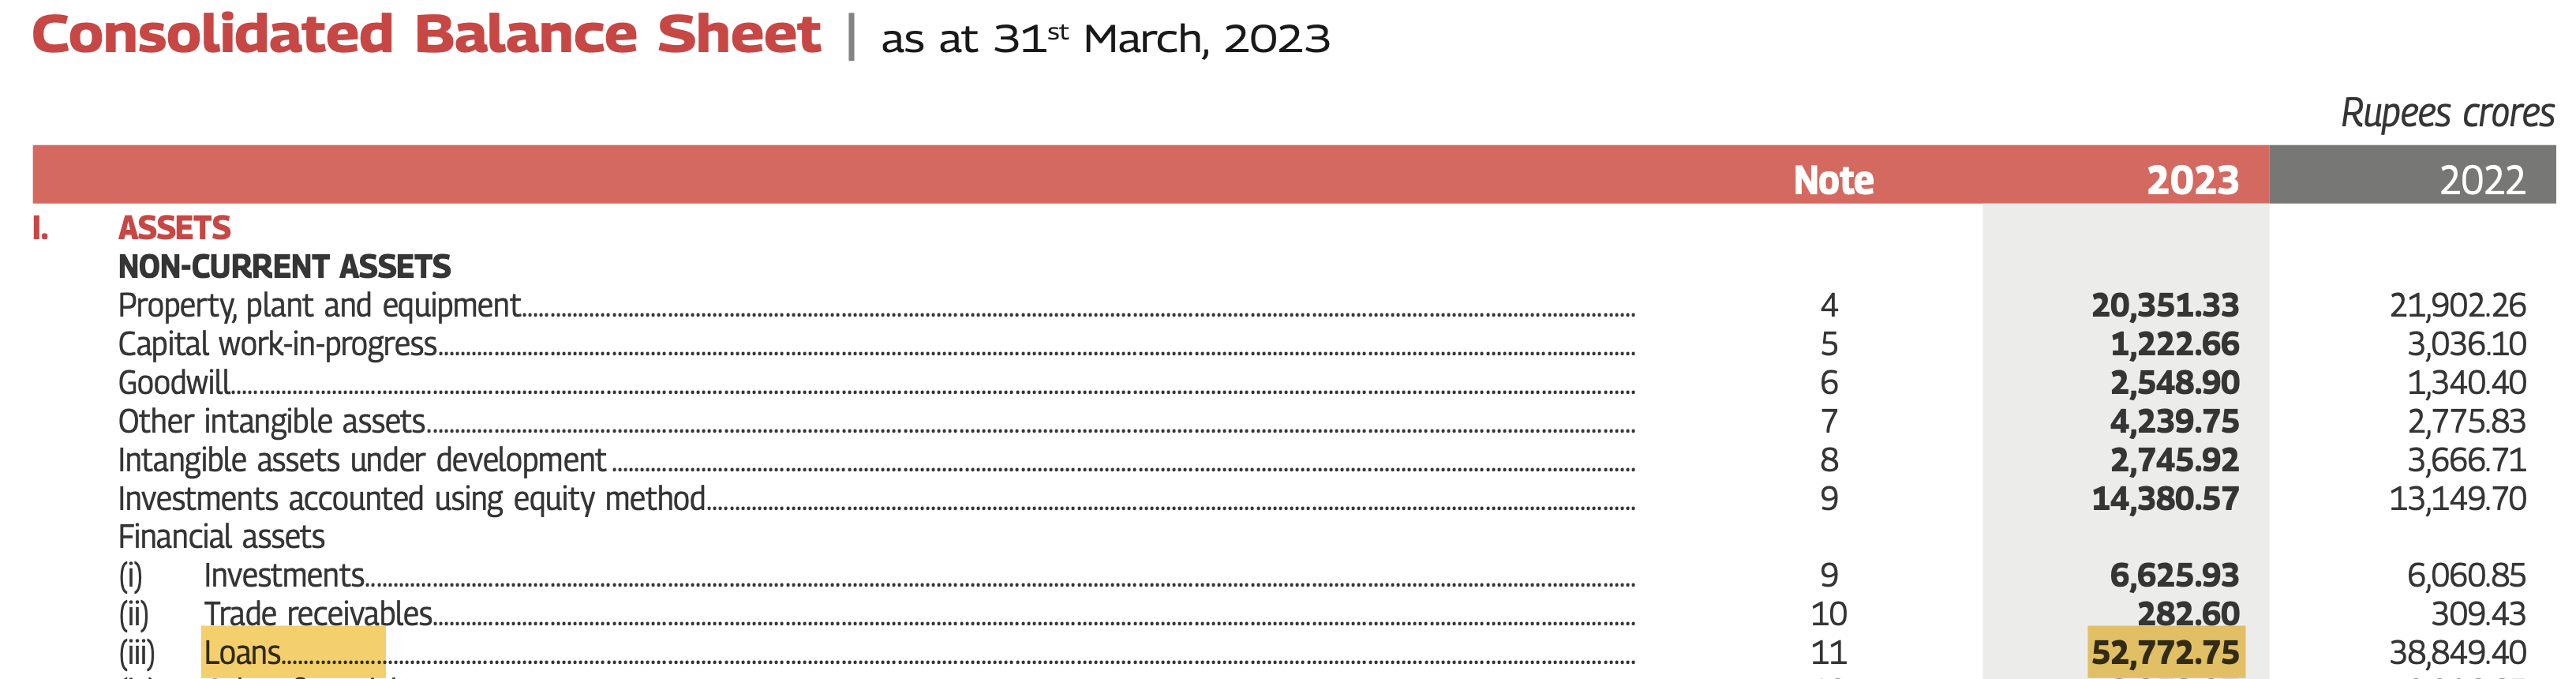
I dug deeper into this. Actually, the receivables went up so much primarily because of loans given by Mahindra Financial Services Limited (MMFSL). This is a subsidiary of Mahindra and Mahindra which does lending.

I looked at the cash flow from operations in the annual report for FY23. If you go to page 373 you will see that Financial services receivables went up by 18,797.21 crores. This means this much amount of money went out of the company.

If you then go to page 394, you will be able to see that the loans given by the financial services vertical have increased by the same amount (18,797.21 crores) in FY23.

Also, if you look at the Asset side of the balance sheet (Page 368) you will notice an asset called ‘Loans’. That is where these loans given out reside. These loans are an asset for the company as the company will earn interest from these loans. Hope this clarifies.

2 Likes

There has been some very smart moves by Mahindra which are small for overall company so have mainly got unnoticed.

  1. SML Isuzu acquisition at a huge discount
    M&M shares jump over 1% after CCI clears 59% stake acquisition in SML Isuzu; open offer to follow - The Economic Times

  2. Aero structure win
    Mahindra Aerostructures, Aernnova announce $300 mn multi-year contract - The Economic Times

  3. Focus on solar
    Ontario Teachers’-backed Mahindra Susten to flip more green energy assets into InvIT

3 Likes

Mahindra & Mahindra - All in one Auto company is the biggest beneficiary of GST 2.0

Good overview of the group

1 Like

Interesting. Aerospace set to become a growth driver. Airbus requesting them to supply more components

https://www.moneycontrol.com/news/business/m-m-eyes-global-aerospace-acquisitions-as-aircraft-makers-seek-supply-chain-stability-13938440.html

1 Like

Mahindra and Mahindra -

Company’s stakes in various group companies -

Mahindra Electric Automobile Ltd ( MEAL ) - 4W BEVs - 92 pc

Mahindra and Mahindra Fin services - 52 pc

Mahindra Lifescpace developers - 52 pc

Mahindra Logistics - 59 pc

Mahindra Holidays - 67 pc

SML Mahindra ( sell CVs > 3.5 T ) - 59 pc

Mahindra last mile mobility ( sell 3Ws and small BEV CVs ) - 78 pc

Swaraj Engines ( diesel engines ) - 52 pc

Classic legends ( Yezdi, Jawa, BSA ) - 58 pc

Mahindra EPC irrigation - 54 pc

Mahindra first choice wheels - 56 pc

Mahindra Aerospace and Defence - 100 pc

Tech Mahindra - 28 pc

Mahindra Manulife ( AMC + Life insurance ) - 51 pc

Q1 FY 27 results and concall highlights -

Revenues - 58.2 k vs 45.2 k cr, up 28 pc

EBITDA - 10.8 k vs 8.4 k cr, up 28 pc ( margins @ 19 vs 18 pc )

PAT - 5.4 k vs 4.08 k, up 35 pc ( bumped up by company’s stake sale in CIE Auto. Ex - stake sales, PAT would ve grown by 22 pc )

PAT contribution towards consol numbers from various businesses -

Auto - 2.12 k cr, up 21 pc ( includes PAT numbers of SML Mahindra and Mahindra Trucks and buses ltd )

Farm - 1.52 k cr, up 15 pc

M&M Fin Services - 486 cr, up 78 pc

Tech Mahindra - 411 cr, up 28 pc

Real Estate - 41 cr, up 2X

Logistics - 14 cr ( vs negative 7 cr in Q1 LY )

Investments - 772 cr, up 115 pc ( due gains realised on sale of M&M stakes in CIE automotives )

Imp commentary -

Board has approved merger of MTBD into SML in early Q2

SUV volumes grew 15 pc

Domestic farm equipment values grew by 18 pc, Export volumes of farm equipment grew by 15 pc. Company continues its mkt leadership in farm equipment segment with mkt share @ 45 pc

SML+MTBD - combined mkt share now @ 7.8 pc. Combined volumes grew by 11 pc

Notes from Q1 concall -

Reported strong results despite severe RM price inflation ( @ around 400-500 bps for key RMs )

M&M Finance’s asset quality and disbursement trends continue to remain strong. Gross Stage 3 assets have been below 4 pc of AUM for past 8 Qtrs in a row. Closed Q1 FY 27 @ 3.45 pc ( talking of GS 3 )

Labour shortage in farm / rural areas are structural drivers for growth in tractors and other farm equipment. Rabi cash flows have been healthy. This is keeping rural cashflows @ healthy levels. Rainfall shortages in June are now behind ( as the catch up in July/Aug has been encouraging ). Kharif sowing has picked up meaningfully over last 1 month

Domestic Farm ( core tractor ) business clocked 19 pc EBITDA margins with sales @ 9964 cr. EBITDA margins in international farm business were negative with sales @ 1735 cr ( also due impairment charged to P&L ). Other farm business like Farm machinery + Powerol + Swaraj Engines clocked 10.7 pc kind of EBITDA margins with sales @ 10.7 pc. Consol company level EBITDA margins in the overall farm business were @ 14.2 pc

Auto PV volumes sold in Q1 @ 1.75 lakh, up 15 pc YoY

LCV< 3.5 T volumes sold @ 74k, up 20 pc YoY

Consol EBIT margins of Auto business ( SUVs + LCVs<3.5T, EVs + Trucks and Buses and Last mobile connectivity solutions ) @ 7.7 vs 7.9 pc YoY

Auto Segmental Revenues and EBIT -

SUVs +LCVs < 3.5Ts - 25.16k cr, EBIT @ 8.9 vs 10.8 pc

EV SUVs - 5.4k cr, EBIT @ 5.3 vs (-) 3.3 pc

Trucks and Buses + Last mile connectivity - 4.19k cr, EBIT @ 2.3 vs (-) 2.9 pc

EVs ( 3W + 4W ) -last mile connectivity volumes - 35.5k vs 19.2k YoY

ICE ( 3W + 4W ) last mile connectivity volumes - 6.7k vs 5.8k YoY

SML volumes - 5.4k vs 4.3k YoY

MTB volumes - 3.9k vs 3.4k YoY

Tractor volumes - 1.58 lakh, up 18 pc YoY ( domestic mkt share @ 45 pc )

Non Auto business of M&M finance ( mortgages, PLs, SME loans ) grew by 79 pc YoY in Q1. Auto loans ( PVs + Tractors + CVs ) grew by 21 pc

12 pc of all PVs sold by the company were electric. Company’s EV business is EBITDA positive even without PLI benefits

As company’s volumes improve, their EV profitability should only improve. Plus - as the consumers start to realise that they r gonna save significant amount of money by using an EV vs a petrol car and this mentality gains momentum, company can always start charging premium for Electric Vehicles

Mahindra lifespace ( RE subsidiary ) - intend to keep focusing on Mumbai, Bengaluru and Pune. Shall keep trying to improve their depth in these 3 cities instead of spreading themselves thinly over many cities

Took 1.5 pc price hike in Q1 followed by another 2.7 pc price hike in early Q2. This should support margins ( to some extent ) vs Q1

Despite the recent price hikes taken by the company - prices r still below vs LY ( before GST rate cuts )

M&M finance AUM now @ aprox 1.5 lakh cr. 83 pc of the AUM comes from Auto lending ( PVs + CVs + Tractors + Used Vehicles ). Aim to grow the non auto business to 30 pc of AUM by 2030

Company’s Aerostructure order book stands @ $ 1.2 billion and growing fast. Revenues right now aren’t comparable to their large order book because it takes time for order executions. Aspire to grow their aero structures business by > 30X over next 10 yrs ( organic + inorganic combined )

Commodity price pressures are more severe in Farm vs Auto business. Two reasons - there is no way to hedge the steel and rubber - both r used more extensively in farm business. In auto business - they do hedge their Aluminium requirements. Secondly - Aluminium prices have started correcting but not Steel and Rubber

Disc: holding, biased, not SEBI registered, posted only for educational purposes

2 Likes

Beyond HAL, they have best aerospace business pipeline after Tatas (which is in unlisted entity).

Beyond aero-structure biz, they want to be complete defence aircraft manufacturers.

https://www.ndtvprofit.com/business/rs-1-lakh-crore-60-aircraft-tata-mahindra-and-hal-in-the-race-all-you-need-to-know-11902696

2 Likes

Mahindra’s march in aerospace and defence gets a leg up

https://www.manufacturingtodayindia.com/embraer-selects-mahindra-for-60-aircraft-iaf-bid

3 Likes