
Till December 2025, the stock was below 1k marketcap. Institutional holding is rare in smaller cos. And where did you see the cash flows? Operating Cash Flows are immaculate.
Check on stock scans tijori yoy cash flow is weak if you still want to invest check management guidance and then make a plan accordingly to that
1 Like
Seven Canyon Advisors are expecting 30%+ CAGR in sales and 50% CAGR in profits. this is similar to the numbers i had projected. Curent price is 15X FY 2027 earnings and 7.5x FY 2029 earning.
As company already has capacity for 1,000 cr sales and adding plants in Hormones and Biologics, this could lead to a potential revenue of INR 1,500 Cr to INR 2,000 Cr.
Company will become a good size pharma company paving potential for larger revenues and profits.
2 Likes
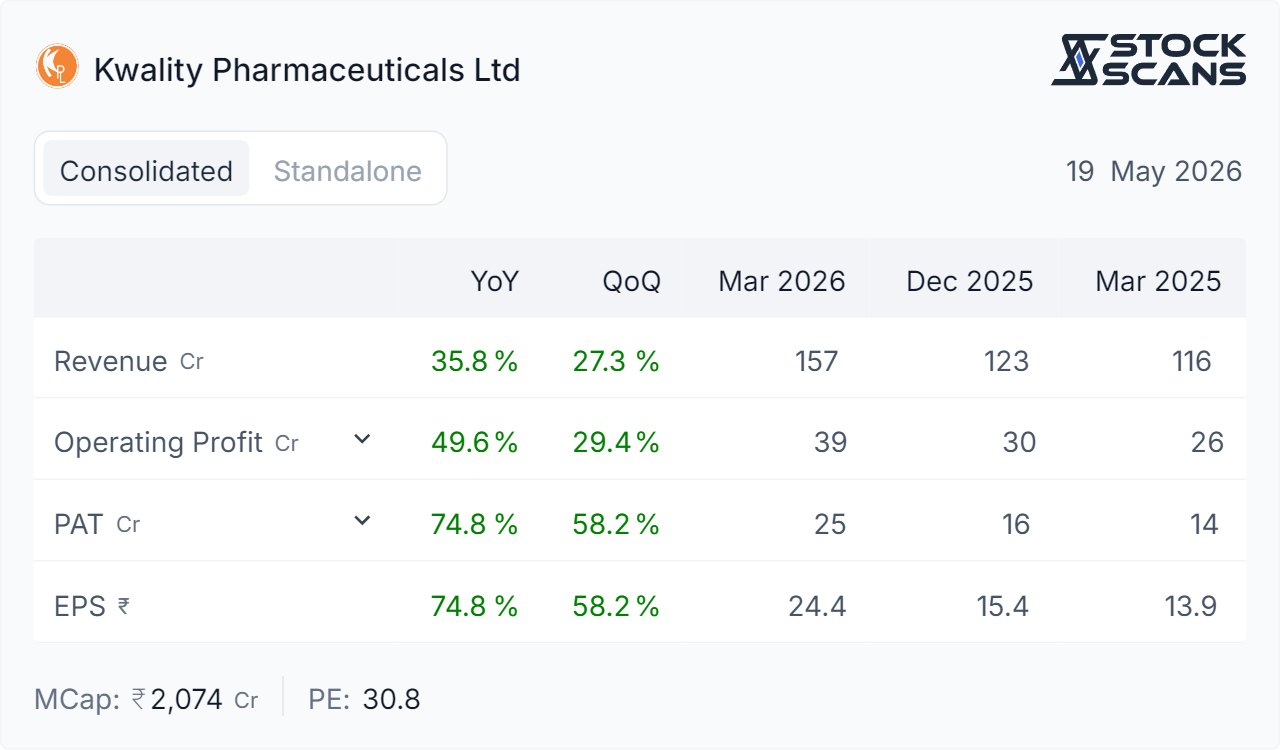
See we have to do deep research don’t look on don’t just look on yoy growth rate , PE ratio and other things there are negative things also like debtor days , inventory days , trade payables have increased , days payables have increased , cash conversion cycle has increased like anything so this all are trap , company is generating profit , til cfo is not getting converted, better do research for everything
2 Likes
In the latest concall management has clarified that 1,000 cr revenues is without the new plants. Including new plants revenue could go upto 1200 cr. Even at 1,000 cr and 30% EBITDA margin PAT will be 200cr. Taking a multiple of 25x mkt cap could be Rs 5,000 cr
Please note that this is not advice to buy/sell the stock. it is just for educational / discussion purpose.
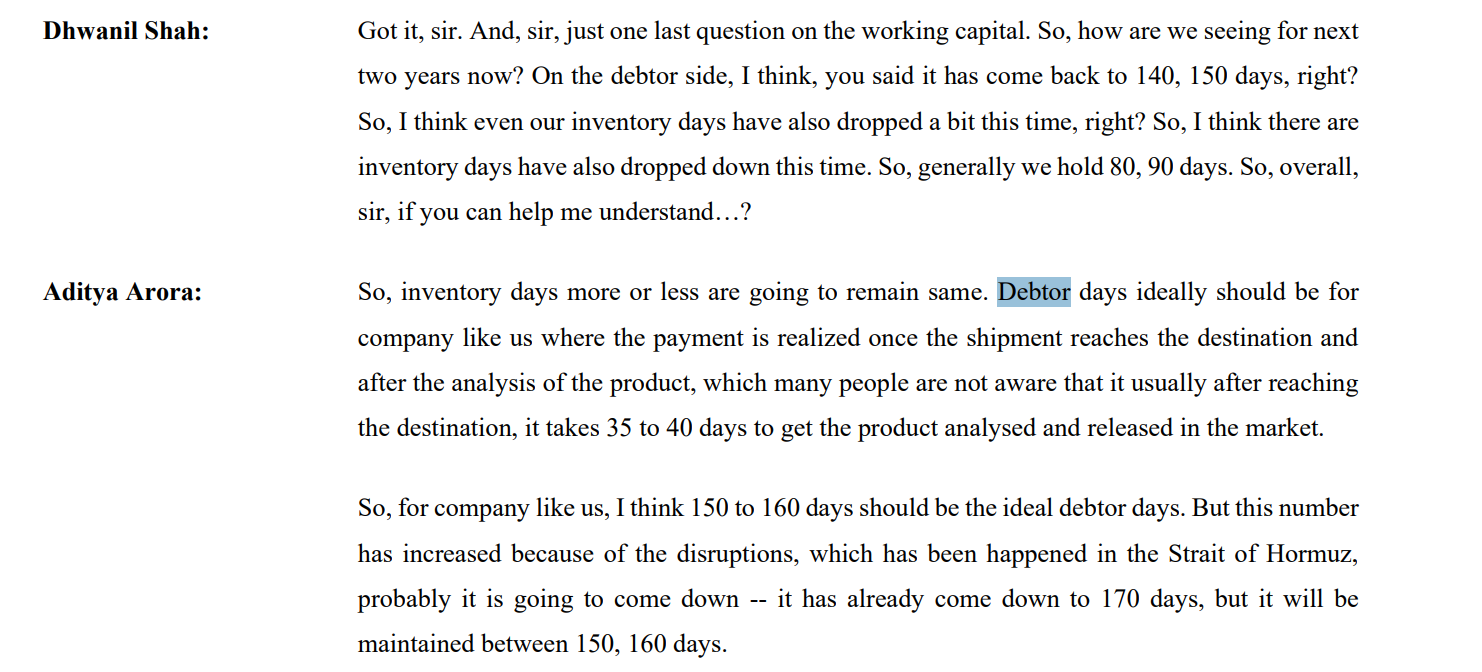
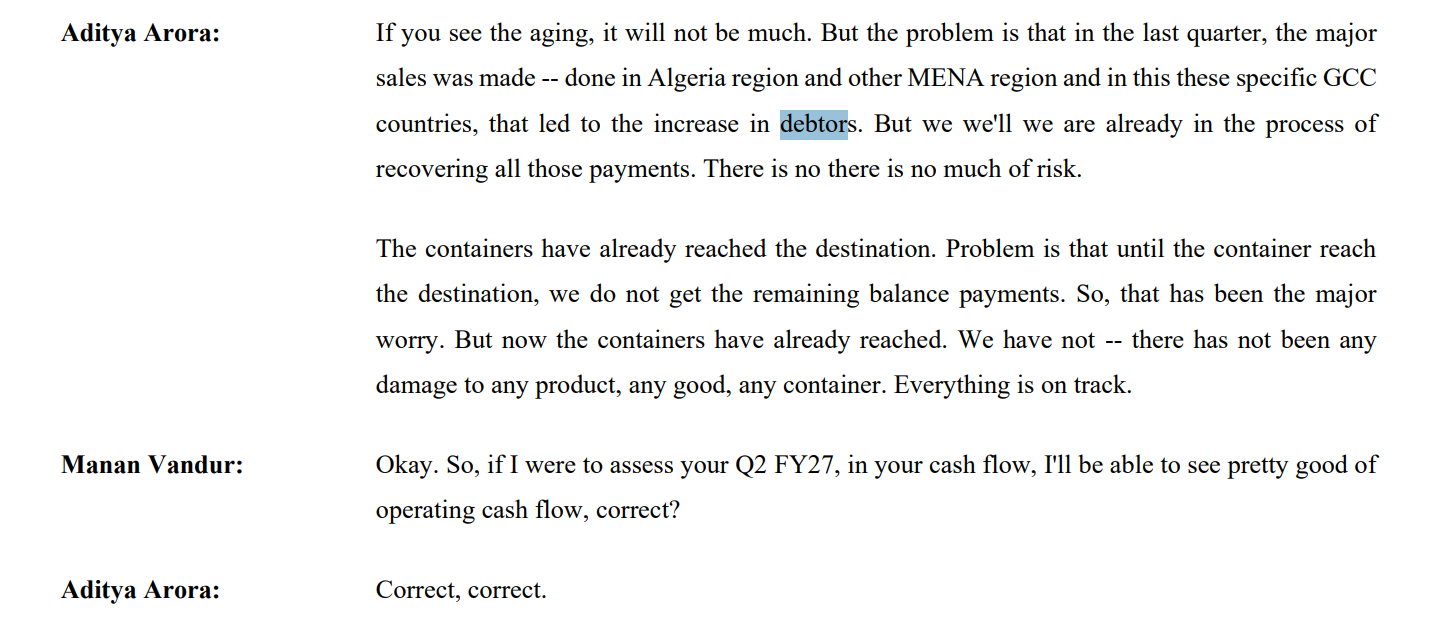
According to management in recent concall they have mentioned the payment structure for export. According to them the payment on export are done in two parts
First partial payment is done on advance. Second payment is done once the shipment reaches the intended port and after products quality test is done.
Therefore, the ideal debtor days should be between 150-160 days for current product portfolio.
Currently, due to US Iran war shipment to GCC and MENA countries got delayed. The second part of payment got delayed as well. Which will get reflected on Q2FY27 cashflow statement.
Disc - Invested and Biased.
2 Likes
Debtors increasing is only temporary due to Middle east issue.. cash conversion cycle is always high for formulations companies and that too into exports where transit time itself is high.
without cash company will not be able to invest in new plants from internal accruals. Further they have very low debt.
2 Likes
See they many problems we have to track down as of now , cash flow , inventory days etc everything is not going up to the mark , as of now fyis have freshly entered into this will track down more
1 Like
Yes correct will track down and then I will think for investing
1 Like
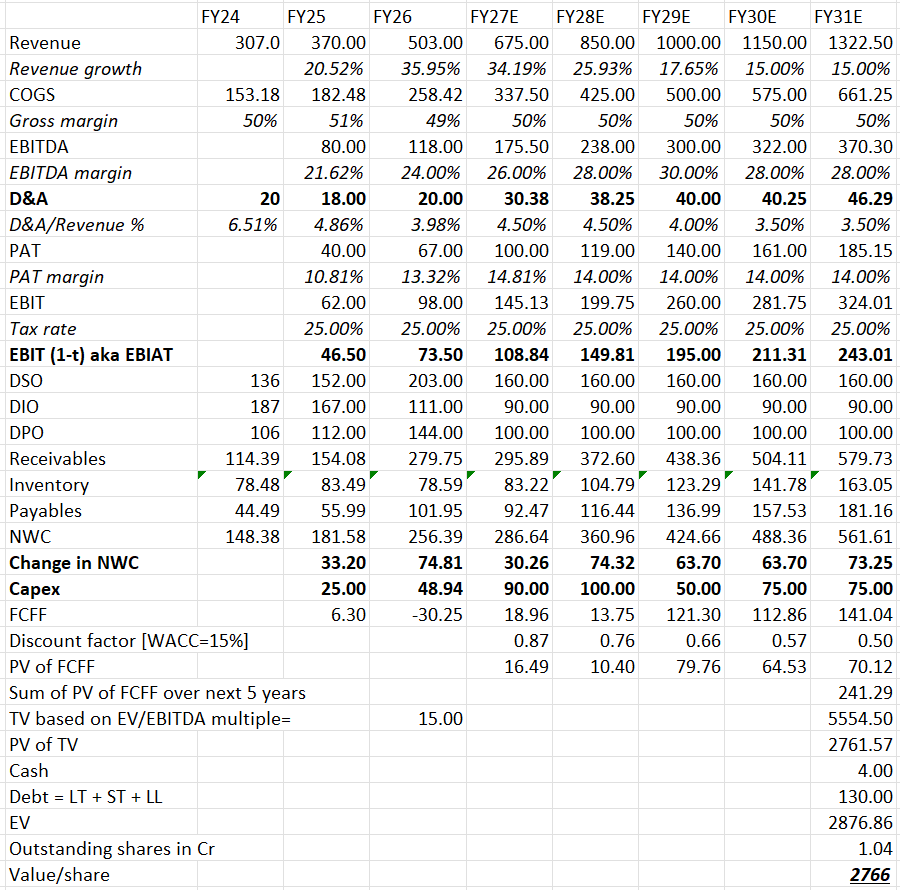
Kwality Pharma KPL has run up a lot recently, but its valuation still looks interesting especially in the context of strong guidance given by management for FY29.
Company is currently trading at a 12-month forward PE of 24x. DCF valuation with 15% WACC and 15x EV/EBITDA exit multiple suggests it is still undervalued. Thoughts?
Disclaimer: DYOR. This post is only for educational/discussion purposes and not a buy/sell recommendation.
3 Likes
Many people gave negative feedback on my posts on Kwality Pharma when it was at Rs 300.. Today it is at Rs 2,500… 8X…
I have been posting on this forum for benefit for all.. have written about many companies.. People who dont know how to analyse companies should not mock others..
14 Likes
On 24/07/2026, KPL announced- CDSCO has granted permission to proceed with pilot-scale manufacturing for the generation of preclinical batches of Pembroluzimab.
Pembrolizumab (brand name Keytruda) developed by Merck & Co. is the largest single oncology drug medicine in pharmaceutical history. Reaching annual global sales of ₹3,00,000 Crore ($32.7 Billion). Merck’s patents expire on late 2028. Volume will shot up after 2028 as generics enter at economic cost (Current price of this injection is more than 200000 ₹ per dose).
Can KPL develop and ready to launch in 2028?
How much market share can be capture by KPL?
1 Like
I am quite confident Kwality Pharma will be able develop Pembrolizumab before the patent expires in end 2028. While many companies are building capacity to capitalise on this opportunity, Kwality can be one of them. Also not many companies have got into Biologics - some companies have older plants which will have to be recertified. Kwality’s plant is new and will get latest certifications.
As per the guidance given, Kwality will be able to get about 400 cr sales in FY 29/FY30 - which is very small portion of the total mkt. assuming prices will come down by 80 to 85% after patent expires.
2 Likes
Can you please provide some more input on the source of your confidence in their ability to develop Pembrlizumab?
Also if they are able to develop it, why are the revenue expectations capped at 400 cr for FY30, which is about 4 years from now, is not adding up.
The stock has already rallied so much that I am wondering if it’s still good enough to be worth entering now?
1 Like
Kwality is already making generics of off-patent products. It will not be difficult to make one more. They have reached clinical trials for one molecule - Erythropoietin (in Biologics). Pembrlizumab will be the second molecule.
Revenue of 400cr is not a cap - in fact it is a conservative number for FY 29. Revenues will come only after few years as patent of Keytruda (Pembrlizumab) is expiring only in 2028 end. Erythropoietin revenues may start earlier but only after all approvals have been obtained which is a time taking process.
Kwality is a company which is continuously growing and is expected to reach 1,500cr revenues in FY 30 (from current rev of 500Cr). You can take your call to invest or no.
2 Likes
Thanks for the Clarification!
Will try to keep a close eye on new developments, as Pembrlizumab will be the key driver and decision maker for the company in the coming years.
As a vague estimate of at least 220-250Cr. Net Profit on 1,500Cr Revenue, will be a good price pusher, provided things go as planned. (Although I do expect them to improve the Margins overtime as well)
2 Likes
Does anyone have today’s AGM notes?
Questions asked by investors in AGM just reiterated the points in the investor concall:
- Sales target of 700cr+ for FY27 and 1000cr+ for FY 29. Guidance may be revised upwards based on performance.
- Hormone plant to be commissioned in Nov 2026. Sales to ROW through existing distributor channel. Will appoint new distributors subsequently - new distributors have already been identified
- First biologics (erythropoetin) to be commercialised by Dec 2027. Company mentioned that productivity of their erythropoetin is double that of Wockhardt.
- Second biologics (Keytruda generic) to be launched in Dec 2028 when patent expires. They has done sales tie-up for sales to hospitals in India.
- They will be doing third shift in General plant (Unit 1) to achieve 1,000 cr sales target. they have already done arrangements to increase capacity of unit 1 by 20%.
- Algeria JV to start by mid FY 2028
Company is confident of its growth plans and it seems they will revise guidance upwards in few quarters.
6 Likes