
You are correct. As per media reports, 3 slabs are being contemplated: 5%, 18% and 40% (sin goods)
2 Likes
In reality, this 40% tax will be passed on to customers.. making cigarettes a lot more expensive. Historically, whenever prices rise in this manner, it creates a price gap that fuels the illicit cigarette trade. This could undermine legitimate businesses and also result in a loss of tax revenue to the exchequer..
2 Likes
As anticipated, there would be few complex moving parts to the Proposed GST rates.
I can foresee a possibility that, with many complex moving parts above 3 slabs recommended, the gains of Tax reduction may be minimal. My personal opinion has always been that, the complexity of any Tax regime always creates loop holes and inefficiencies in the system resulting into sub-optimal benefits to the exchequer.
(I may be wrong in my analysis!!)
1 Like
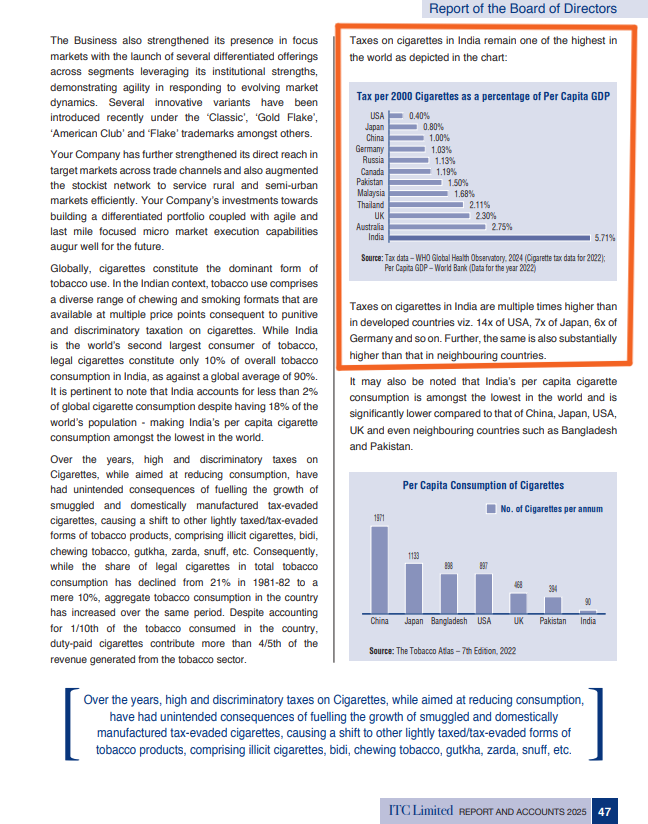
“Taxes on cigarettes in India remain one of the highest in the world as a percentage of per capita GDP “
“Historically, steep increases in taxation have adversely impacted tax collections and legal cigarette volumes, while a stable tax regime has led to buoyancy in tax collections”
Source - ITC FY25 Annual report
2 Likes
This is the reason Chinese illegal cigarettes are taking over a sizeable share of Indian markets resulting in a huge revenue loss for the country. The GST council should consider this before making any recommendation for further increase of taxes.
However the increase will be passed on to the consumer and don’t see any drastic hit to ITC except some short term volatility.
3 Likes
The PE premium that HUL and Nestle get is also because of the hugely profitable franchises they have created. ITC margins in the Non Cigarette FMCG biz are abysmal. No one doubts that they are an in-efficiently run business. Therefore the ITC PEs will always remain at a huge discount
4 Likes
True but I believe with backwards integration and creating new brands through organic and inorganic means can change the scenario in a decade or so. HUL and Nestle have already hit the ceiling and are already a mature business
2 Likes
This is where we need restraint the urge to over complicate the taxation regimes, but unfortunately the evidence speaks against it. Experts have built several complex layers in the current GST regime and General Taxation regimes, leaving gaps. Illegal cigarette business takes away the benefits of Increased Taxes where as if you keep only 2 tax rates, it could actually induce more willingness among population to pay taxes and buy legal products.
1 Like
During times of GST uncertainty & pessimism, there is a good news in one of the major business segment i.e. ITC Paper Division (ITC-PSPD). Minimum import price declared - which has put entire paper sector on huge demand atleast for the day.
DGFT Notfication-MIP-VPB-22.08.2025-RP.pdf (750.7 KB)
4 Likes
Note from ICICI Direct Research Desk:
- The Lok Sabha passed the “Central Excise (Amendment) Bill” and “Heath Security se National Security Bill” in the Lok Sabha on 3rd December 2025.
- The Central Excise Bill will add new central excise duty on cigarettes, cigars and hookah, while the Heath Security se National Security Bill will replace the existing compensation cess levied on pan masala.
- The excise duty on cigarettes and cigars will be in the range of Rs 5,000-11,000 per 1000 sticks.
The Finance Minister clarified that there won’t be any increase in overall tax rate on cigarettes. It will remain at 50-55%. This removes the uncertainties over the taxes on cigarettes. We expect trade channels to start refilling stock as uncertainties have been addressed.
12 Likes
What are the views of the members on this huge tax?
3 Likes
As per News yesterday, excise duty on cigarettes and cigars is in the range of Rs 2,050-8,500 per 1000 sticks depending on its size.
Many analysts were mentioning in their ITC Estimates earlier that, Now since there is stable tax regime on cigarettes, the future is more predictable while arriving at target prices. Some of those reports were making me uncomfortable as I was not sure about the stable tax regime.
GOI has stated excise duty in the range of 2050-8500, hence as per financial express news, now Total Tax on cigarettes will be close to 75% which is maximum limit suggested by WHO. Hence this tax hike might have major impact on legal cigarette market.
“An investor has to be vary cautious while estimating target price for any Cigarette stock” and it has been proven correct again.
Since the contribution of cigarettes in Net Profit is quite high (about 75%) there will be impact on its EPS at least in mid term.
Dividend Yield > 5% could be the area where ITC stock price might stabilize as it has happened in the past during 2020-21-22.
There is a possibility that, ITC management will start looking at Non-Cigarette business more aggressively now to offset the slow growth in Cigarette business. Agri and Paper business could be the area from where some positive factors can emerge.
As per some reports - “Its paper boards, paper, and packaging business continues to focus on accelerating plantations in core areas, developing new areas, collaborating with other wood-based industries, and implementing satellite-based plantation monitoring systems, among others for portfolio augmentation and cost management”.
Note : I have edited the post as Total Tax on cigarettes due to this excise duty could be much higher than I calculated earlier.
14 Likes
Wanted to post this earlier but regarding ITC’s non-cig biz, it feels like there is so much left on the table.
They are the leader in atta no doubt. Also their protein enriched atta is a good move.
Sunfeast- dark fantasy taste wise has no competiton for me personally but not available in all qcom platforms. Marie and bounce are also good. Moms magic beats good day but don’t understand why it sells less( perhaps because although I do see the big packets of moms magic along with good day, small shops mostly only keep the smaller packets of gd)
In Yippe, Maggi just seems untouchable. Also, Yippe’s pasta packaging doesn’t look good.
Bingo looks like it has a distribution problem. Never at the front in any store. Taste wise pretty good.
Fiama looks to be gaining market share.
Mangaldeep is slightly higher priced than cycle which in a basic product isn’t going to do it any favour.
Disc- Invested. Some views borrowed from my mom
11 Likes
In my view, this is a good buying opportunity. The smokers will continue to smoke and the excise tax will be passed on to the end consumers. The tax on tobacco is still low compared to other developed countries. However the government should crack down on Chinese smuggled cheaper alternatives if they don’t want to lose tax revenue
6 Likes
When the government spends significantly more on treating tobacco related illnesses than it earns from the sale of the products, does the industry shift from a revenue generator to a national debt?
With Ayushman Bharat now providing a health safety net for over 80 Crore citizens, the state is arguably assuming a liability that far outstrips the sin tax revenue it collects.
By moving toward a specific excise regime and 40% GST, the Center seems to be prioritizing healthcare solvency over industry stability.
Government policy stance is getting more common man friendly by the day (RMG ban, GST cuts, Income tax cuts and now this).
12 Likes
Wondering if there is any study, which an investor can refer, which proves by raising taxes consumption of Tobacco products can be reduced in medium to long terms.
1 Like
Even if available, No such studies can be reliable, since organised maret is not 100 % in India. Contrary to that, there are enough studies & data from across the globe, where raising tax on SIN goods like cigarettes, tobacco, etc only fuels the illicit imports & illegal trades.
Same risk is looming in India with this step.
6 Likes
There are several studies.
https://grok.com/share/bGVnYWN5_c3ab773a-b229-45e4-961a-9be858bc92a8
4 Likes
I think it’s more like 80 percent
2 Likes
Yes, it is almost close to 75% to 80% which is quite high, hence it is prudent to consider it more as Cigarette stock with FMCG, Paper and Agri as add-ons. Going forward, this ratio may go down since Cigarette Margins will be under pressure and FMCG, Paper, Agri may deliver higher Net Profit percentages in overall Net Profits.
4 Likes