
IMO its actually not the quarterly results but rather the impatience of certain set of investors (in no way referring to them as inferior as they do what they do well), which by the way are in majority, that such knee jerk short term (even medium term) reactions happen. Its upto the other set to decide for themself whether they wish to eventually transform to the other side or grow at what they feel they were originally good at…thats why Investing is not so easy!
Personally in some of my stocks results, I have been bracing for impact a day before it will be announced 
5 Likes
I am still amused to see who the f* is alice(seller) . DII figure is always buy, FII sell for 2 days and buy for one day, retailer portion in all junk IPO’s so called tech platforms is getting subscribed 40-50 times. Mutual funds allocating capital to these mega expensive IPO’s & secondary market is begging them please don’t sell me i have already lost my shirt.
Current situation is different from 2018-19 bear market which was majorly triggered by IL&FS fiasco and cascaded to weaker NBFC’s and banks due to rise is short term rates. For last 16 trading sessions, only one day was looking like a buyers day, everything is just going down down and down. Froth built up has already started to cool down, trent down 42% PGEL 50%, these accidents will keep happening wherever results are not above estimates for growth stocks. Mutual funds inflow has cooled down to 26K from 30K. until there is a stop on large IPO’s we will face selling in mid cap small cap. Q2 earnings are overall ok. Q3 & Q4 should trigger consumption demand as cumulative liquidity infusion is 3.5 to 4 lk cr including tax, GST and interest rate cut. October inflation is down to 1% which is bad sign as it shows demand inflation is still sluggish. Cutting losses in weak positions and converging capital to high conviction bets. Last week and current week have proven to be really brutal.
11 Likes
@Cshar @Ghonarbochon Sharma ji / Ghanshyam ji… hope today is better. Last week was tough. This week feels like chaos in a chicken coop—chickens running everywhere, fox jumping around, and we keep shouting “Sell! Buy! Wait, what now?!”
It’s testing patience on some stocks, like TARIL. I have no full experience with commodity cycles, but -47% in two weeks? Yesterday, it felt like the stock might die. Still holding and added a bit more (sharks eating it up or just overreaction? That’s my view).
Dummies kept pf steady (i mean -10% in 2 wk at pf level is still steady…okay ? ) like IZMO, ADORMulti, Suvenscience. Hope they go up while the market goes down. It’s just a dream with some unclear details.
Looking at semicons and metals for the next move: already have comparative larger bets Moschip + ACI (hoping for big revenues by FY28). Metals: Vedanta is in for 3 yrs now , thinking of adding Gravita + Hindcopper. Autos look good: Ather + SMLMAH + TSFInv.
What do you think about sector strength in these 16 days? How do you spot a buyer’s day in this mess? Q: How much more pain is left? Q: When will we know we’re out of trouble—see green signs or more problems?
Share your guru wisdom, senior bosses, can we crack up over these crash pakodas—deep-fried bargains that’ll taste sweeter later ?
2 Likes
@thakurvi You are right …but its very annoying all the same for impatient ones like me .
@Investor_No_1 You are right as well . This kind of market is not uncommon .I have seen it in late 2022 and specially between Jan to March 2023 . It usually helps if one takes this phase as investing rather than harvesting phase .Problem is, I pick companies which can do well in next 1 year or so..and if that time period is spent in this kind of market, the company performance will go down by the time market becomes bullish and there goes the chance of profit .
@Cshar yes..maybe bihar elections,ipos and the weakest quarters result expectations are causing the trouble. Logically it seems ,better results are ahead in next 2 quarters but market seems to be ignoring it .I am also doing the same thing …reducing holding with weaker results(if unexpected) and adding to existing high conviction stocks which are at loss or at about same value where I bought them. Please feel free to share ideas to study .
@LarryWink Added to Taril too .Seemed like a planned campaign the way various non material things were bandied about in past 20 days .But I do not expect to get returns in next 1 year.I will take a long time to recover .I will hold it just out of spite …just because I can afford to lose it all as well because I have so many other stocks .Interestingly , all the other stocks mentioned by you were not in my radar .Have to look at those.
3 Likes
Hi @LarryWink
Shanker Sharma suggested lake theory of returns last year where he claimed that nifty 5 year returns will be zero, though i am not fully convinced with him however if we see markets as if now, each and every sector has run up in last 5 years. Main problem is PE ratio as in euphoric times same stock quotes at higher price multiples and in pessimistic times it trades at lower multiples despite good earnings as none wants to buy. This quarter good earnings have been treated ok ok, flat earnings have been punished and bad earnings have been severely punished. Clear signs are you should look for under ownership in stocks you choose to avoid large losses where earning potential is clearly visible in next 12 months. Keep a track on quarterly earnings to avoid large losses as earning reactions are severe. Diversification creates more trouble in these times. Oct inflation is close to zero which is showing that demand trend is weak as people will save more, six months doen the line consumption pick up is a high probability. Railways some pockets looks interesting. Defence is ok but long term hold. Be a stock picker and do a hard research on what you own.
3 Likes
@cshar I think your are misreading the oct inflation …considering the GST change ,lots of products have reduced in price and hence the low reading . Many companies and media outlets are saying the sales have picked up a lot post the GST change …
Also Shankar Sharma ..in most generous terms is thoroughly untrustworthy . One can trust him to do his best for himself but should have a bucket of salt ready for believing his statements for the benefit of the public .
12 Likes
Selfnote to remind myself why I added Ceinsys now(incase this decision goes south later )
The main concerns that are dragging the stock down…
- Increasing receivables and whether this will cause cash issues later . Hence EPC like valuation at 21 PE
- Whether they will be able to get new projects once the large ones are done .
- Whether the other inorganic part of the business will become profitable in time .
- Where is the acquisitions for which the QIP was done ?
- Who will be the CEO ? Surej ? To be or not to be .
Mgmt answered ?
- Big project ,recently started hence receivable will increase but they will get paid as they progress with execution.They received some 40 crores in October too. Those projects are in Maharashtra, not some poor state and BJP aligned …so should not be an issue .
- They have more than a years worth in hand plus pipeline.Mgmt says they will get more in next few months .
- The VTS business will break even next FY start .
- Aquisitons in next couple of months.Maybe two in the two business lines.
- Surej will be the CEO .
Why I added?
Market is somehow valuing it almost as a pure EPC business ,which it is not .It has other sources and those are 40% revenue wise .I still have some safety cushion as my purchase price is at 740 .The company and management has done enough in past 2 years to justify the trust .When I bought it first time at 610 after qip at 560, it went down to 400 and I did not add fearing something is wrong.Then offcourse it went up and up till 2k.I do not see much wrong in its prospects and at this price it seems fine.
Note:The edit was to correct a messed up paragraph .
8 Likes
Post results Portfolio update :
Sold off sheetal cool …on second thoughts it seems it will take too much time even if it turns around .
Sold RMC switch gears at 30% loss … well,I probably bought it too high and its going down even after posting seemingly good results. Also,any stock with gov as customer is in for a bear mauling these days .
Sold off SGLTL … for 3 quarters running they have under delivered and saying some orders were delayed to the next quarter .I do not believe them anymore . Made 30% profit and have HLE glasscoat still ,so no regrets.
Sold off Eimco Elecon….too turbulent and no orders.No visibility of the CM package sales either.Overall it was profitable but unsatisfying investment.
Sold Bluejet … at a small loss but a complete waste of time .This quarters result was an eye opener, luckily I sold before it at around 640. I do not really understand its complexity but my past experience with lauruslabs and inventory de-stocking says ,things may take longer time than I have patience for .
Added:
Active clothing at 104.1% of portfolio roughly .Seems decent bet for my High risk High reward portfolio.
20Microns at 195 .1% . Seems a good bet as a short medium term trade .
Blackbuck at .1.4% .
Rishabh Instruments@416. 1% . HrHr portfolio.
JayKay @ 230 1.2% .HrHr portfolio.
Also added to laggards like CMSinfo,polyplex,dynamic cables,redtape,Globus etc. Bought Dam Capital,Zaggle,Newgen,IDA,SAI LiFE,Vimta ,Onesource etc .
After few short term trades I have made enough profits in Shaily to keep about 1% as free stock’s . Want to see how it goes for next 3 years with the GLP1 thingy.
Holding on to CCL,Sequent ,Valiant and HBL.Getting sourly tempted to sell off HBL…so hard to hold on to a company where the management is so willing to trip up any positive stock movement with incomplete cautions .
Postscript : The spreadsheet backup of my portfolio dated 23rd april,25 says that if I had not made a single change to my portfolio since then ,I would be better off by a 1% . So much for my stock picking skills …
12 Likes
Thesis behaind adding active clothing ? We lot of other textile companies?
The only other textile company I have is VTM and I am blissfully unaware of the fundamentals of other textile companies . :)
I bought it after reading the transcript of the last concall and the latest Crisil rating report available in screener .It seemed a beauty in my eyes at 104 rupees (I should have bought more..its a very small allocation ) .You must read those to decide if you see the beauty or a beast . ;)
1 Like
So these guys are different from kpr mills and so on?
Past few weeks, every day I feel like why is it not 3:30 yet ! Seriously …whats going on..!
Kya chal rha hai ? Bas Fogg hi chal rha hai ! I mean everything is very foggy and nobody seems to have the foggiest notion .
Largecaps,mid-caps are fine…all the doom and gloom in small and microcaps! Very despair inducing situation.
Some pundits are saying and even to me it seems like market has decided that any company counting any government as client is not going to get their receivables at all and gov’s will not spend any money here on . So, its a cash flow concern …!
Seriously even if Gov spends slowly or delay payments like in JJM, does it mean they are not going to pay at all ? Since when the “dumb” retail investors who mostly rule the smallcap holdings, become so aware about cash flow ? Even more than fund houses and mutual funds !
My idea is that this BS propaganda is being peddled to shake the tree and make it easier to buy for the shakers . So holding on with my dear life and added some to ceinsys ,genesys and HBL .
Got out of CMSinfo(too much patience needed) and skipped out of intellect as the latest concall did not seem very assuring to me .That kind of talk resulted in muted performance for a long time in 2022.
Bought back some Stallion ..from the profit I made from it last time(1.1% of current PF). I am trusting the management to walk the talk.If they are crooks as the markets seem to think,I will only lose the profits as tution fee .
Added a small quantity to Valiant communications..it seems some good investors also see possibilities in this one …
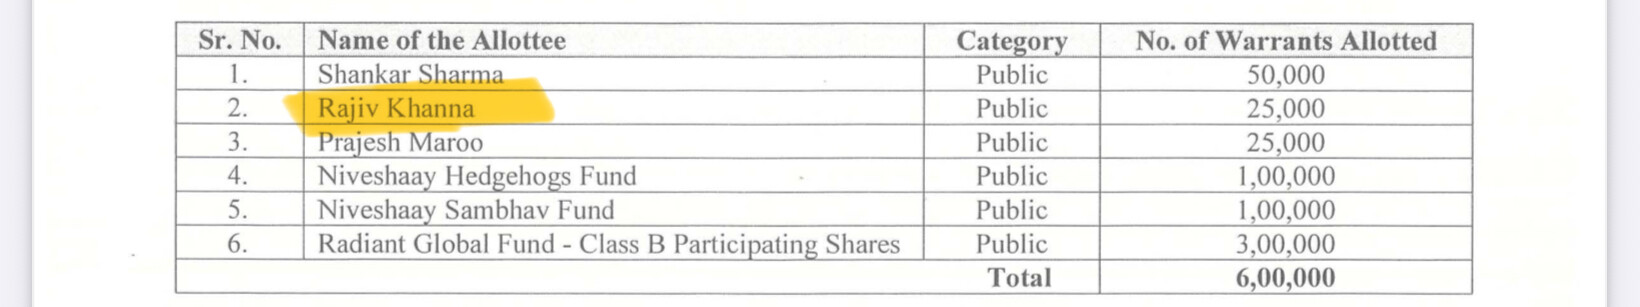
Usually I fail to add to already profitable positions ..but this time I am trying my best to increase size in high conviction bets ..hence additions to HBL,Ceinsys and Valiant .
Note…the edit is for adding the section about valiant.
10 Likes
Unable to make any sense of the markets at the moment . Hoping that by end of december , this undue negativity lifts because the results should be good and some will start taking positions for it.
Replaced Active clothing with Ginni Filaments because this is not a normal textile company anymore and has much better chance of a rerating when that becomes known widely . At this pricepoint its trading at less than 9 PE assuming the results from last 2 quarters can be extrapolated for full year.This is not a very aggressive assumption, since the company has divested its lossmaking textile unit ,reduced debt using that money and is currently ramping up its business of unwoven textile and products made from it ,namely wet wipes for various purposes. They make it for J&J and other larger FMCG companies and also selling under their own brand named Clea . So in effect ,its a B2B FMCG company with minor but growing B2C parts or a technical textile company .They have new advanced machines and contracts with major companies along with capacity to manufacture more without extra capex and reduced interest costs . All good things in my opinion.I had a look at this one back in 2022 when they stated their plan to sell the old unit but thankfully did not enter because it would have been very frustrating .
Also, added monarch surveyors and Connplex . I know SMEs are risky but these two seem to have enough physical presence on ground to justify the faith .
Sold out of Apollo Microsystems and Stallion Fluoro as I do not have enough conviction plus it seems better to close chapters on a high than suffer through a long consolidation or downward leg as was the fate of Ceinsys,Piccadilly and HBL ( damn the management),Wockhardt etc .
Edit: Details added for Ginni Filaments investment thesis since there is none in VP at the moment.
8 Likes
Even more than the market volatility and portfolio drop, the worst thing about this market is the emergence of macro specialists with 15 seconds worth of knowledge on everything under the sun including economics,policy,GDP,govs capex plan , Japanese rate , liquidity etc. Not bad if they kept their fresh of the AI farm gyan to themselves,but no…they must advertise it on every topic in the forum if anyone has to say anything positive about the near future .
I saw a rude quote sometime ago…”Opinions are like assholes, everybody has one !” . Now I know its accurate too.
6 Likes
. These are typical traits of bear markets which test conviction of even smart investors. Very few have courage to see their portfolio stocks going down more than 50% and still keep their conviction and logically you should not in all the cases and there are always things you don’t know and only surface in hard times. EQ is more important here than IQ.
Hedge funds across world have borrowed more than 18 T USD from Japan due to ultra low interest rates, Selling by FII’s in last 4 years in tune of 11 lk cr has some links to yen carry trade. Current rate differential between US and Japan rates is below 2% now hence no easy money and return of capital to Japan, expecting liquidity conditions to remain tight in 2026 as well. Really don’t have large hopes from markets in a broader level, thematic returns are in hindsight now. All asset class are in top of cycle including real state, commodity, even selling from Equities and buying Real estate or gold silver at this time is not a good bargain.
7 Likes
Experienced guys always say maximum negative sentiments are during the bottom …hoping still thats true .
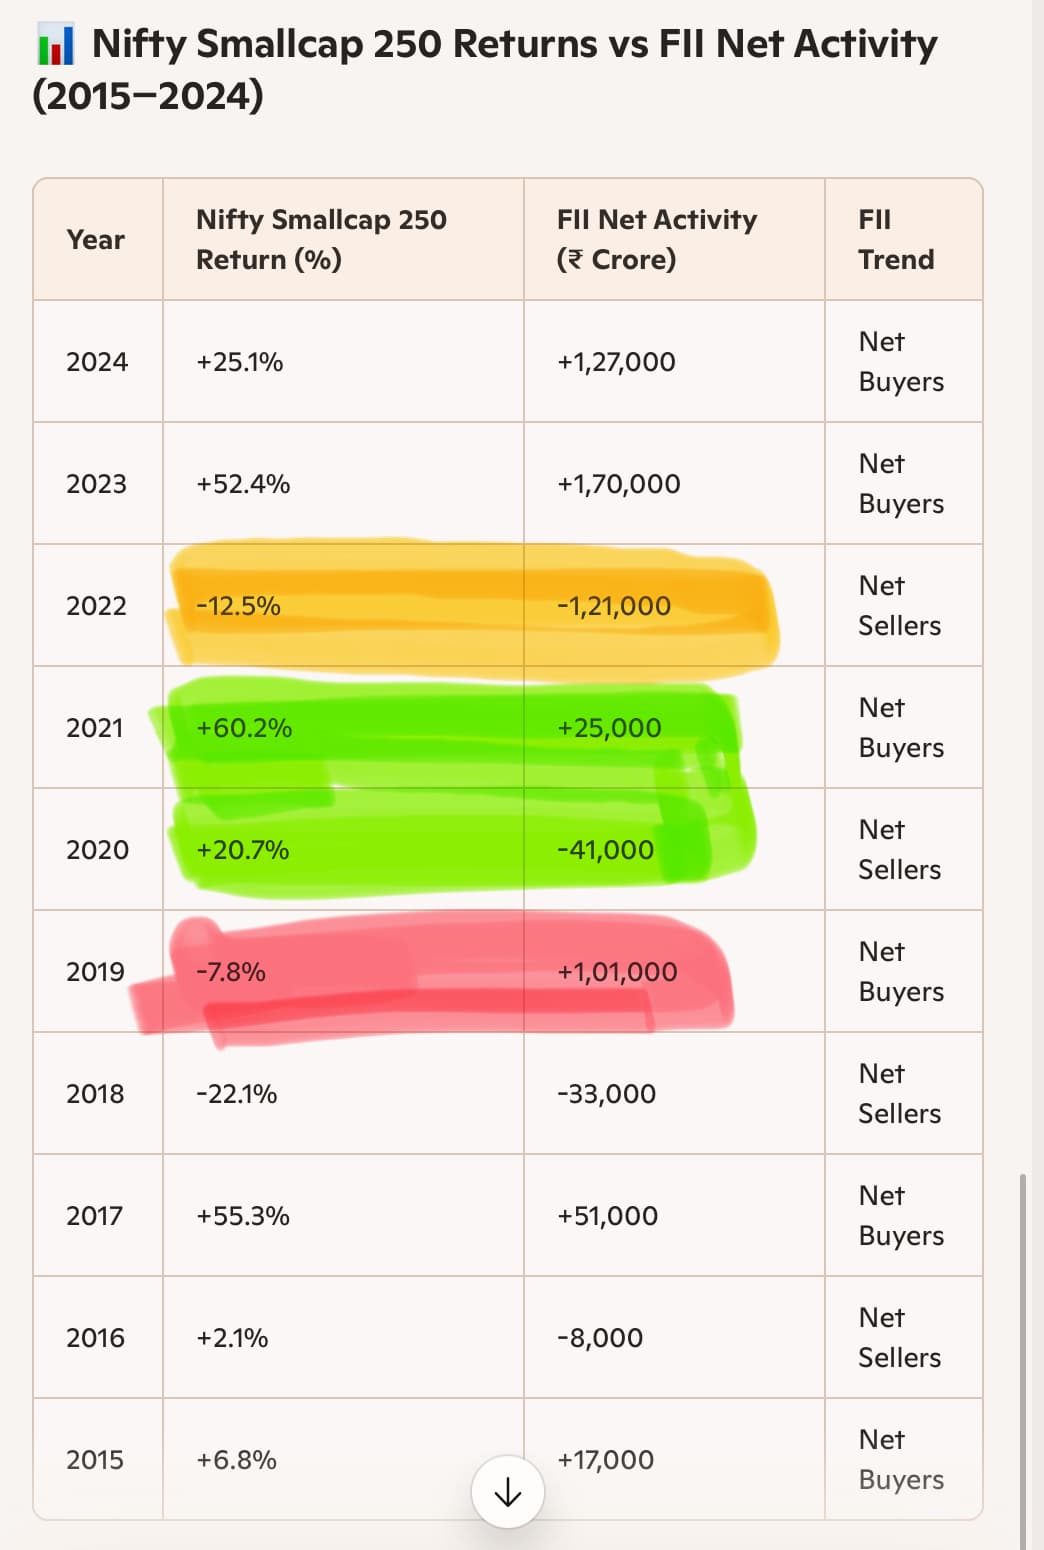
Current year till date its about 3 lac crores FII sell and only -12% returns in smallcap 250.
@Cshar Liquidity was great in 2024 and in most of 2025 in international markets ,but that did not really translate to Great returns in Indian markets but sure did in US markets.Similarly liquidity was not great in 2023 in international markets but we did fine .Also there have been many years where FIIs sold a lot but we got good returns and reverse is also true. Imho, as far as foreign investment is concerned ,we are too small a part of the pie to really sink and rise based on things you have mentioned. Frankly,there are too many variables if you look at everything that internet feeds us ..its non actionable data for individual investors .Hedge fund managers may find it useful ,and TV pundits and PMS peddler’s may wax eloquent about macros and geopolitical stuff but considering all that while managing a personal portfolio of few lacs or even a few crores is an exercise in futility .
What most people have is a delusion of workable knowledge gleaned out of these macro musings and chance sometimes proves them right and gives them the bragging rights .If it were so easy,we would have a completely efficient market with so many rich funds and people using computer models for so many years now . Plus, as a small and microcap investor , the real threat is always domestic retail sentiments/panic rather than FIIs .
Even during the 2025, I have had three multibaggers (apollo,axiscades,stallion,) out of 10 bets and quite a few 50% plus investments(cartrade, force, sml,vadilal etc.) . Its a different matter that over-diversification has worked to keep the portfolio boringly rangebound .
I have never been a theme of the moment investor …while I do trade on those when I can . Themes are tricky..too early leads to frustration and too late leads to FOMO . I just try to get reasonably safe trades to take the portfolio forward( this is not working this year) and gradually build up the stomach to invest heavily in multibagger hopes while doing my best to know the business risks.
10 Likes
So ends 2025 …the first year in my investment journey when the portfolio registered a loss YTD(-6.22%). Surely many more years like this will come but I hope that the positive years are bigger and more in in number .
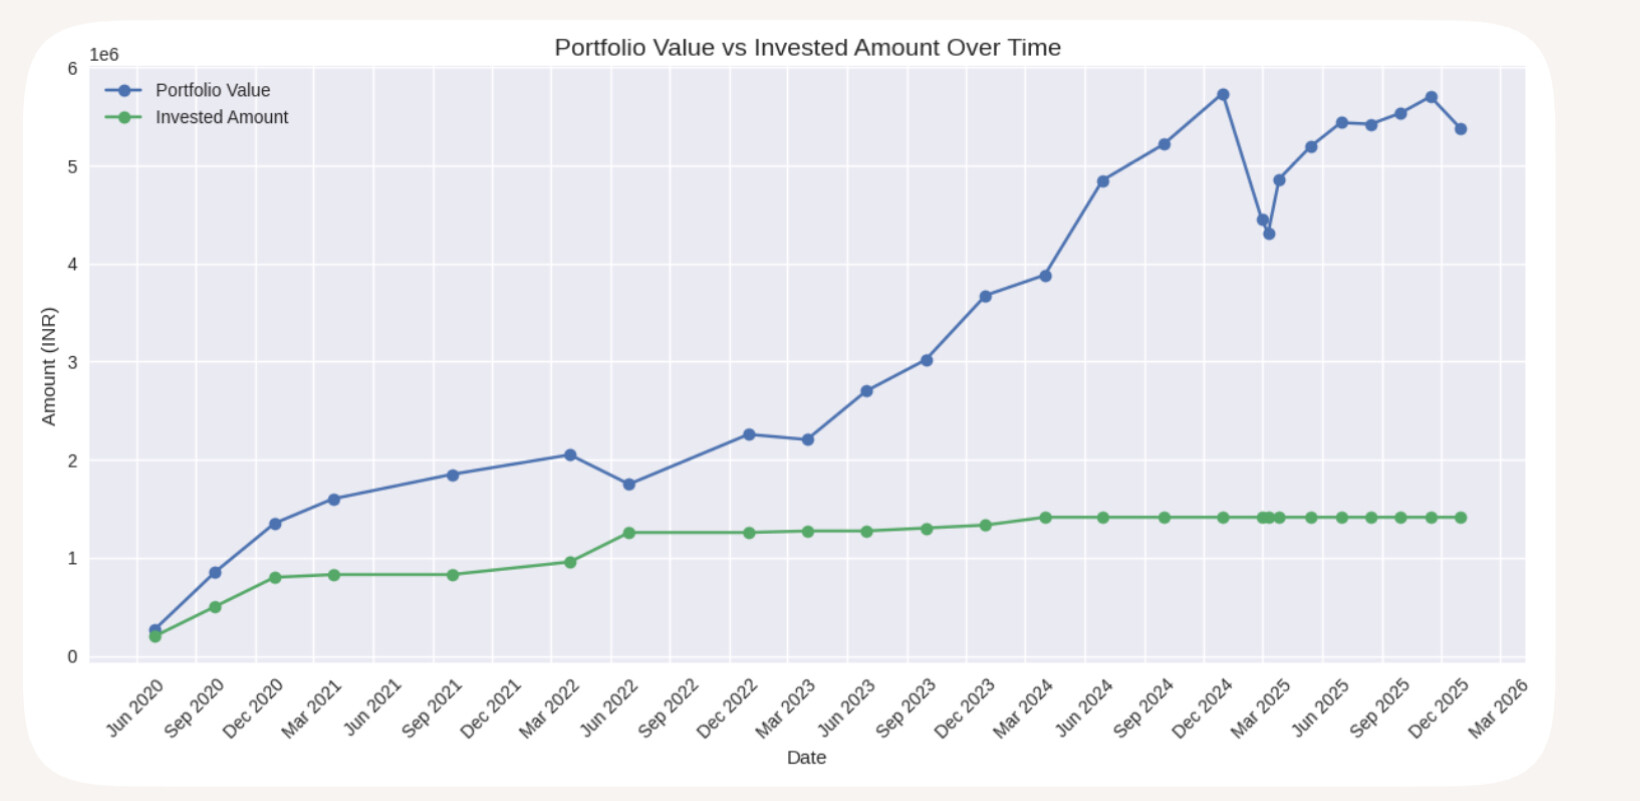
The XIRR has reduced to 34.7% from its lofty peak of 48% in 2024 .
.Have added Afcom, Neetu Yoshi last week at 835 and 111 and Marine electricals at 210(1.2% of portfolio). Portfolio is mostly without any largecaps and very heavy on companies below 3k marketcap .For the first time I have 4 SME stocks but they are not very richly priced as far as I see it and they do have potential .All are well discussed in this forum and their business has visible physical footprints .
Lets hope 2026 goes much better for the portfolio.
19 Likes
Notes on HBL Trim decision :
I will sell more than half to get my capital out and leave the profits(roughly 2.5 % of portfolio) in play.
Reasoning :
The management again gave an out of turn disclosure with extreme caution in a bearish markets .Considering the tenders of ICF and BLW is yet to be finalized,one can only assume ,that the 1000 crore minimum mentioned by the company can only be because they expect to get one L1 position at best from these two .
2679 X .815 = 2183 crores
For approved vendors = 80% of 2183 equals 1746 crores
L1 gets — 1048 crores , L2 gets = 698 crores
Doing the same for the other tender
2400 X .815 = 1956 crores
For approved vendors = 80% of 1956 equals 1565 crores
L1 gets — 939 crores,L2 gets = 626 crores
Now management has mentioned “atleast” and that implies they are not counting anything for the 7000 loco re-tenders which are yet to be declared .Hence what this means is management wants to say that they are going to do equal or better in FY27 ,than FY 26 .Unforunately , they have done so in such a hamhanded manner, that very few people will think it positive and that has reflected in this mornings price action .
Lets consider other facts —
- The company is one of the three approved vendors and first mover, yet they are getting the short end of the stick even in this benign competitive environment where a much lower quality company like Kernex have stolen the march and they did so with the same quote per Unit as last year and HBL failed.
- Come the next re-tenders, even if HBL manages to get some, they will have to do it at a lower margin just to ensure that they get the orders. Then next year, the competition will be bigger and margin will reduce further.
- In a two horse race(Medha not listed) waiting for other horses to come in this year or the next, who is going to pick HBL as the frontrunner when they can’t fill their capacity now?
- The management is undoubtedly honest and capable but they suffer from "Superiority complex " ,likes to pose on a high moral ground and prone to scatter pearls of wisdom from time to time (mostly at the wrong time ) ,yet not ready to do a concall or release a PPT every quarter even though they are quite a big and mature company.
- HBL is very well discovered and darling of too many, it is already a midcap of sorts, hence its unlikely to be a big bagger from here in short term. Still it has solid track record, great future prospects and hidden triggers on the defence side and likely to be solid compounder over the years for a patient investor.
12 Likes
This post is only for reference later on what I thought about AI and IT service companies at this point in time ….
Investors like Samir Arora and others who are calling the managements of companies like TCS and Infy short sited or dumb are just ignorant of the business of these companies . Unlike what they think these companies do not make their money from BPO ,KPO or manual activities . Even production support jobs which was basically routine Manual job at a specific time ,has been automated years ago ,long before Arora heard about AI .They make most of their money in transformation,upgrade and migration activities which is not very easy to be replaced by AI . What they are ignoring is …
-
If it was so obvious ,accenture and IBM would have built their LLMs long ago . They are in the same business as TCS,infy and better .
-
How many listed US companies have their own LLM ? Some with deeeep purses did so in past 2 or 3 years but thats only in building infra phase ,not really in LLM development .
-
If it was just a case of throwing money , Ambani or Adani would have done it .If you have a proven business that you know is going to go on ,you do not throw money in a doubtful cause .
AI agents tuned for a specific job is much better but even then integration into existing business is a long road . A company that has been running for years have deeply complex setups involving multiple generations of softwares of various types . Most do not even keep up with Microsoft OS versions and still have 2012 servers running without patch (eg. European top Telecom company) for 3 years now .Its just foolish to imagine AI will suddenly make its way into these companies and replace existing setups.Most people who are used to plug and play softwares do not comprehend the complexity of untangling or even maintaining a messy company environment and imagine AI can just replace everything .We had a very big hype about cloud computing in 2012 ,but it only found its legs in 2019 or thereabouts . My own experience in the cloud migration journey of an European investment bank tells me that its not as easy and sometimes its not even worth it as cloud costs increase faster than planned because all tiny unplanned changes needed by real world requirements add up over time and managment starts wondering about going back to on premise data centers . New companies or a new division of a company may find it easier
The big question is , will the banks and investors wait 5 years to see return on investment when its highly doubtful whether there is actually a business case . I mean why would you use AI when you can use automation and get the thing done with no chance of hallucinations . No business will risk their business and leave it at the hands of an AI thats prone to hallucinate … they never employ drug addicts if they know about it and banking companies actually do drug tests before employing outsourced IT guys .
The most threatened job is of coders but development projects are only 35-40% of IT service business revenue wise and it includes testers as well who will be more difficult to replace with AI .So I do not think , AI is going to destroy IT business or even reduce it by the same percentage as the stock prices are going down .But markets are driven by people ,most of whom do not know the businesses( The helios guy comes to mind first but there are lot more )…so prices may go down further …
For now staying away from IT stocks …service and product both . Let the fools rush out first …
Disc: Its only my opinion as I have been in the industry for about 19 years now but in a technical role .
18 Likes
In continuation of the previous post , a few observations about AI adoption in support/ maintenance/ upgrade/integration projects …
-
The client companies who engage the IT service companies are assuming that AI is already making things cheaper for the IT service companies to do a certain set of activities.Hence they are giving extra aggressive targets like cost reduction of upto 70% in 3 years where it used to be something like 30% in 5 years .It does not matter whether its feasible or AI can really do that , the point is whichever company says they will do more has their noses ahead during bidding for projects .This is already resulting in IT companies picking up projects with unreasonable targets because if one does not do it the others will say they will .
-
As a direct outcome of the first point , companies are trying to force AI deployment and reduce costs at the same time .They need to reduce costs as they need to maintain margins as well as spend bucks to deploy AI in existing projects .In real life ,deploying AI has costs which client companies are not ready to bear as there is no guarantee of success .Hence the IT companies are squeezing the employees more and reducing team size even though AI has not reduced work in any meaningful way . A close friends project is trying to force an agentic AI solution that will reduce about 5% of work for the humans,but since they will need to fund the deployment cost and maintain the margin target , the team is about to be reduced by 25% .So in effect ,AI is responsible for job loss in an indirect way not because it has reduced the human workload but because everyone is forced to jump on the bandwagon .The irony is ,the reduction of headcount being attributed to AI is not because AI efficiency and AI is actually increasing the workload of surviving employees ….
-
How long this will go on is anyones guess…but its very clear that ,AI is not going to benefit the IT service companies revenue(unless clients increase IT budget or decide to take on more modernisation based on AI savings) or profit (because clients will squeeze as much as any gain made because of AI).
-
However, since its evident that the so called AI led gain is anything but ,sometime or other spades will be called spades .Unless some other breakthrough makes AI super-intelligent at a much lesser cash-burn, debtors will get more anxious with every passing month . Amodei and his ilk has a lot of reason to say outrageously ambitious things but reality is full of edge cases which can not be disregarded casually in production environments even if they are less than a percent .Vishal Sikka did hit the nail on the head . AI is already good enough in coding to get a medium sized project done when used by an architect skillfully but its nowhere near as good when it needs to be used in a messy existing real world setup.All that talk about it replacing most white collar jobs is pure daydream or unmitigated nightmare depending on whose side you are on but none of it is real .
5 Likes