BW LPG Q1 FY25
Old news ,
Disc : Holding since the JV announced
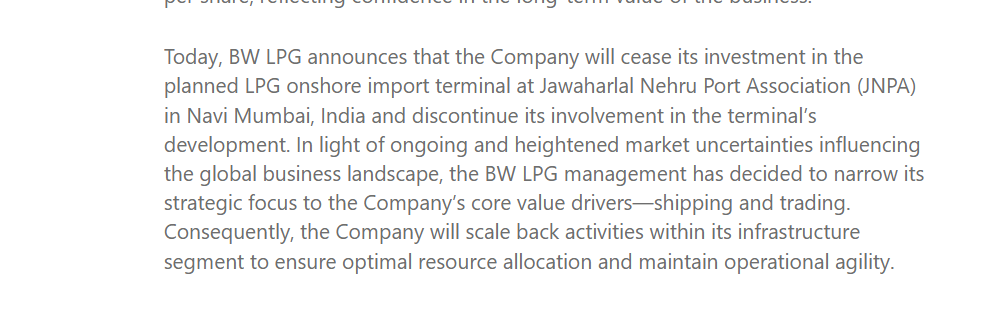
I never researched what was core business of BW LPG. Interesting that GB went with BW LPG as partner, who did not have any LPG infra experience or interests earlier. Just LPG trading and shipping experience. Maybe Gb thought this might negate any possibility of the partner being a threat, and will assist in LPG sourcing and shipping till JNPA. After that GB LPG terminal takes over for final LPG storage & confidence petroleum for distribution. 3 partners for 3 legs, wishful thinking it turned out to be stool, one gone all fell down.
Aegis on other hand ties up with Vopak (logn history of building terminals) for the capex heavy terminal setup part. But it retains the higher EBITDA last leg distribution business. Also sourcing and trading JV with Itochu is retained.
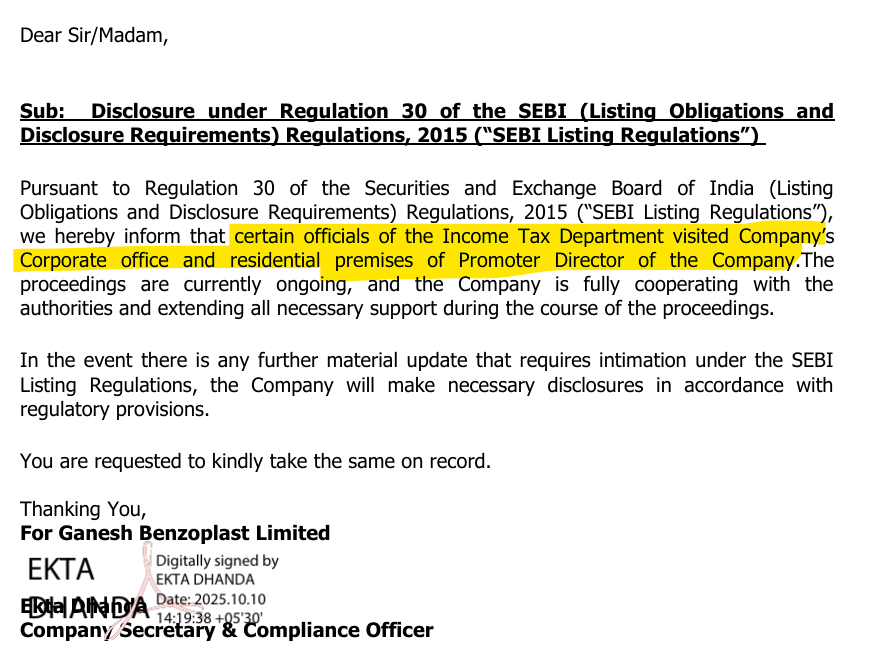
One more interesting update from the company. Somehow it does not seem to end.
No end to the soap opera, plus a mystery the stock jumps up today !!
Nice graphic summary, does this channel give similar views on all concalls ?
Company has clarified that the “The JNPT land parcel remains a key
strategic asset. The Company has initiated construction of additional storage tanks to increase capacity by approx. 1,00,000 KL and plans to utilise the remaining land for ammonia and chemical storage, with a portion reserved for
future expansion of LPG, ammonia or liquid cargo facilities.”
This is further to my last post on Ganesh Benzoplast, and important for ME, as I am taking U turn on my original thoughts.
I had initially written how I intend to stay away from the company due to its chequred past and all the recent negative developments, however, today I am with different views.
While I was negative on under provisioning for Morgan case, the settlement looks to be a step in right direction. This frees management bandwidth in unproductive tasks and also allows the company to take corporate actions (demerger, dividends etc) whatever is appropriate.
While I was negative on inability of company to make decision and move ahead with additional land parcel, my view today is that its not uncommon even for reputed companies to take too much time to decide and move ahead with huge Capex. The fact that company will have to stick to what it does with the land today, for next 25 years, makes me feel that investors can give extra time to the management, and changing plans about land usage should not be viewed too negatively
The persistence of the management to appear in front of the investors in concalls, and answer difficult questions, despite everything wrong going in the company (theft by CEO, joint development falling apart etc), looks to be a good sign. Will this act continue, I am not sure.
So what is management attempting to do?
Trying to built market cap?
Building credibility in the market which has written off the company?
Is the phase of negative surprises over for the investors?
Has the character of the company changed?
Can the company be treated as investible?
Are there genuine efforts by the management in the right direction?
These are difficult questions to answers, and each investor will have different views, which makes investing interesting.
Disclosure - Tracking position. I am a amature investor, this post is not intended to influence anyone to buy/sell.
Recent Updates -
Ganesh Benzoplast Limited (GBL) has recently faced a substantial increase in its land lease fees at the Jawaharlal Nehru Port Trust (JNPT) terminal. The annual lease rental provision for one of GBL’s older plots at JNPT surged from approximately ₹2–3 crore to ₹24 crore.
Capacity Expansion: The company is proceeding with a 1 lakh KL capacity expansion at JNPT, including the construction of 30,000 tons of A-class petroleum tanks. This is expected to generate high-margin revenue starting from FY27.
Price Adjustments: Management indicated they are seeking to demand a standard 4% to 5% year-over-year price escalation from customers and adjusting rental income to absorb the higher costs.
A 10x increase in a core operating cost is a “material event” that should have been disclosed via a standalone regulatory filing the moment the notice was received, rather than waiting for quarterly results. But then, corporate government was never this company’s strong suit.
Disc: Holding due to low valuations. Lost some capital over the course of the stock’s violent correction over the years.
An old but informative post on Ganesh Benzoplast
https://knowise.in/wp/blog/ganesh-benzoplast-ltd-a-turnaround-story/?utm_source=chatgpt.com
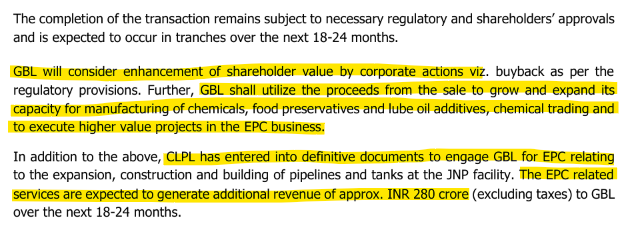
GBL sells its liquid storage tank business at terminals located at the Jawaharlal Nehru Port (“JNP”), Goa Port and Cochin Port on a slump sale basis, as well as its shareholding in ILSL Rail Logistics Private Limited (a wholly owned subsidiary of Infrastructure Logistics Systems Limited (which is a subsidiary of GBL), for transaction value of INR 1,154 crore.
They say this will generate additional 280Cr revenue over next 2 years, But most of the cash generating business is sold off. Interesting to see PE funds getting in to this business.
Press Release
Exchange Notification
Who is Cisternina Logistics Private Limited or CLPL?
KKR, a leading global investment firm, today announced the signing of definitive agreements under which funds managed by KKR will make a majority investment in Cisternina Logistics Private Limited (“Cisternina” or the “Company”), a bulk liquid and gas storage and logistics business in India. The investment will support Cisternina’s proposed acquisition of the liquid storage terminal and rail business of Ganesh Benzoplast Limited (“GBL”), which will serve as the platform’s anchor asset, as well as its expansion through further acquisitions and the development of new storage infrastructure across India. Below link has more details, this was also announced today only.
KKR to Invest in Cisternina to Build a Leading Pan-India Liquid Storage and Logistics Platform
KKR to invest in Cisternina Logistics to build pan-India liquid storage and logistics platform
My thoughts:
This entire transaction (slump sale + redeploy of the ~923Cr funds back into surviving business + EPC) will take 18-24 months to complete. GBL mgmt capital allocation has been terrible in last 10 years. Will that change with fresh capital?
I have my doubts, margin of safety is not there, in my thoughts. My personal opinion. I do not have any positions in GBL.
I request veterans and long terms trackers of this stock to put some light on this 1154 cr transaction? Why stock is hitting lower circuits when 50% of buisness is yielding cash equivalent to 100% of mcap? Won’t the cash be adding more value to existing shareholders?? And What about Jnpt unused land ??? How come suddenly company sold the cash giving business?? Chemical manf wing was about to demerge and now it has become the main stream business??? For Cryogenic plant company said that investments of 500-700 cr reqd but no such commentary from company???
I am invested, and sharing my thoughts to clear my head.
What remains after the deal…Chemicals business with a Fy26 rev of 185 cr and Op. profit of 21Cr.
Additionally, 1154 Cr comes in (there will be tax on this) and 80 cr of cash which is on BS right now. There will be some residue networth related to the chemicals business on balance sheet, but I am ignoring that as that will likely be much less. The networth/book value after the deal will be around largely 1000 Cr. Mkt cap is 896 Cr and will keep sliding I believe. My reasoning is…the promoter is not going to share these proceeds with all the shareholders in the form of dividend bcos their holding is 39%, so every 100 rs they give out as dividend, promotoers get only 39 rs.
They did mention that they will do buyback. Essentially, after 2 years the mkt cap of company will remain significantly below its networth (this networth will largely be cash, not plant/machine/land/intangible), unless they plan some really interesting use of the cash which genuinely earns higher returns.
So the situtation will be, there will be significant cash lying on BS, promoter will not distribute it with shareholders, market cap will be significantly below the networth, chemicals business could be stagnant. Bottomline…dont see light at the end of the tunnel.
An example that comes to mind is Maithan Alloys. The promoter owns 74% of the business, they have a lot of cash, and they started investing in shares, they have built a massive portfolio, didnt bother to declare dividend, the core business is not improving, share price has gone nowhere in last 5 years.
The company in todays call has shared that they will share some portion with shareholders via dividend, do a buyback in which promoters wont participate, and they envisage to scale the chemical and EPC business significantly.
So I hope the management does what they have communicated regarding buyback+dividend, that will be positive.