EMS Limited - Tapping in the growth in the water management space

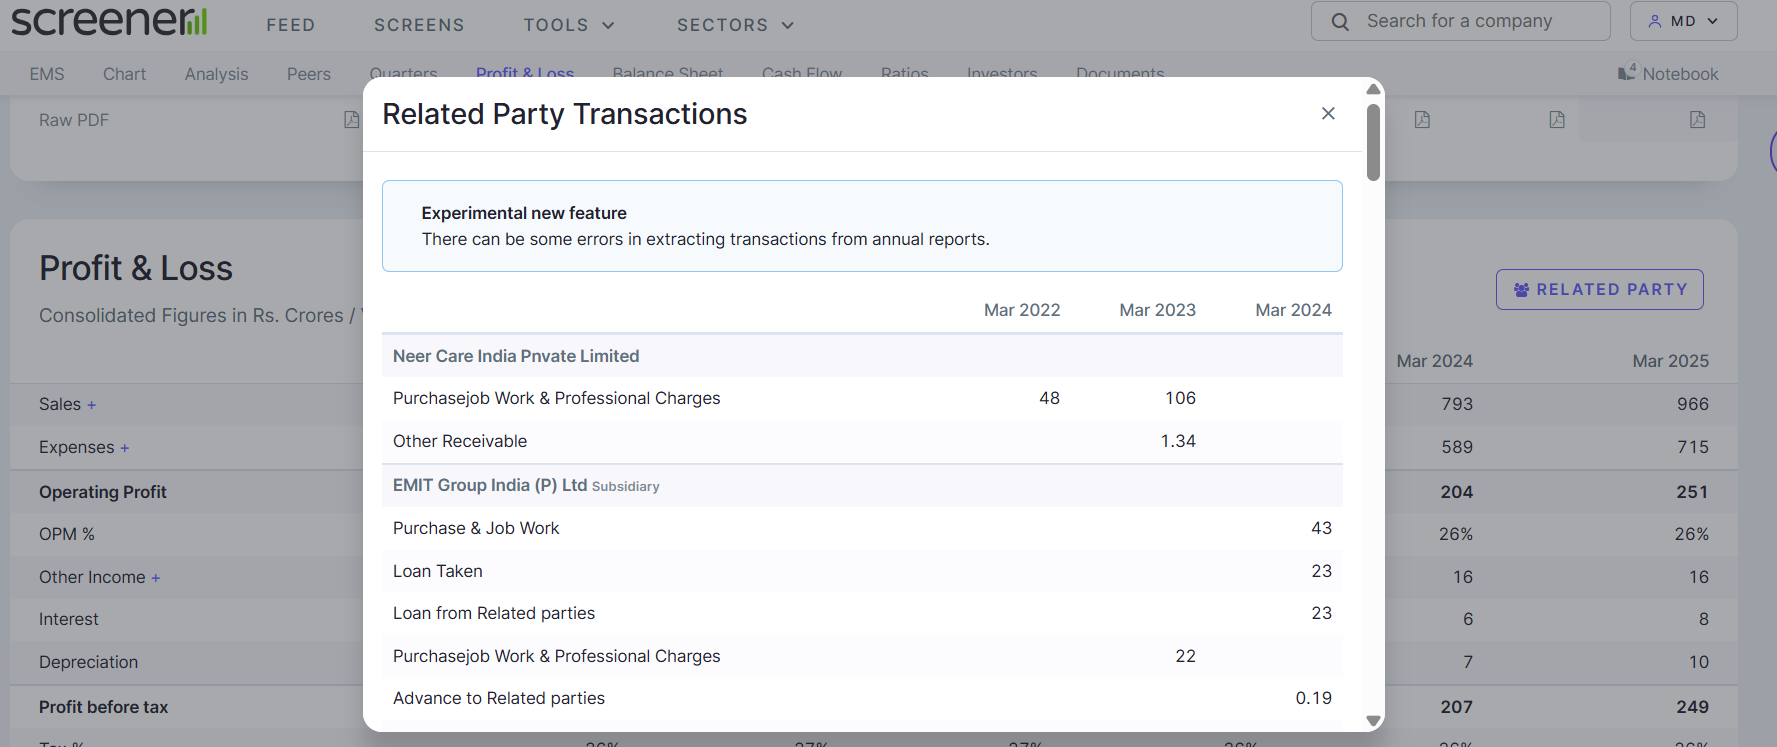
There are a lot of Related Party transactions with Promoters and their relatives.

Below transactions are Suspicious to me

  1. loans given to directors from EMS limited and its subsidiaries as well.
  2. Rent paid to relatives of promoter
  3. Loans & Advances given to Subsidiaries

I think This is a major red flag

5 Likes

@srikanth2 I am curious, where did you get the related party transaction details?

I got this from EMS website

the latest concall got pretty heated related to the above issue.


you can have a look at the full transcript here : https://ems.co.in/home/images/pdfs/Transcript-Earning-Call-held%20on-30.05.2025.pdf

3 Likes

(some good news after long time) lowest bidder for 183.81 Cr fatehpur sewerage construction offered by UP Jal Nigam https://www.bseindia.com/xml-data/corpfiling/AttachLive/3b79b309-0386-4047-a2dc-0eac5cdaeee2.pdf

2 Likes

2 Likes

The latest concall saw confrontation from one of the investor regarding this.

1 Like

EMS has been suffering from several governance issue like the Brij Bihari Saga and poor order inflow also. Now it’s high time we evaluate the risks associated with this company:

Issue Details Severity/Remarks
Promoter Conflict of Interest Chairman Ramveer Singh held 25% personal stake in Brij Bihari before EMS acquired 60% stake. High – Related party deal; possible misuse of IPO funds and corporate governance concern.
Mismatch in Acquisition Disclosures EMS claims ₹7.75 Cr paid, but filings and trail show ₹27 Cr as ‘advance’ – serious inconsistency. High – Raises concerns of financial opacity and IPO fund misutilization.
Asset Overvaluation Book value of Brij Bihari land is ₹38–40 Cr; EMS claims market value >₹80 Cr without independent valuation. Medium – No third-party report disclosed, suspicious justification.
Related-Party Debt in Acquired Entity ₹50–60 Cr of related-party borrowings on Brij Bihari’s books – risk of future debt merging with EMS. Medium – Debt may contaminate EMS’s clean balance sheet on consolidation.
IPO Fund Utilization Gaps ₹27 Cr from IPO general funds were tagged for this acquisition, but purpose/use remains unclear. High – Public capital might have been redirected with poor disclosure.
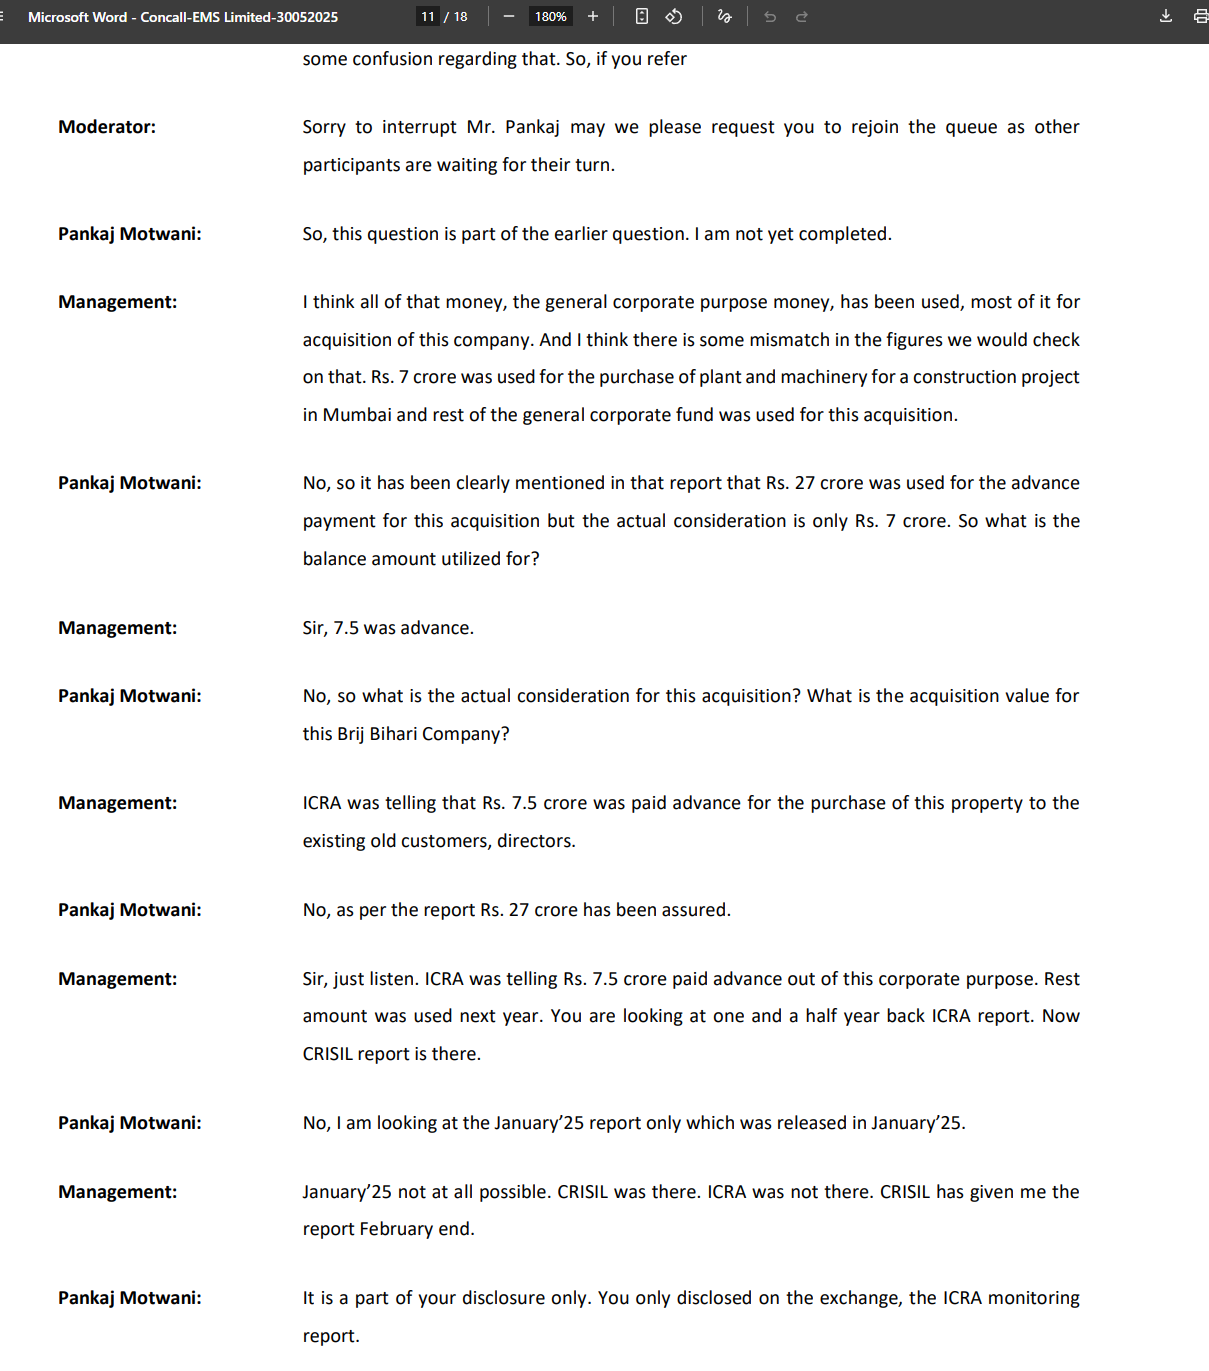
Contradictory Disclosure (ICRA vs CRISIL) Mgmt gave conflicting data in investor interactions vs filings on advance/payment structure. High – Unreliable communication, raises red flags on audit trail.
Intra-group Sales Not Eliminated ₹32.27 Cr sale to subsidiary not eliminated in consolidated results; claimed as valid revenue. High – Violates Ind AS 110; artificially inflates top line.
Unstable/Negative Cash Flow vs PAT ₹508 Cr profit in 4 years vs ₹(-82) Cr CFO; disconnect questions earnings quality. High – Risk of earnings manipulation or unsustainable accruals.
High Other Income Spike Other income jumped 907% YoY; nature not clarified as operational or one-time. Medium – Could be profit inflation from non-core activity.
Disputed Receivable of ₹34 Cr Unprovided Debtors of ₹34 Cr under dispute; no provision created. High – Violates prudence principle; may inflate asset quality.
Real Estate & Road EPC Diversification Plan Company announced entry into non-core sectors; later rolled back due to feasibility concerns. Medium – Strategy volatility; earlier communication proved premature.
Overdependence on Government Contracts Over 90% of revenue tied to government projects, exposing it to policy/payment delays. Medium – Sector risk inherent, needs diversification or risk management buffer.
No Operating Leverage Plan Management failed to present a clear roadmap for maintaining margins during 30% topline growth. Medium – Indicates reactive rather than strategic margin control.
KMP Salary Disproportionately High ₹13.76 Cr paid to KMPs (out of ₹23.78 Cr total employee cost) – 58% of payroll. Medium – Excessive payouts raise concerns on stakeholder fairness.
13 Likes

My view on Acquisition of Brij Bihari Paper & Pulp Pvt Ltd by EMS:

Lets start from the beginning:

The company got listed on September 2023 via an IPO that raised ₹321.25 crore:

  • Fresh Issue : ₹146.24 crore
    • ₹101 crore for working capital
    • ₹36.5 crore for general corporate purposes
  • Offer for Sale : ₹175.01 crore

On August 10, 2024, EMS Ltd made an unusual announcement—it would acquire 75% stake in a barely 1.5 year old paper company, Brij Bihari Paper & Pulp Pvt Ltd . This move left many investors puzzled. Why would a water infrastructure EPC player buy a non-operational paper manufacturing company?

What is Brij Bihari Paper & Pulp?

Brij Bihari Paper & Pulp Pvt Ltd was incorporated on January 10, 2023 . Its stated purpose: to manufacture duplex paper.

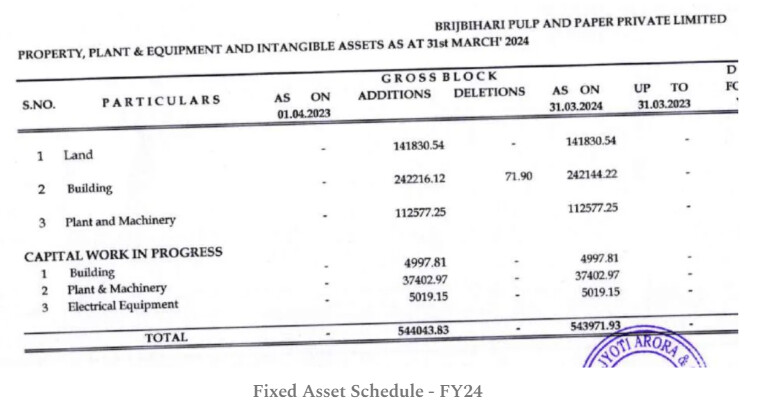
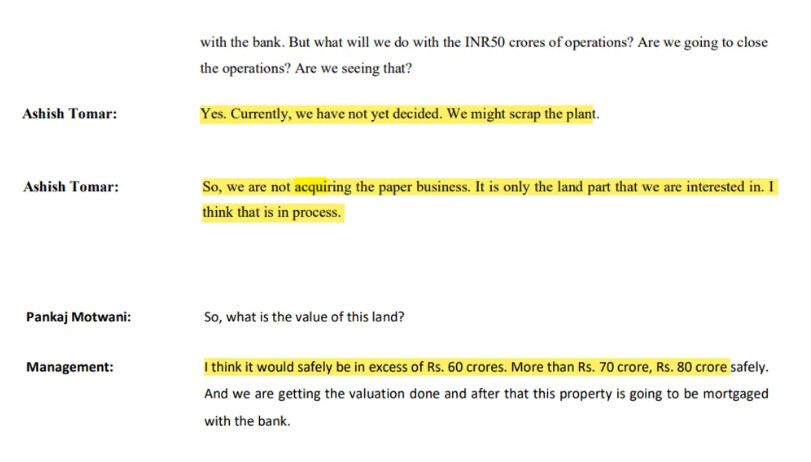
Promotors of Brij Bihari acquired some property (incl. Land, Building , Plant & Machineries) through the NCLT worth Rs ~50 cr and they expect the market value of Land & Building would be ~70-80 cr

A company incorporated 1.5 years back before the announcement by EMS ltd to acquire it

Ownership Trail: Who Owned Brij Bihari?

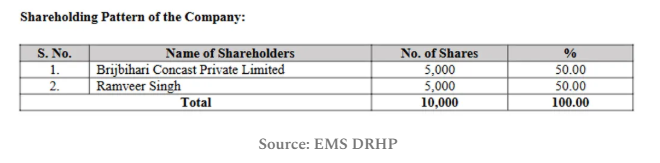
At the time of EMS IPO (Sep 2023):

  • 50% – Ramveer Singh (Chairman & Promoter of EMS Ltd)
  • 50% – Brij Bihari Concast Pvt Ltd

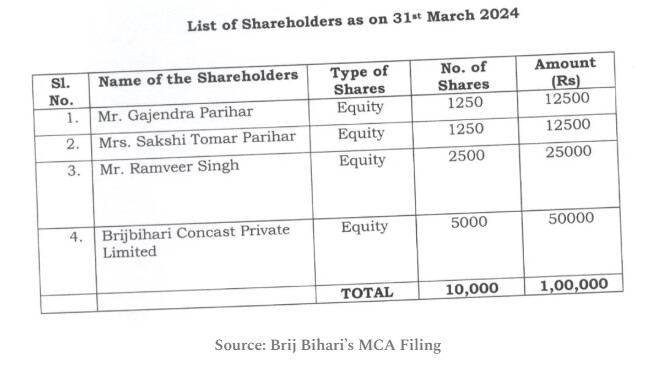
As of March 2024:

  • 25% – Ramveer Singh
  • 12.5% – Mrs. Sakshi Tomar Parihar (his daughter)
  • 12.5% – Mr. Gajendra Parihar (his son-in-law)
  • 50% – Brij Bihari Concast Pvt Ltd

It appears that Mr. Ramveer Singh transferred part of his stake (25%) to family members before March 2024, possibly to avoid direct linkage between the EMS promoter and the company being acquired.

Since they initially announced plans to acquire a 75% stake, it is possible that this 75% comprises 12.5% from Mrs. Sakshi Tomar Parihar, 12.5% from Mr. Gajendra Parihar (his son-in-law), and 50% from Brij Bihari Concast Pvt Ltd.

Inside Brij Bihari’s Books: What did EMS saw?(FY24 – MCA Data)

I have downloaded the Brij Bihari Paper & Pulp Pvt Ltd FY24 Financials from the MCA portal to check their financial health:

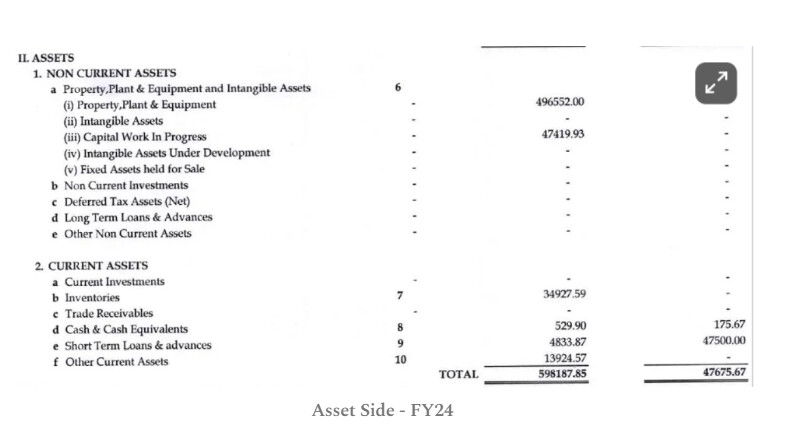
  • Total Assets : ₹60 crore
    • ₹54 crore in tangible assets
    – ₹39 crore in Land & Building
    – Balance in plant & machinery, inventory


Liabilities :
• Share capital: ₹1 lakh
• Related party borrowings: ₹59 crore

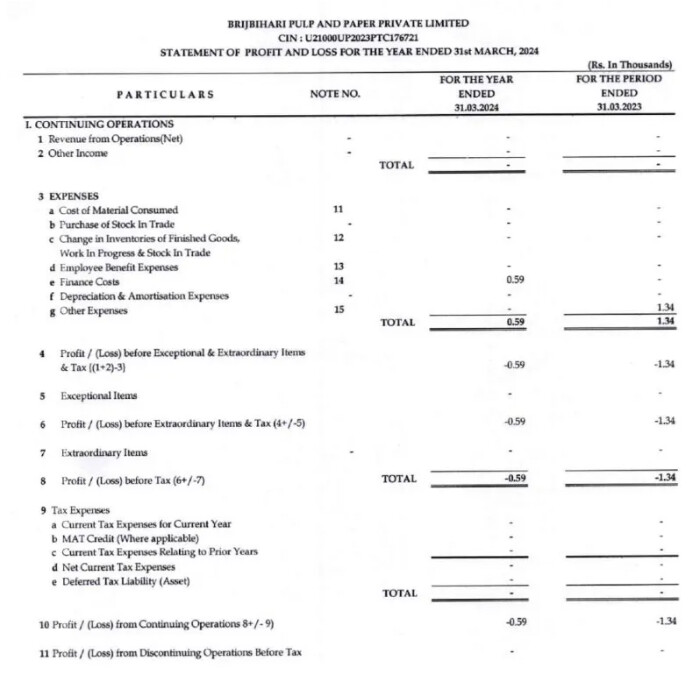
  • P&L Statement of Brij Bihari Pulp & Paper - FY24:

  • The company had no operations in FY24. Its P&L is blank, meaning no revenues, no expenses. Surprisingly, it didn’t even book depreciation, despite holding ₹60 crore worth of assets on its balance sheet.

:pushpin: Essentially, it’s a highly leveraged company with ₹59 crore debt from the related parties (Mr. Ramveer Singh & Mr. Rajiv Agarwal of Brij Bihari Concast Pvt Ltd) with no revenue in FY24

Purpose of Acquisition (As per EMS)

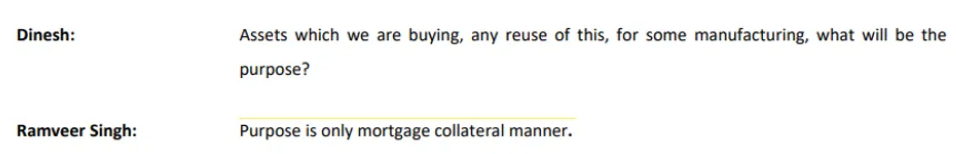
  • EMS claims it is not interested in operating the paper business.
  • The only interest lies in the Land & Building worth ₹39 crore , which has a claimed market value of ₹70–80 crore .

    EMS plans to mortgage these Land & Building to arrange financing (e.g., working capital loans).
  • All other assets—including plant, machinery, and inventory (~₹20 crore)—are non-core for the EMS, thus they might impair them in future.
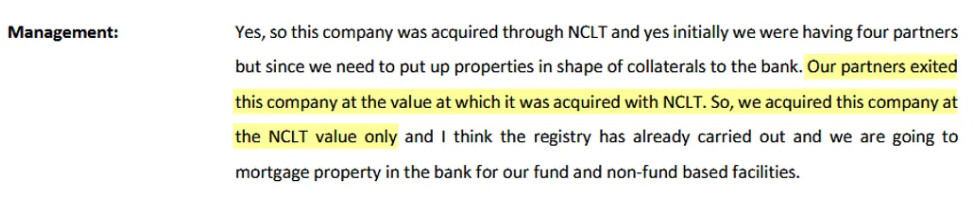
  • EMS stated that Brij Bihari Concast is exiting at the same value at which they bought these assets from NCLT, implying EMS is acquiring all those properties at price at which it were acquired from NCLT.

What Did EMS Actually Pay?

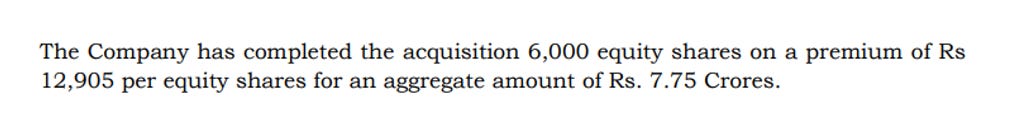
  • As per EMS’s exchange filing (Mar 27, 2025) , the 60% stake was acquired for ₹7.75 crore .
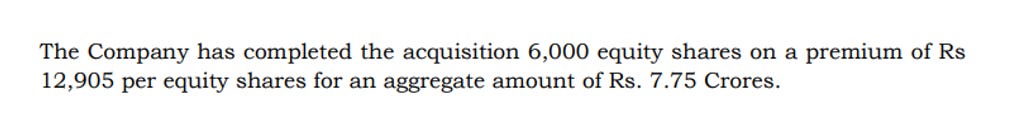


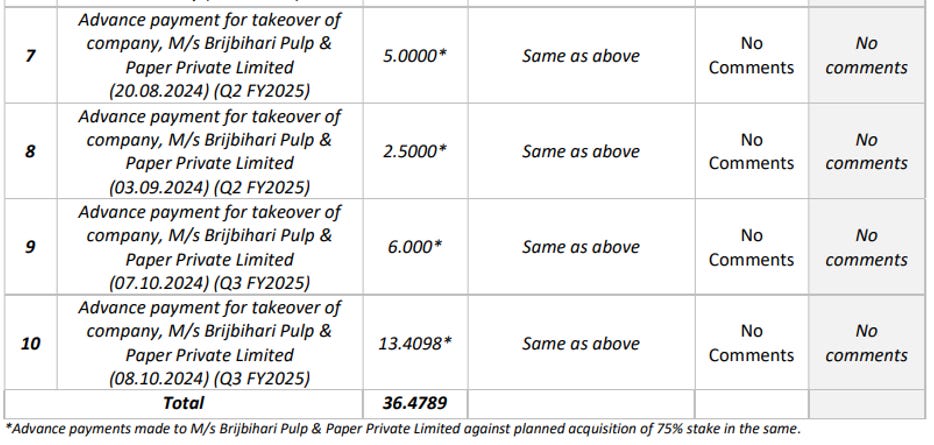
  • But the ICRA Monitoring Report (Jan 2025) noted that ₹27 crore of IPO funds had already been advanced for this deal.
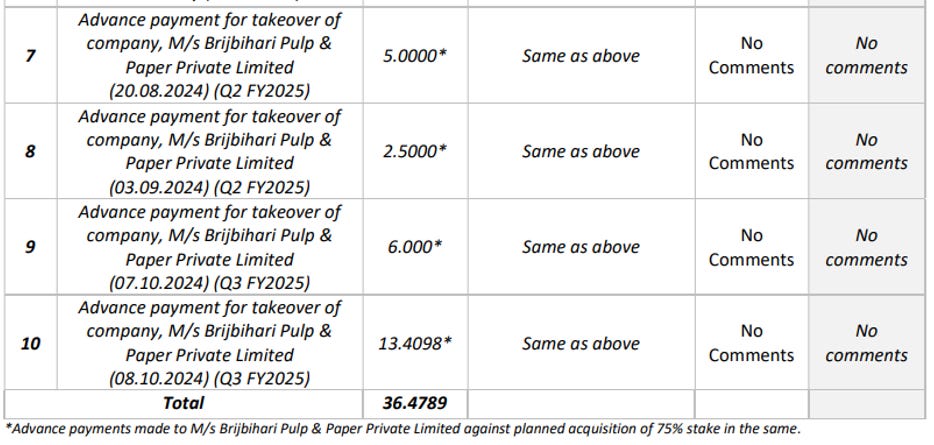


That’s a ₹19 crore unexplained gap . No disclosure has been made to clarify this difference.

  • While EMS initially announced acquisition of 75%, they ultimately acquired 60% in March 2025. This suggests:
  • EMS likely acquired the entire 50% stake of Brij Bihari Concast
  • And possibly part of the family stake (daughter/son-in-law)

Connecting the Dots – How This Was Set Up

Let’s piece together how this acquisition came about:

  1. Jan 2023 – Ramveer Singh and Brij Bihari Concast set up Brij Bihari Paper with ₹1 lakh capital with 50-50 stake in Brij Bihari Paper & Pulp Pvt Ltd
  2. This newly formed company acquired distressed assets worth ₹60 crore (including ₹39 crore Land & Building) through NCLT .
  3. To fund the purchase, both parties gave loans, resulting in ₹59 crore related party debt on the books.
  4. During FY24, Brij Bihari booked all the assets—but ran zero operations , and surprisingly no depreciation was charged during that period too.
  5. By March 2024, Ramveer’s 25% stake was shifted to his daughter and son-in-law.
  6. In August 2024, EMS announced it would acquire 75% stake in Brij Bihari.
  7. EMS had given Advances worth Rs. 27 cr for the takeover of Brij Bihari Paper.
  8. In March 2025, EMS disclosed that it had actually acquired 60% stake for ₹7.75 crore.

Critical Questions

  • If the land’s market value is really ₹70–80 crore, why is the seller (Brij Bihari Concast) exiting at cost?
  • Why did EMS use ₹27 crore from IPO proceeds for a stake that’s later disclosed to cost only ₹7.75 crore?
  • Why acquire a company with ₹59 crore of related party debt, just to mortgage one ₹39 crore asset?
  • What exactly is EMS valuing at ₹7.75 crore when Brij Bihari Papers carries ₹59 crore of borrowings, has only ₹39 crore in tangible assets, and effectively delivers negative net worth ?
  • Why were family members inserted into ownership before the acquisition was announced?
  • Interestingly, during EMS Ltd’s IPO in September 2023, the company earmarked ₹36.50 crore under “General Corporate Purpose.” With ₹26.25 crore—about 75% of this amount—used in this acquisition, it raises a critical question: Was the Brij Bihari acquisition planned even before the IPO?

Governance Red Flags or Strategic Play?

While the company claims it’s purely for collateral purposes, the structure, timing, and stake transfers to family members raise eyebrows from a governance perspective. Investors should watch closely how:

  • EMS services the inherited ₹59 crore debt
  • Utilizes this land-backed collateral
  • Books impairment, if any, on non-core assets

My View: Even a “Free” Acquisition Looks Risky

EMS has paid 7.75 cr for this deal with remaining 19 cr remains unexplained.

My view is even if EMS Ltd acquired Brij Bihari Paper & Pulp Pvt Ltd at free of cost, the deal still brings along nearly ₹59 crore of borrowings. In exchange, EMS gets land and building valued at ₹40 crore—essentially paying ₹60 crore in debt for a ₹40 crore asset. The rest of the assets (₹20 crore) are likely impaired or non-functional.

There’s no operational business being acquired. In fact, EMS has explicitly stated it doesn’t intend to operate Brij Bihari’s core business.

At best, this appears to be a move to acquire a real estate asset, possibly for use as collateral which means blocking capital for a single-purpose asset (collateral), while inheriting a leveraged company

But the key question remains— Is this capital efficiency or a potential misuse of shareholder funds?

Disclaimer: All the insights shared here are based on facts I’ve gathered from public records and company announcements. I’ve tried to stay neutral and objective, but this post is purely for informational purposes—not a stock tip or investment call. Always do your own research!

Not invested
22 Likes

Statutory auditors resigned. Another huge red flag

Plus this -

"On a consolidated basis, EMS Limited has achieved a 15.81% increase in revenue
during the quarter under review; however, profit has risen by only 2.42%. This
variance is attributable to the manufacturing segment i.e the newly acquired
Subsidiary, EMS Industries Private Limited (Formerly known as Brij Bihari Pulp and
Papers Private Limited) which is currently in its initial stage of operations and will
generate a margin of approximately 10% in future. Given this lower margin in the Qtr
ended June 30,2025 in manufacturing segment, consolidated profit growth appears
modest despite the strong revenue performance. It is important to note that the
increase in revenue reflects growing sales volumes and market penetration, and as
manufacturing operations mature, margins are expected to improve in the following "

They’re now going to operate the paper plants!?

The shenanigans of this management… It’s quite amusing actually (Unless you’re a shareholder)

DISCLOSURE - NOT INVESTED. Was studying but seeing all the tricks management were doing, stayed away from it.

9 Likes

*AND THE SAGA OF FINANCIAL SHENANIGANS CONTINUES:*

Red flag/Risk analysis from Q1FY26 Concall transcript:

  1. Accounting Treatment of unutilized PPE (Property, Plant & Equipment) of Brij Bihari (renamed as EMS Industry Pvt. Ltd.):

Red Flags Identified

  • Misleading justification: Asset acquired for “business purpose” but only 20% actually used.

  • Accounting manipulation: 80% shown as CWIP to avoid depreciation, artificially boosting profits.

Situation Correct Accounting (Ind AS) EMS’s Treatment Issue
Assets that are ready for use but idle (e.g., building, machinery that could be used but isn’t fully utilized) Must be classified as PPE and depreciation must be charged, even if idle (Ind AS 16, Para 55–56). Classified as CWIP, no depreciation charged. Incorrect – artificially avoids expense, inflates profits.
Assets that are still under construction or not ready for intended use Can be classified as CWIP; no depreciation until ready. EMS lumps all “not currently used” into CWIP. Misleading – “not used” ≠ “not ready”. Usage is a business decision, not an accounting criterion.

One investor Pankaj Motwani raised this issue of not charging depreciation on the full amount of asset and violation of Ind AS16. In response Management said that only 2 out of 5 machines are operational.

** Verdict**

Theoretically incorrect under Ind AS 16.

Assets that are ready and available for use but temporarily idle must be classified as PPE and depreciated, not parked under CWIP.

EMS’s approach = aggressive accounting / earnings manipulation.

Contradiction: Earlier rationale (collateral for banks) vs current usage (mostly idle).

Selective disclosure: Ignores related-party loans, only emphasizes “no bank loans.”

Capital efficiency concern: Money tied up in non-productive assets, hurting return ratios.

  1. Acquisition of EMS Realtech Pvt Ltd (Aug 2025)

** Key Facts**

Target: EMS Realtech Pvt Ltd, incorporated 2013, engaged in Real Estate business.

Financials: Zero turnover for the last 3 years (FY22–FY24) — effectively a dormant shell.

Transaction: 100% stake acquisition (10,000 shares). Consideration to be in cash (exact price yet to be decided by takeover committee).

Related Party: Promoter & Chairman Ramveer Singh and MD & CFO Ashish Tomar are already directors and members of EMS Realtech. Transaction falls under Related Party Transaction (RPT).

Timeline: Completion expected in 90–120 days post-committee report.

Material Update: Still in drawing phase, Construction likely to start in November. Although management claims the land parcel to be at Rs 200 to 250 cr, they said it was taken at face value, not at market price.


Risks & Red Flags

Issue Why It’s a Concern
Dormant company with NIL turnover Buying an entity with no operations or revenue track record raises doubts on business rationale.
Unrelated diversification Target operates in real estate, which is completely outside EMS’s core water & sewage EPC business. Risk of capital misallocation.
Related Party angle Promoters Ramveer Singh & Ashish Tomar are directors/members in the target company. High conflict of interest risk — potential promoter enrichment.
Opaque valuation Consideration not disclosed upfront; left to a committee. Without independent valuation, risk of overpayment or misuse of shareholder funds.
No strategic clarity Management has not explained how this acquisition supports EMS’s long-term strategy (water infra focus). Looks opportunistic and possibly promoter-driven.
Governance overhang Combined with earlier Brij Bihari saga, this raises pattern concerns about questionable acquisitions linked to promoters.

promoter Ramveer Singh’s dual role in both EMS Ltd and Realtech, coupled with face-value transfer of a “₹200–250 cr land bank” with no revenue, strongly suggests promoter self-dealing and diversion from EMS’s core EPC business.

  1. Resignation of Statutory Auditor wef 12th Aug, 25: declared reason is pre-occupation in other assignments
11 Likes

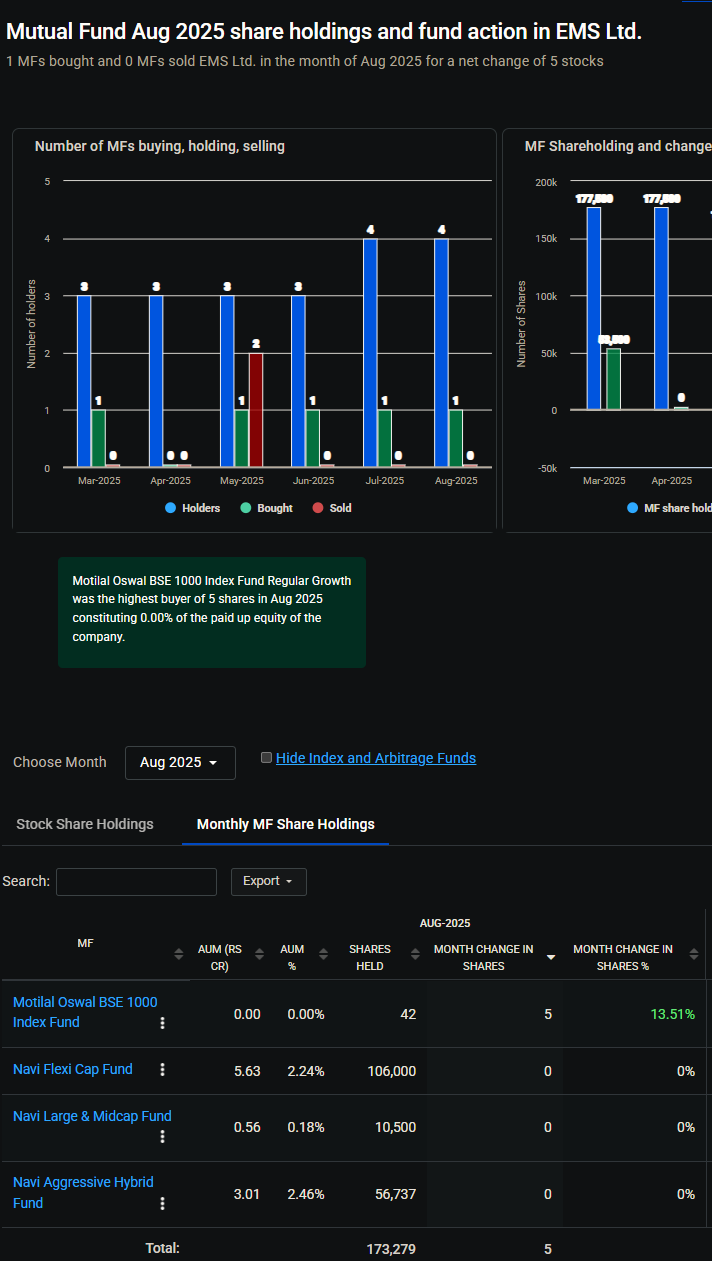
Navi mutual fund is still holding EMS as per August month portfolio..maybe either they dont care because its a somewhat small portion in their nav, or maybe they feel things are still alright despite the valid concerns

Mutual Fund Aug 2025 share holdings and fund action in EMS Ltd.

1 Like

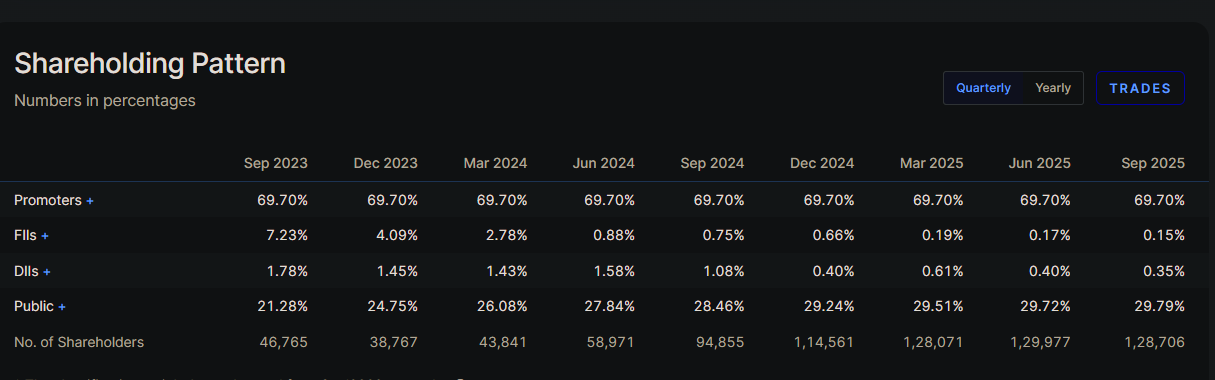
FII and DII continue to sell, its best to remain cautious on EMS..

3 Likes

one reason can be due to the points being discussed above in this thread

1 Like

Adopted from the Q2 FY26 concall

Q2 and H1 FY26 Performance and Operational Challenges

• Q2 Revenue Decline: The company experienced a decline of about 26-27% in its figures for Q2 FY26.

• Reason for Decline: The primary cause was unexpected high pan-India monsoon rains . The company operates in six states, and heavy rain hindered underground execution work across several projects.

• Operational Impact: Digging work necessary for laying sewers had to be stopped entirely because continuous rain causes the arc to collapse, posing a safety risk to nearby civil structures like buildings and electrical systems.

• Work Continued: Only over-the-ground works, such as the construction of Sewage Treatment Plant buildings or Water Treatment Plant buildings, could be performed.

FY26 Guidance and Growth Strategy

• Annual Growth Projection: The company is still committed to achieving 18-20% annual growth for FY26 compared to FY25.

• H2 Ramp-up: While traditionally H1 provides 40% of the revenue, the weak Q2 means H1 FY26 yielded only about 33% of the annual target. The company plans to deliver 66% of the annual revenue in H2 , with a significant ramp-up of progress expected to be visible in Q3 (December quarter) and maximized in Q4 (March quarter).

Order Book and Bidding

• Unexecuted Order Book: The current unexecuted order book is precisely ₹2380 crore . This represents 2.5 times the FY25 unexecuted order book.

• Pipeline and Expectations: Tenders worth about ₹4000 crore are in the pipeline, and the company expects to add a minimum of ₹500-600 crore in further orders during the current financial year.

• Execution Period: The usual completion period for projects is two years, allowing the company to easily execute 45% to 50% of the order book annually.

• Winning Rate: The typical winning rate (strike rate) when bidding for contracts is usually around 15% (sometimes 17-18%).

3 Likes


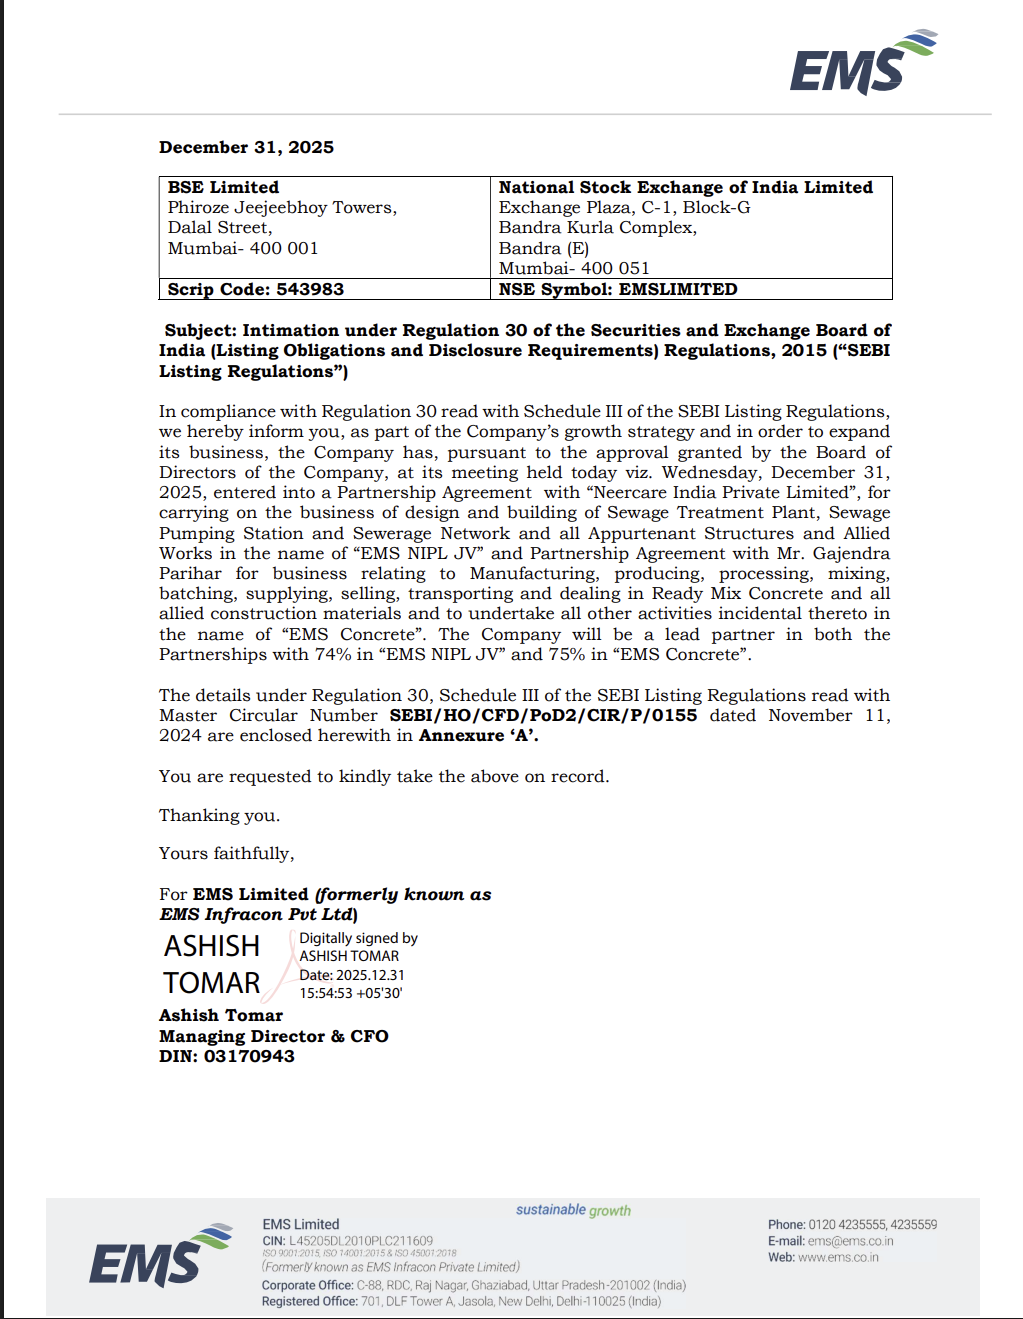
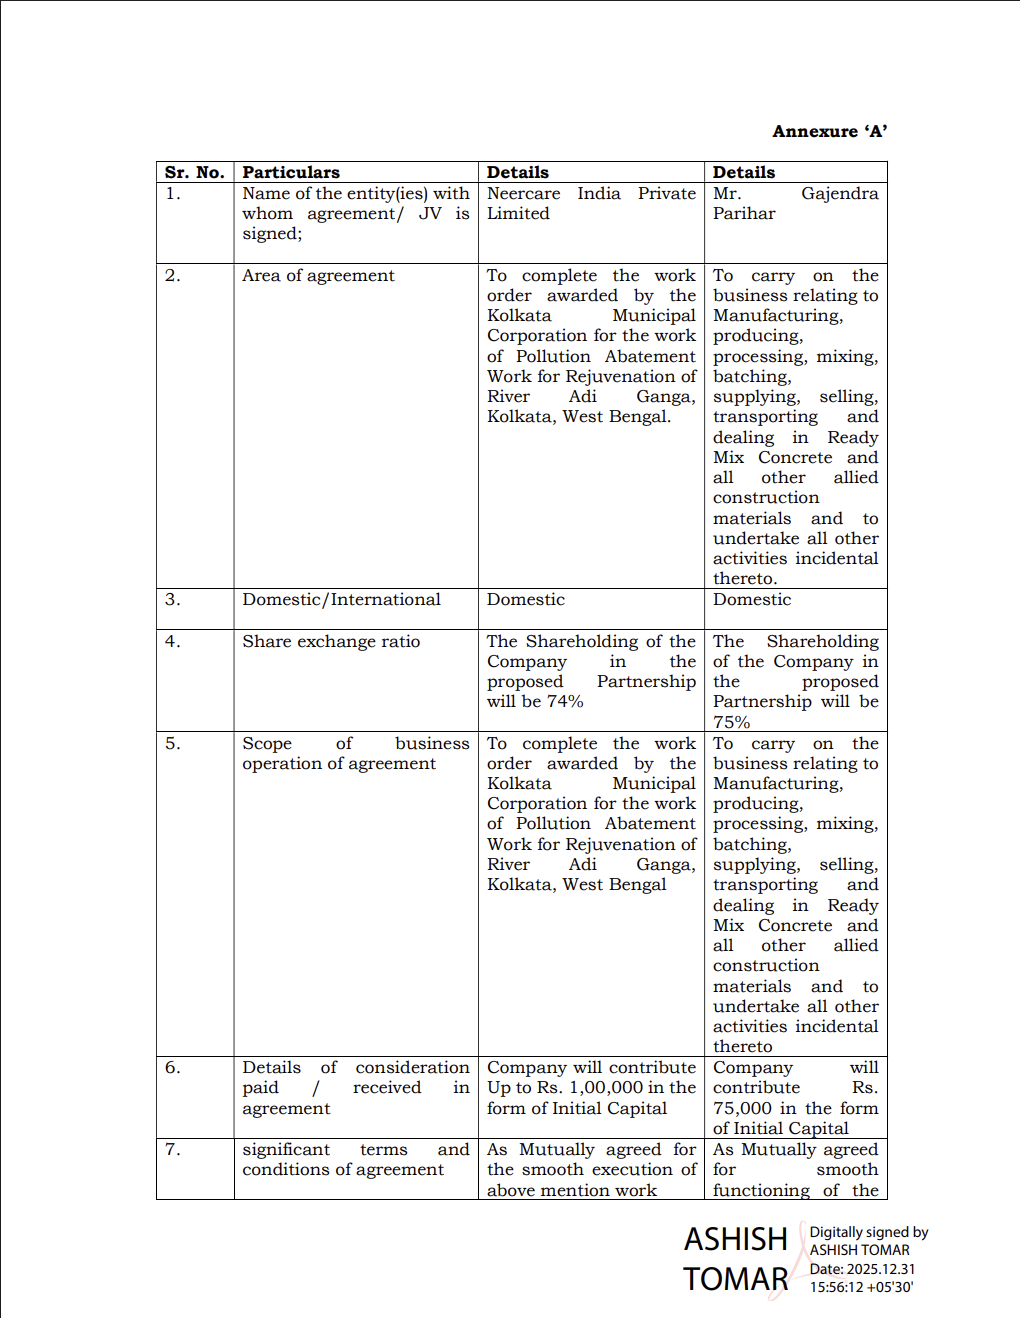
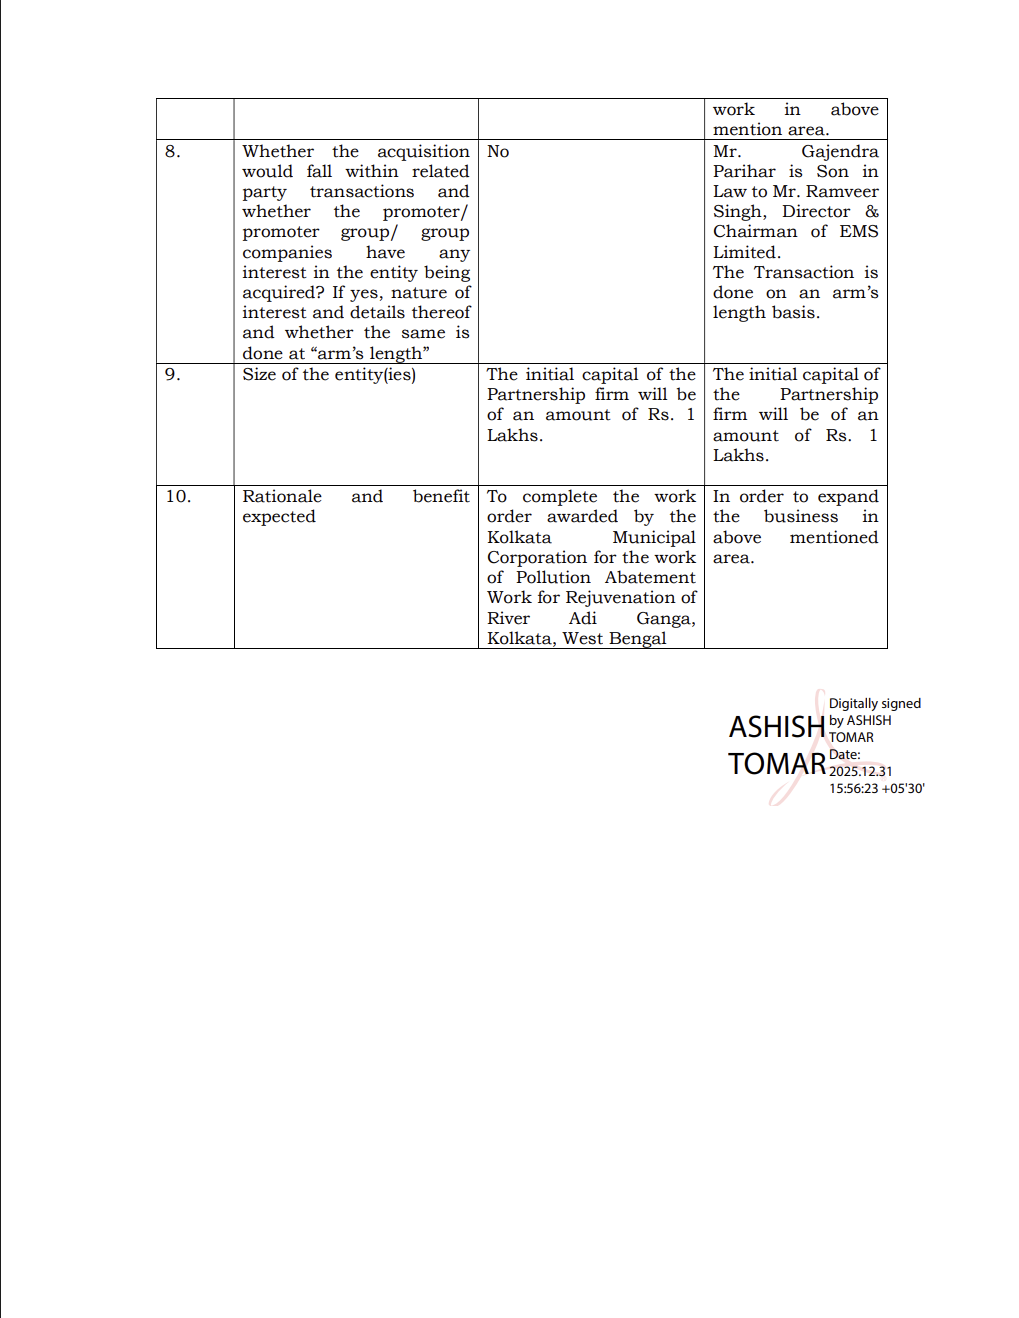
MAJOR RED FLAG: Related Party Transaction (Point 8)

The partnership “EMS Concrete” is with Mr. Gajendra Parihar , who is explicitly stated to be the Son-in-Law of Mr. Ramveer Singh (Director & Chairman of EMS Limited). This is a classic related party transaction (RPT) .

The rationale for choosing a family member as a partner, rather than an established industry player, is unclear.

Extremely Low Initial Capital (Points 6 & 9)

The total initial capital for both partnerships is shockingly low.

  • EMS NIPL JV: EMS to contribute only ₹1,00,000 for a 74% stake in a municipal sewage project.
  • EMS Concrete: EMS to contribute only ₹75,000 for a 75% stake.

This capital is symbolic and inadequate for any meaningful construction or manufacturing business.

a. The real funding will come later via loans or advances from EMS Limited, which may not require the same level of disclosure or shareholder approval.

b. 1. The partnerships are likely structured as “shells” or Special Purpose Vehicles (SPVs) to execute specific contracts, isolating risk but also creating opacity. The listed company’s funds will flow into these vehicles.

Disc: Holding

2 Likes

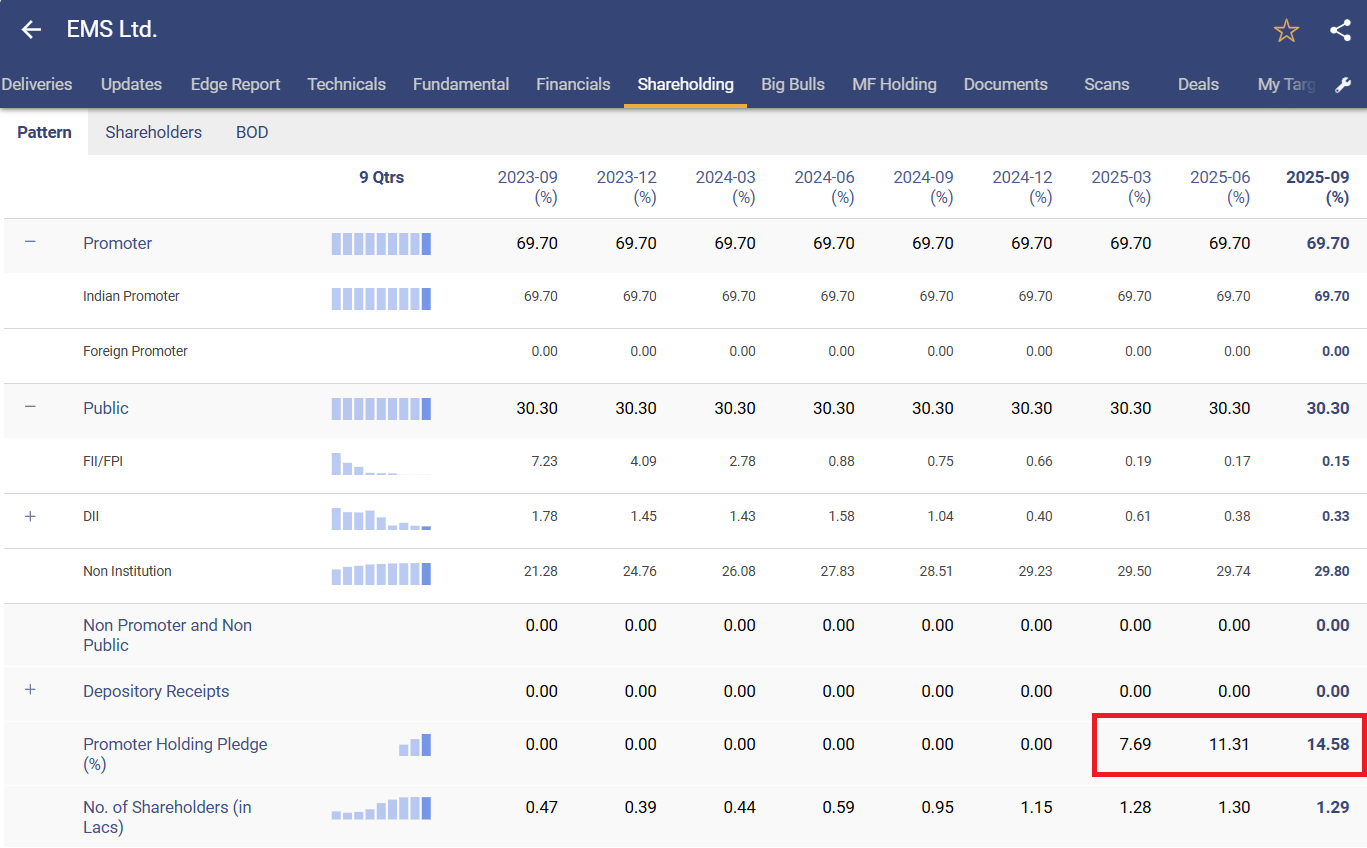
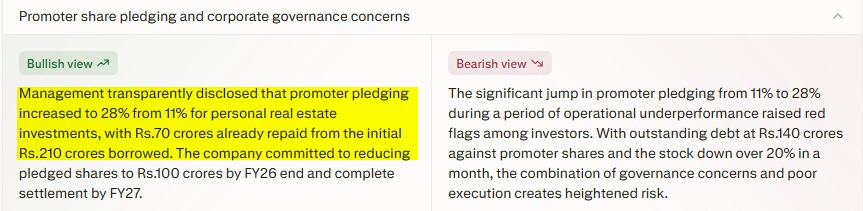
EMS LImited | Pledge Increasing

Thoughts folks ?

2 Likes

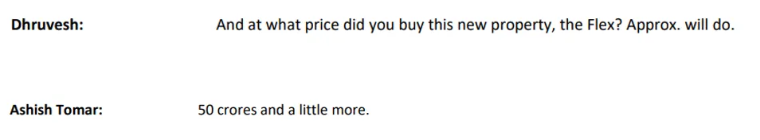
Promotor moving money from their own company to purchase real estate does not go well with market. Disc invested and 60% plus loss at cmp

2 Likes

I am caught up at same loss %. Only positive is orderbook