Hi TD,
Long time investor!
I’ve been here since it was just a baby. Today it’s a 13k teenager.
Looking forward to seeing it turn a centennial.
Keep doing what you’re doing for the co. and this country.
Hi TD,
Long time investor!
I’ve been here since it was just a baby. Today it’s a 13k teenager.
Looking forward to seeing it turn a centennial.
Keep doing what you’re doing for the co. and this country.
this is a very true state of indian players - they have expanded with a lot of prudence and resillence building, cashflows & profitability first be it E2E, ESDS or Yotta all have been very concious of debt led capex.
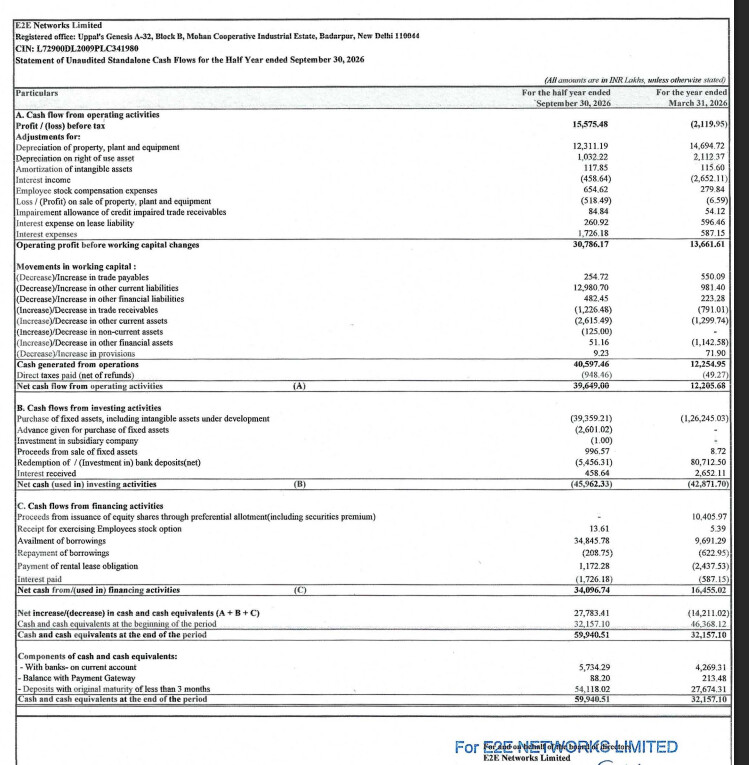
I have highlighted this earlier the correct way to look at E2E is P/CFO. In H1FY27 the company has generated Rs400crs of CFO. If I extrapolate the company will generated Rs 800crs in FY27. At Rs 11,799crs market cap the company trades at 14.7x P/CFO which is super cheap by any stretch of imagination. The GPU is getting depreciated much faster than their economic life and that is inflating the P/E multiple.
tbh everyone is worried of elon’s comments on neoclouds that GPU led lending is facing problems but spacex own revenue today is more from data center than rockets.
so, essentially we should look at real indicators of demand and supply.
Most of the US neo clouds are growing using debt. E2E hardly has a debt problem. We are confusing the trees for the forests
Agreed and well put. The key thing US players have piled on debt to buy the GPUs, the growth is yet to come and it is a circular financing in a way, as and when the interest rate goes up the debt will bite them even more.
i think down the line…only those neoclouds will do well, where there clients stays with them irrespective of fact that, they are able to get cheaper compute elsewhere.
even though for now there looks to be no derth of compute demand for many years, but this i think will remain the biggest anti thesis for any neocloud, any neocloud that is able to have that sort of competitive edge will be able to command a good price multiple.
tracker to track in excel to see whether company has competitive edge and not only has rental business.
E2E_neocloud_tracker.xlsx (21.4 KB)
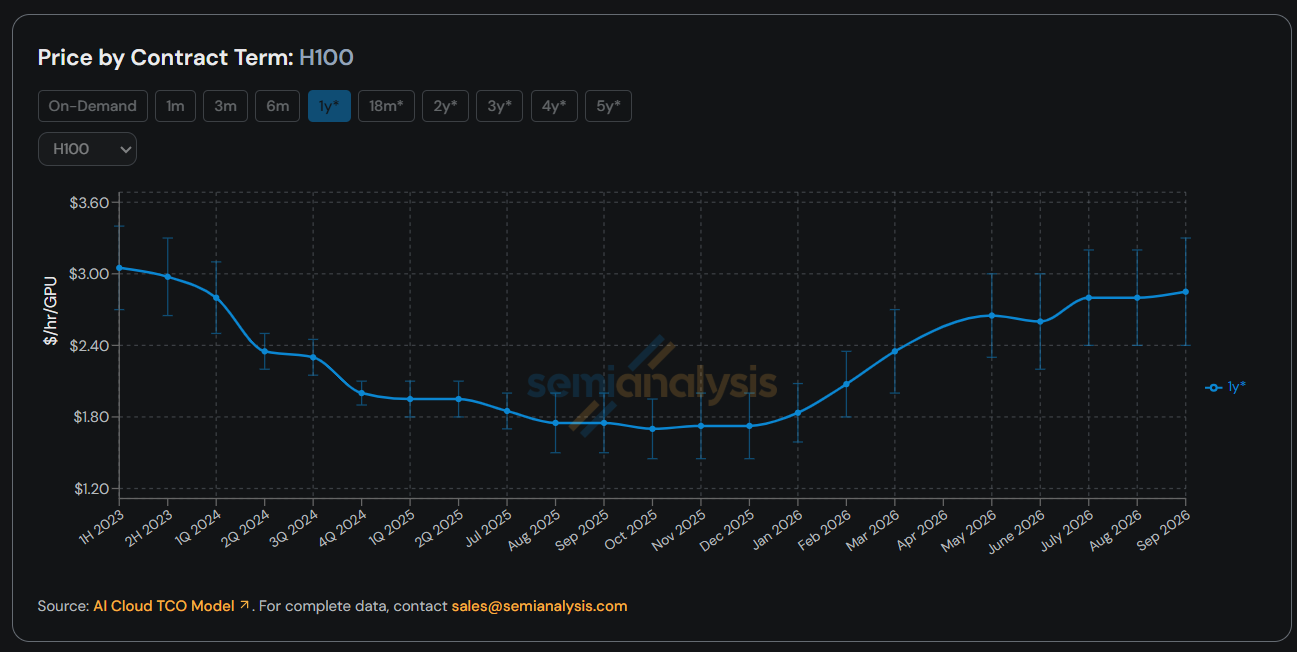
GPUs are depreciating, but their rental prices are going up because of their software optimization of particular chips. And demand is outstripping supply. Some people prefer to use older chips because of their optimization of it and understanding.
GPUs are depreciating, but ai models are improving and software of that model is optimized ,the value created is increased that’s why customers are willing to premium. So, the rental prices are going up. GPUs are the bottleneck. That’s why prices will increase and continue, in my opinion.
In short ai models are getting cheaper and better .
Running ai required gpu’s.Its the bottleneck.
increase in value created per gpu > depreciation per gpu