Dua has said in the previous Q call about considering alternative funding paths. This is possibly to get access to larger sets of GPUs. I’m sure these learnings from Coreweave and other players in the industry are lessons being considered by them.
I’ve also given it some thought about possible better ways to finance the CAPEX but come up empty handed. I am not a finance insider in the industry so definitely not an expert. Large equity dilution for a small company dilutes the current shareholders’ values substantially and financing puts pressure on the profitability and other liquidity ratios. So, I guess its between a rock and hard place.
Hopefully they come up with something.
I just want to know from the management whether in their vision, they see E2E as a mid-large player in a incredibly large AI landscape or a niche player and happy to have their share of the pie and be happy with the growth/limitations that comes with that.
I’d add a slightly different lens on the dilution part.
Dilution isn’t automatically value destruction for existing shareholders. The earlier rounds were raised at much lower valuations, and that capital is precisely what has compounded into the market cap the company carries today. So the raise itself was accretive — the test was never “how many shares got issued” but “what return did the company earn on that money.”
The same logic applies now, If management keeps deploying at the kind of returns they have so far, this round should play out the same way. The risk isn’t dilution — it’s the capital being deployed at returns below what the market is pricing in.
I’d rather own 1% of something ten times the size than 2% of what we have today."
On the vision question: I wouldn’t hold my breath. Anyone tracking the company for a few years knows management has stayed tight-lipped on forward guidance. The most you’ll get is what’s already in the press release — aggressive but judicious capacity expansion. Whether that means mid-large or niche is something you’ll have to infer from future acts.
E2E looks like a goldmine in comparison to CRWV. Cash+, debt well within control and far better growth CAGR. Judicious approach by management by not going overleveradged and the results this qtr have proven the same. Earnings have already compressed the PE and it will further dip with current profit taking going on. I have started nibbling at every fall.
PS: Invested since long, and booked some good profits just before the results.
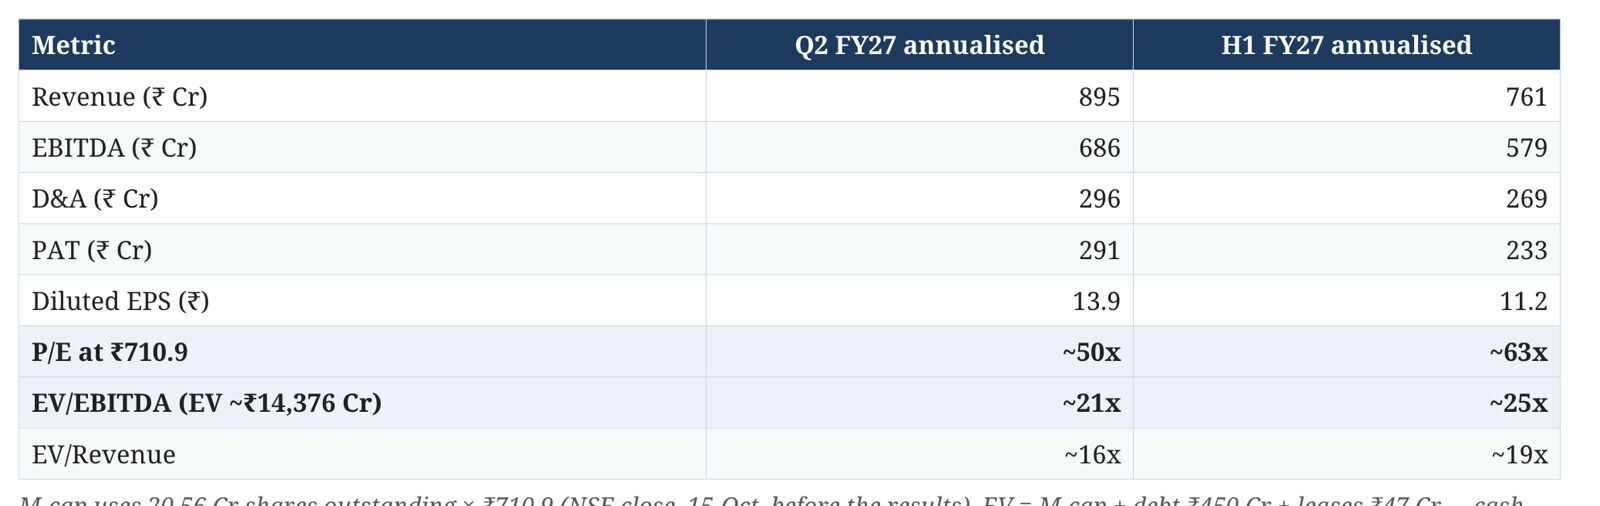
I think we need to look at the company based on its current quarterly run rate, at which the valuation seems fairly reasonable to me. Also, comparing it directly with US neocloud players may not be an apples-to-apples comparison, given the significant leverage these companies operate with.
Another important aspect is the asset base the company currently has. As of now, it has only around 5,000 GPUs, so I believe a forward-looking valuation would be more appropriate to capture its potential as the capacity scales up.
I’ve tried to model multiple scenarios in the attached Excel, which I think could be useful in understanding the forward valuation under different assumptions.
Sharing the Excel for your reference. Would be happy to hear your thoughts and feedback on the assumptions and scenarios.
I didn’t quite understand that demand is there but capital in unavailable. Isn’t that universal truth. Demand for anything desirable is “off the charts” if enough capital is available, e,g, every company would want to own a office in city centre, own chartered planes, do great acquisitions to grow if there was enough capital
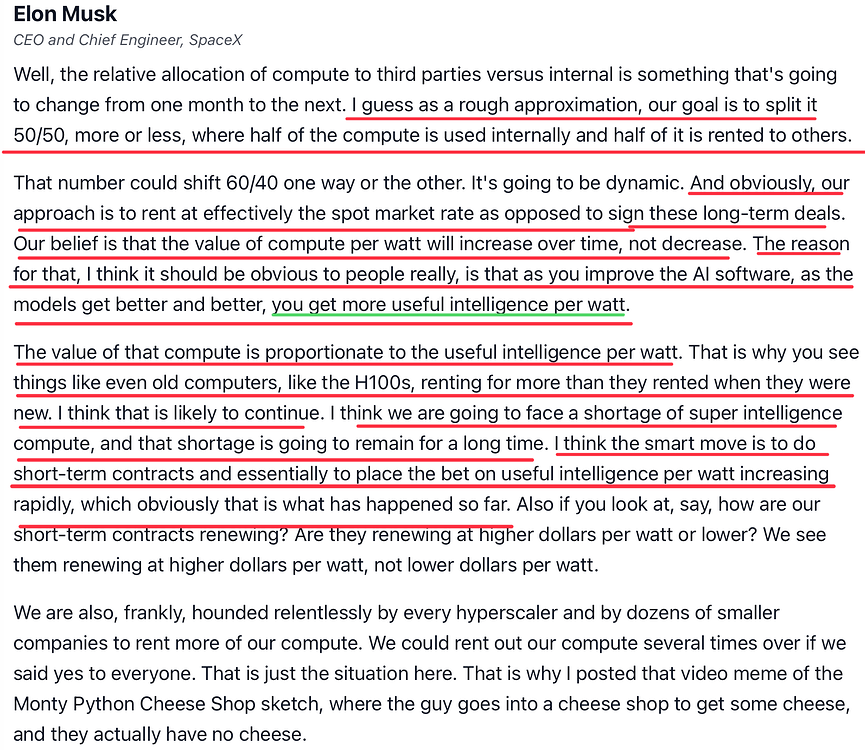
SpaceX CFO: Bret Johnsen: at current pricing, newly deployed compute is paying back in under a year, with pricing now tracking slightly above the top of the $30–50 per watt range they had given a quarter earlier.
there is conflict of interest, but i would rather have some faith in statement given it is coming from a person who is behind the birth of the given industry, everyone have there way to judge statements, i prefer to trust him.
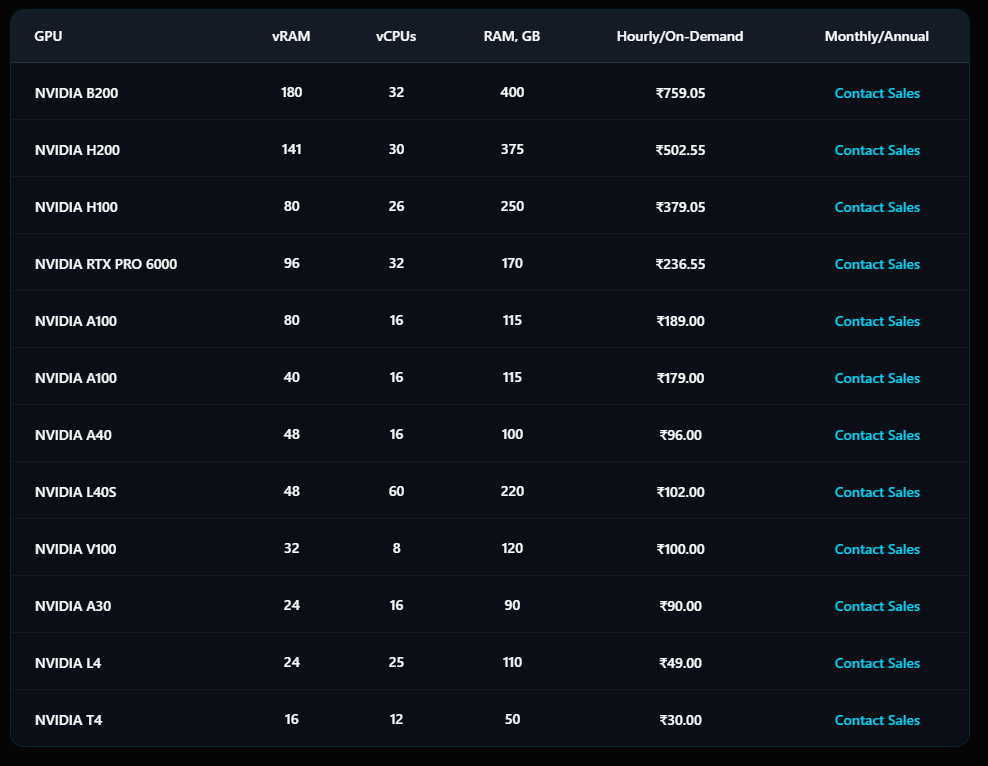
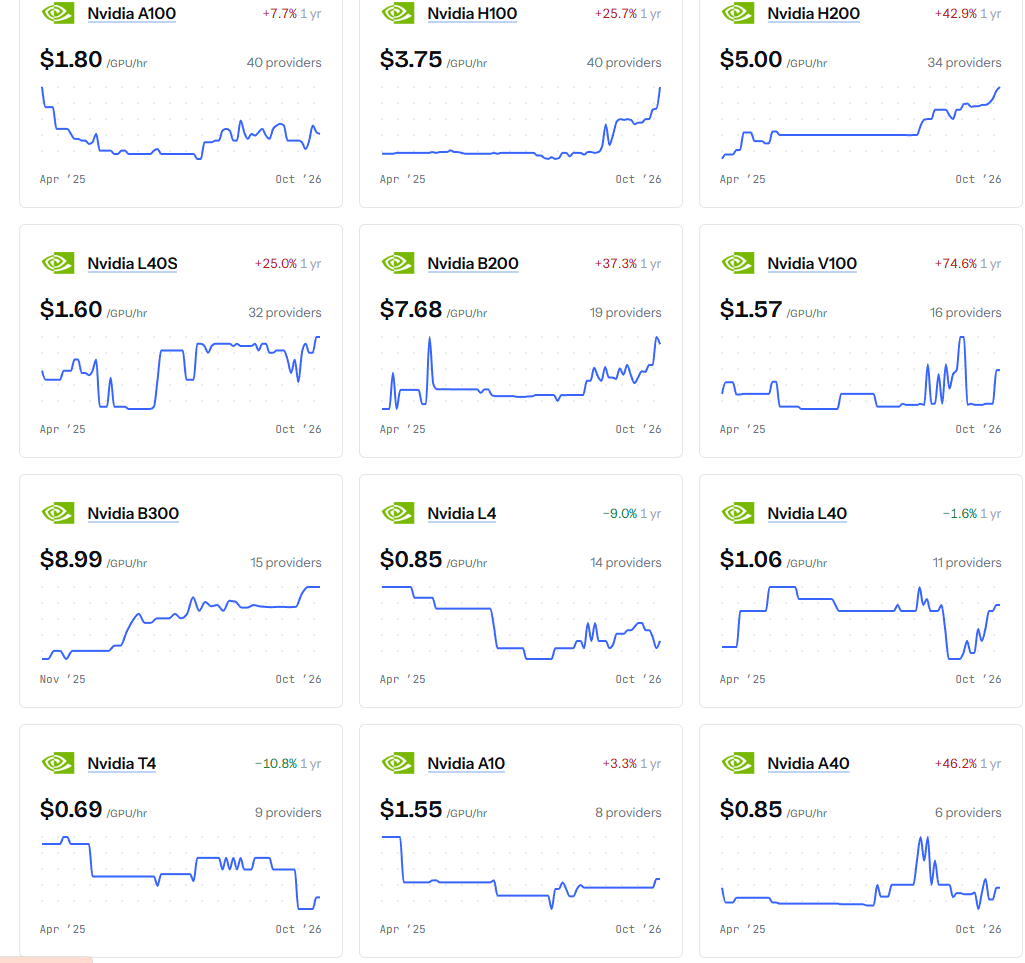
GPU on-demand prices for E2E are higher than the index price.
having said that it seems that most of the capacity is already contracted out. Dont think they have much on-demand capaity to offer.
Watch this for last 4 minutes. Elon says compute payback period can be 6 months by mid next year… Not sure LLM/agents profitable at that rate.. but when Elon says it. You need to listen once . What it means to E2E and its next year earnings..
Discussion is about E2E, the latest sell orders is revealing, what looked like blockbuster numbers apparently has more to it underneath. The way management dodged almost all questions tells me they are unsure about immediate future. They have set high investor expectations. A very appropriate question by analyst on the response they received on their latest California conference outing went unanswered, now here they were not asked for next few qtr growth. What does one take away from it? Did they even see traction on people walking in their stall? All these discussion about compute price increasing, well it might be, but again zooming into E2E , they are clearly saying that they rather retain customer than jacking up prices, so obviously the already rented GPU won’t benefit from current price trend and for new GPUs they don’t plan on aggressive pricing, so the price increase debate tests here. There is no clarity on new capex, whenever that happens will go through more dilution. What baffles me is L&T stayed through with 18% or so stake during most of the base formation part and q1 when E2E reported blockbuster nos stake went down by 2% in September qtr and I won’t be surprised if they are selling even now. For 12 lac odd sell volume buy quantities ranges around 16k. I think market also knows more sovereign contracts means cut throat pricing, so it is not business certainty here, it is being uncertain of renting out full capacity and hence taking hair cut to secure utilisation. Really disappointed with management of dodging all questions.
Now look through past Q calls and tell us which Q they gave remarkably specific answers?
Have you looked at Coreweave or the global GPU markets recently and how their stock price have been faring?
What about the wider India stock market?
I don’t like to to predict/suggest why a stock price moved the way it did. I leave that to Gurus and Traders. Hindsight is 20-20 and I’m neither.
But if you are suggesting E2E’s fundamentals are off, you need a more in-depth view of the business.
I don’t like that management doesn’t give specific answers but you are assuming everything that they know/plan is shared in these calls. If that were true, they went from a 65 crore market to 13000 cr. in 5 years while having no plan at all.
Fair points on separating stock-price movements from business fundamentals. I accept that the sell queue alone cannot establish deterioration in the business, and whether L&T is selling further is speculation.
But the questions about the business remain.
“When has management given specific answers?” If earlier calls also lacked clarity, that establishes a pattern; it doesn’t make the lack of clarity acceptable. As the business scales and capital commitments increase, investors should expect better visibility on utilisation, customer traction and funding.
CoreWeave and global GPU demand provide context. They don’t answer how effectively E2E is converting that demand into contracts, realised pricing and returns on its capacity. Even a strong industry can have very different outcomes for individual companies.
The broader market can explain some of the selling. It cannot answer the operating questions raised on the call. I agree we should avoid attributing every price move to fundamentals. Equally, market weakness cannot be the answer to every company-specific concern.
The California conference question is a good example. Asking what customer response they received is hardly asking for confidential plans or precise quarterly guidance. Some qualitative indication of interest, conversion opportunities or customer requirements would have helped investors assess traction.
Similarly, retaining customers through competitive pricing may be a sensible strategy. But then the bullish argument about rising GPU rental prices needs to explain how much of that benefit E2E can actually capture. Higher industry prices do not automatically translate into higher realisations for E2E.
I am not suggesting management has no plan, or that everything must be disclosed. I am saying investors need enough information to assess the economics of that plan—particularly the balance between utilisation, pricing, fresh capex and funding. Sovereign contracts could provide valuable revenue visibility; what matters is the return earned on the capacity committed.
Finally, the journey from ₹65 crore to ₹13,000 crore deserves recognition, but market-cap appreciation does not validate every future investment decision. You rightly question using a falling share price as evidence against the business; past share-price appreciation deserves the same standard when used in its defence.
My concern is whether the disclosed business outlook supports the expectations investors are carrying today. If you have a deeper business view that addresses these questions, I would welcome it. That would move the discussion forward.

 . What it means to E2E and its next year earnings..