
I think there is a concern on Wholesale book as well as their bulk deposits. Interest income not coming in as compared to loan book growth and wholesale dragging all the margins with no visible advantage. Also some chatter on street is they brought in entire Indusind bank wholesale team and underwriting standards are not top notch plus very low yielding loans.
1 Like
Following up on @Nishit_Shah2’s point about bulk deposits. Went through the Q2 FY27 investor presentation and press release (both filed 23 Oct) and the deposit side has moved the same way again.
Headline numbers look good: deposits +18% YoY to ₹46,889 Cr, advances +22%, PAT +14% to ₹183 Cr. But look at what the deposit growth is made of.
CASA was ₹8,394 Cr in Q2 FY26 and is ₹8,889 Cr now, only +6%. Term deposits went from ₹31,257 Cr to ₹38,000 Cr, +22%. So of roughly ₹7,200 Cr of new deposits in the year, less than ₹500 Cr came as CASA. CASA ratio is down from 21.17% to 18.96% (slide 19). Bulk deposits are now 52% of term deposits vs 46% a year back.
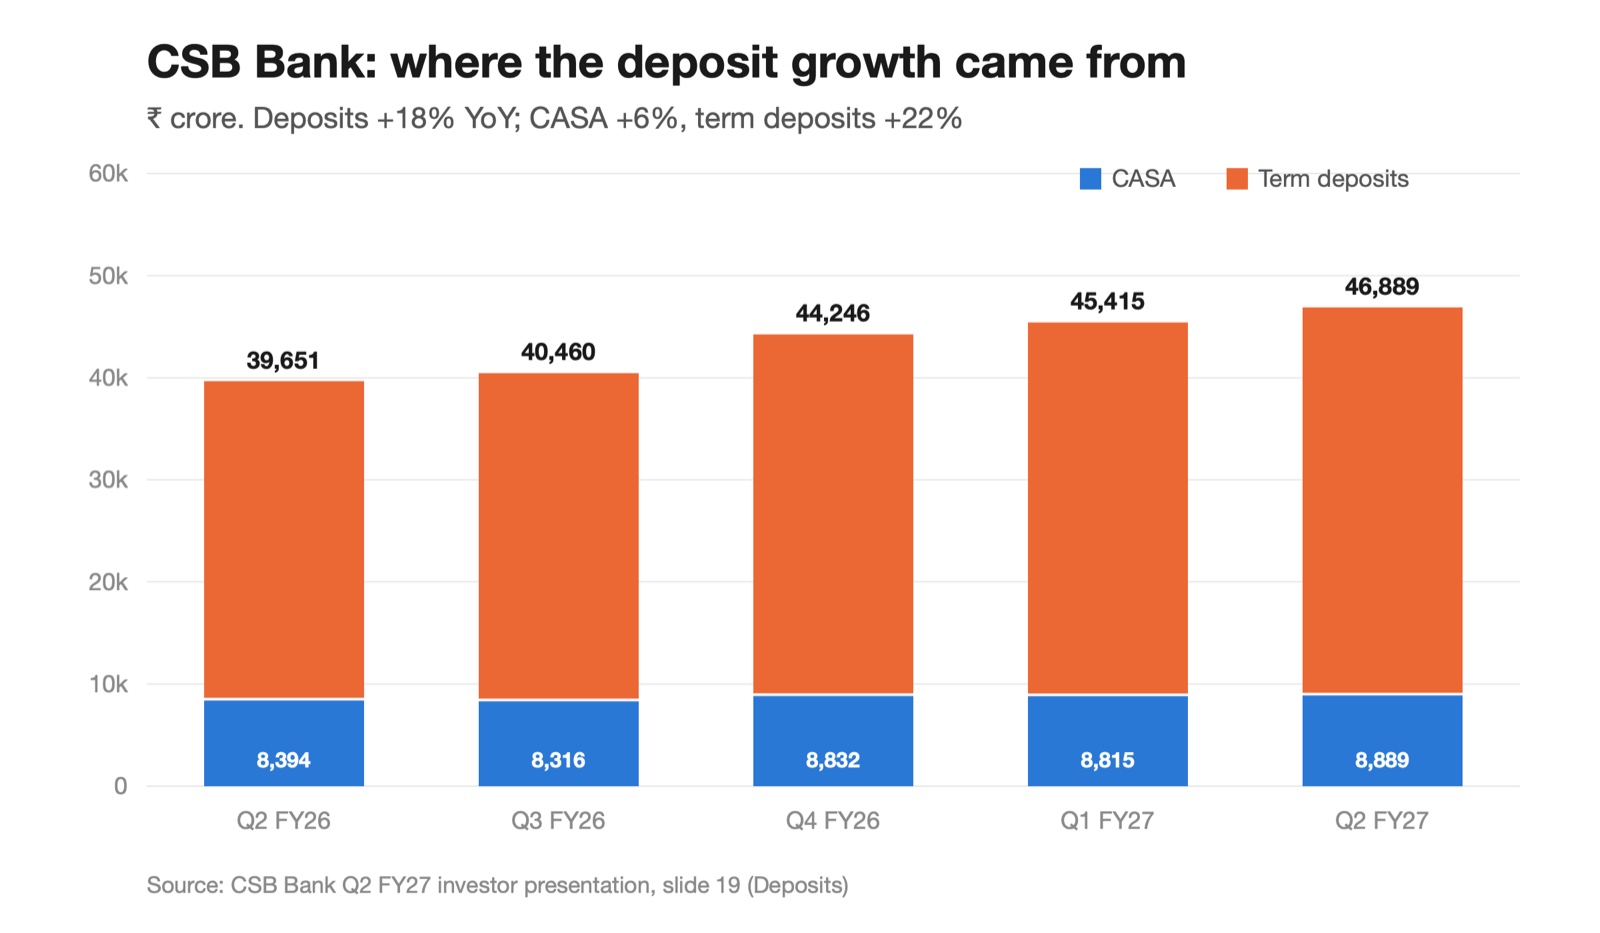
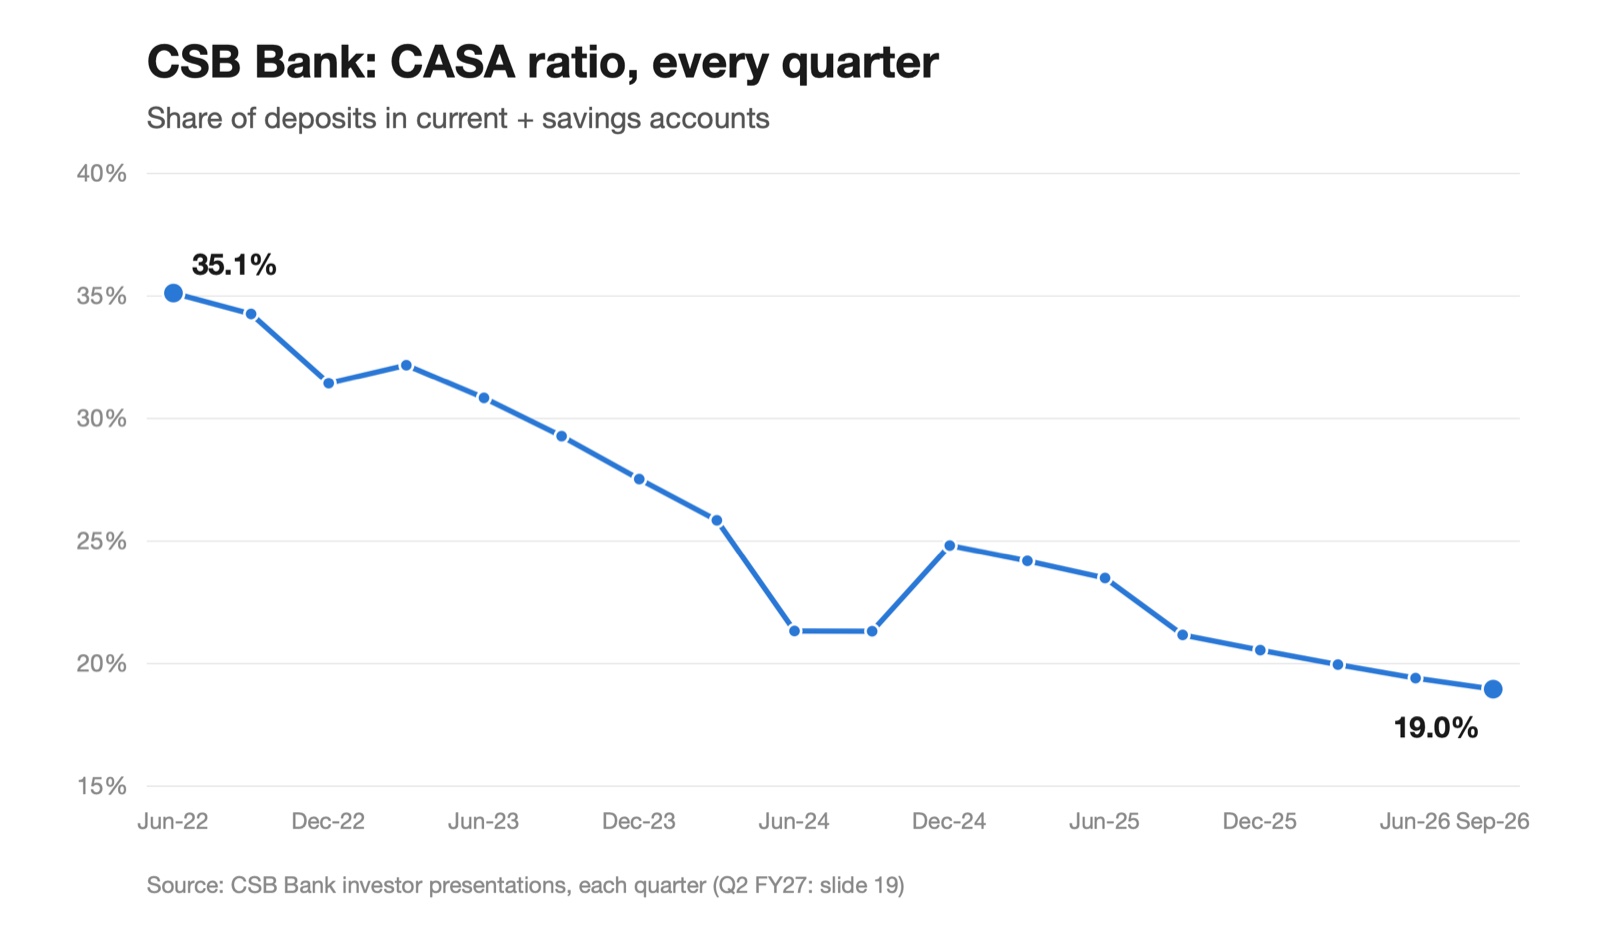
This is not a one-quarter thing. CASA ratio was around 35% in mid-2022 and has come down almost every year since, while total deposits nearly doubled (₹24,506 Cr in FY23 to ₹44,246 Cr in FY26, slide 32).
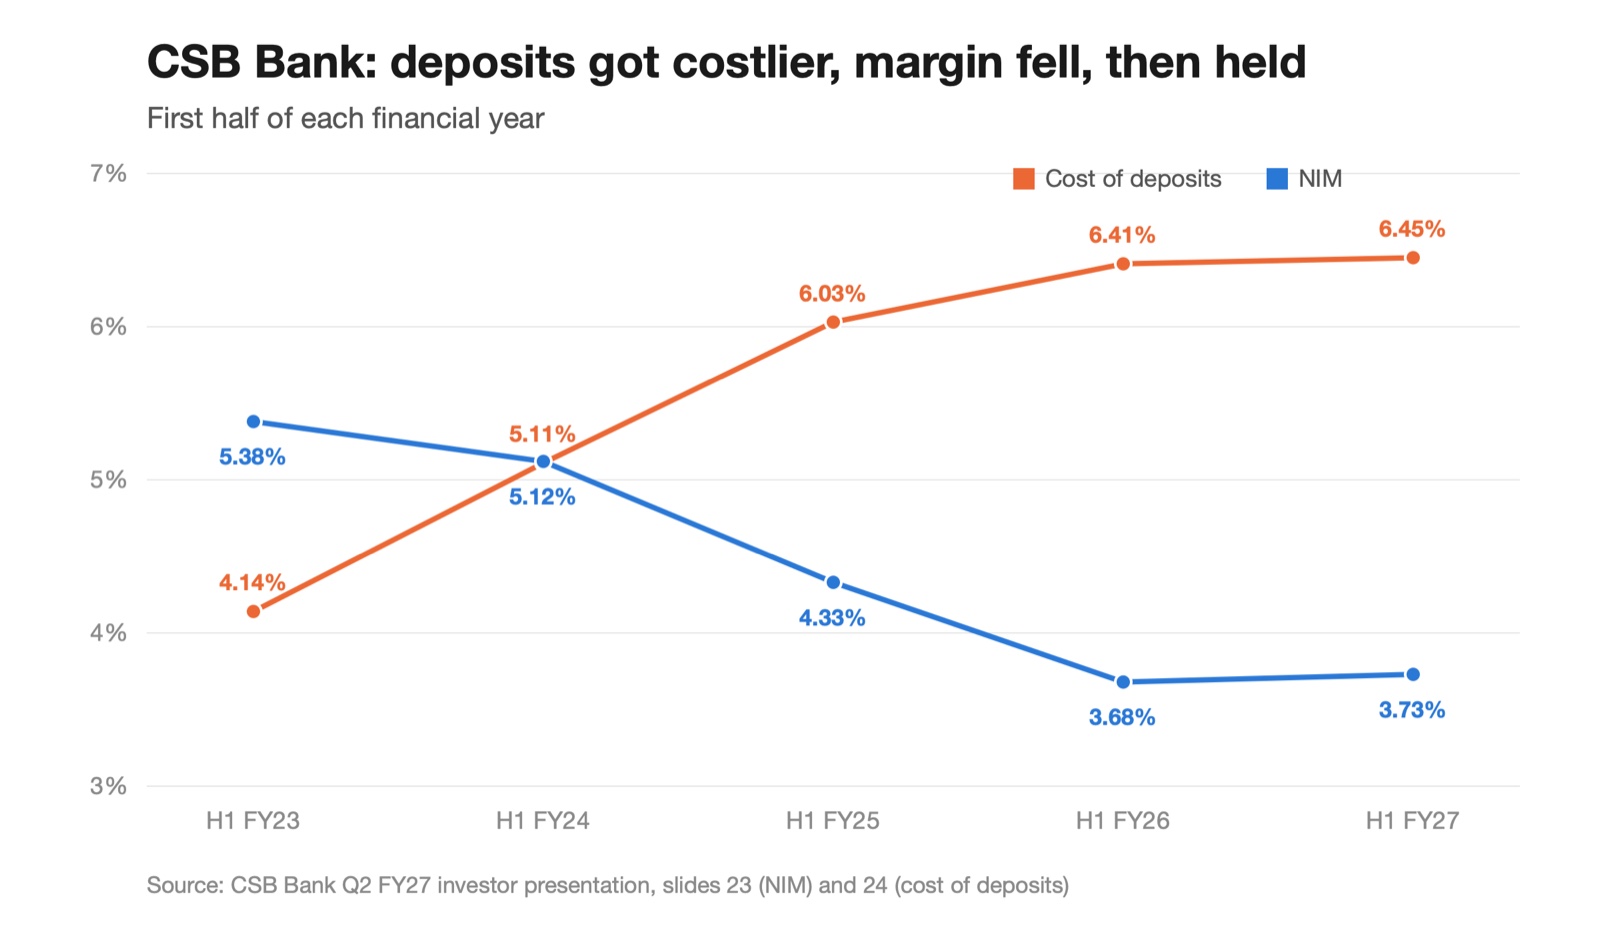
The cost of that shows up clearly. Cost of deposits for H1 went from 4.14% in FY23 to 6.45% in FY27 (slide 24), and full-year NIM fell from 5.48% in FY23 to 3.76% in FY26 (slide 32). ROA went from 2.06% to 1.29% over the same period.
What surprised me is that the margin has actually stopped falling. Q2 NIM is 3.81%, same as Q2 last year, and H1 NIM is 3.73% vs 3.68% (slide 23).
The reason looks like gold. Gold loan yield is 12.33% this quarter (slide 21) and the gold book is up 36% YoY to ₹22,303 Cr, roughly half of the loan book. So in effect the bank is running a high-yield gold book on fairly expensive, rate-sensitive term and bulk money. Works fine while gold yields and demand hold.
For comparison, the other Kerala banks held their CASA much better over the same year. Federal Bank went from 31.01% to 32.04%, and South Indian Bank from 31.86% to 31.55% (their Q2 FY27 press release / presentation). So this does not look like a regional or sector-wide deposit squeeze. It looks CSB-specific.
Few questions for people who follow this closely:
- Did management give any CASA target or say anything about the bulk share on the Q2 call?
- How much of the gold book is benchmark-linked vs fixed? If competition in gold loans picks up or gold prices correct, how fast does that 12.3% come down?
- Is the branch expansion expected to bring CASA back up, and over what time frame?
Not saying this is a red flag yet. Profit growth is fine and the gold engine is clearly working. But funding quality is the thing I would watch most closely from here.