Q4FY26:
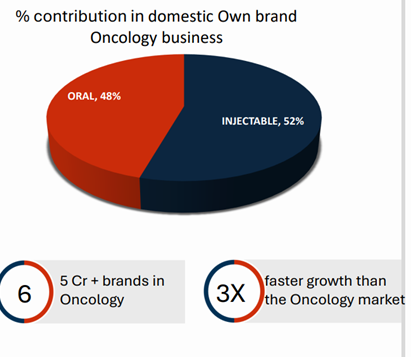
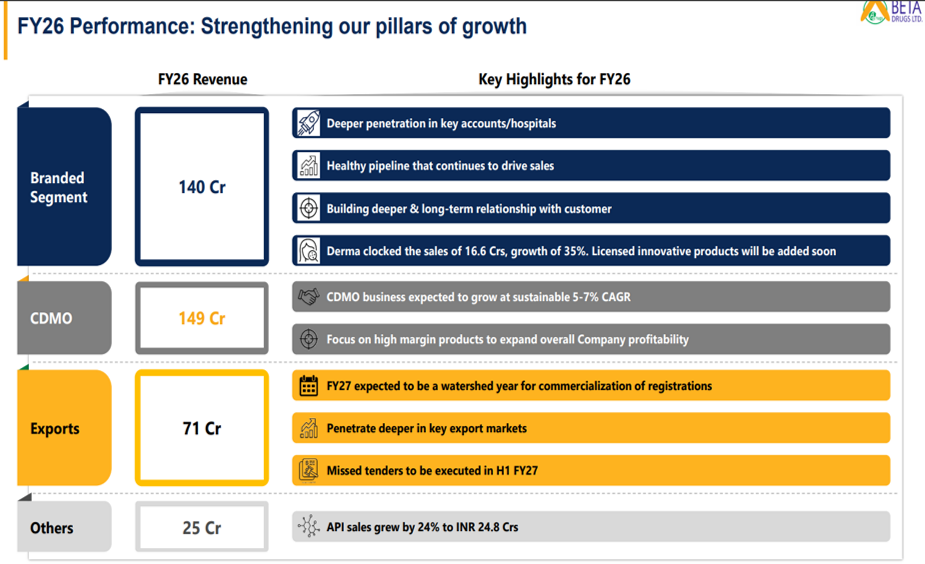
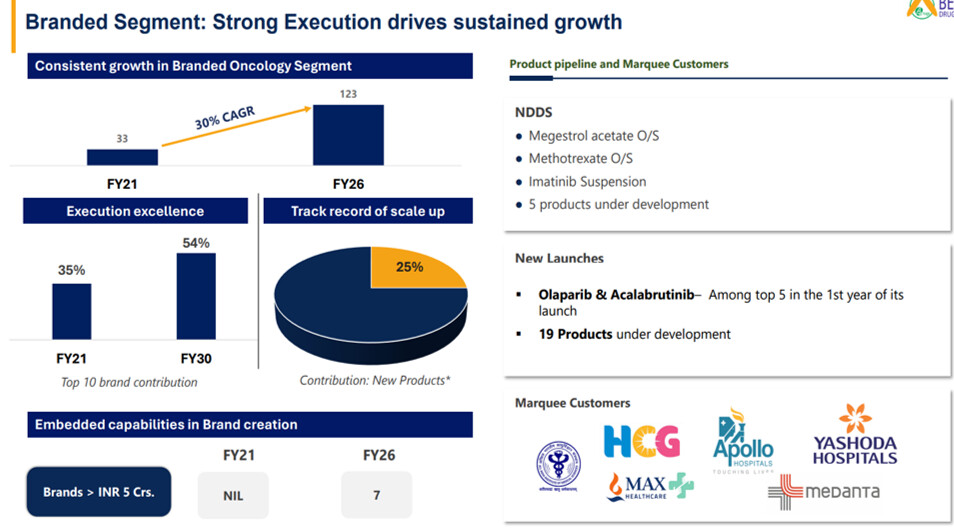
• The Branded oncology business continued to deliver impressive results delivering 20.0% growth. Derma continued to grow at a healthy pace of 34.8% and has recorded break even on monthly basis.
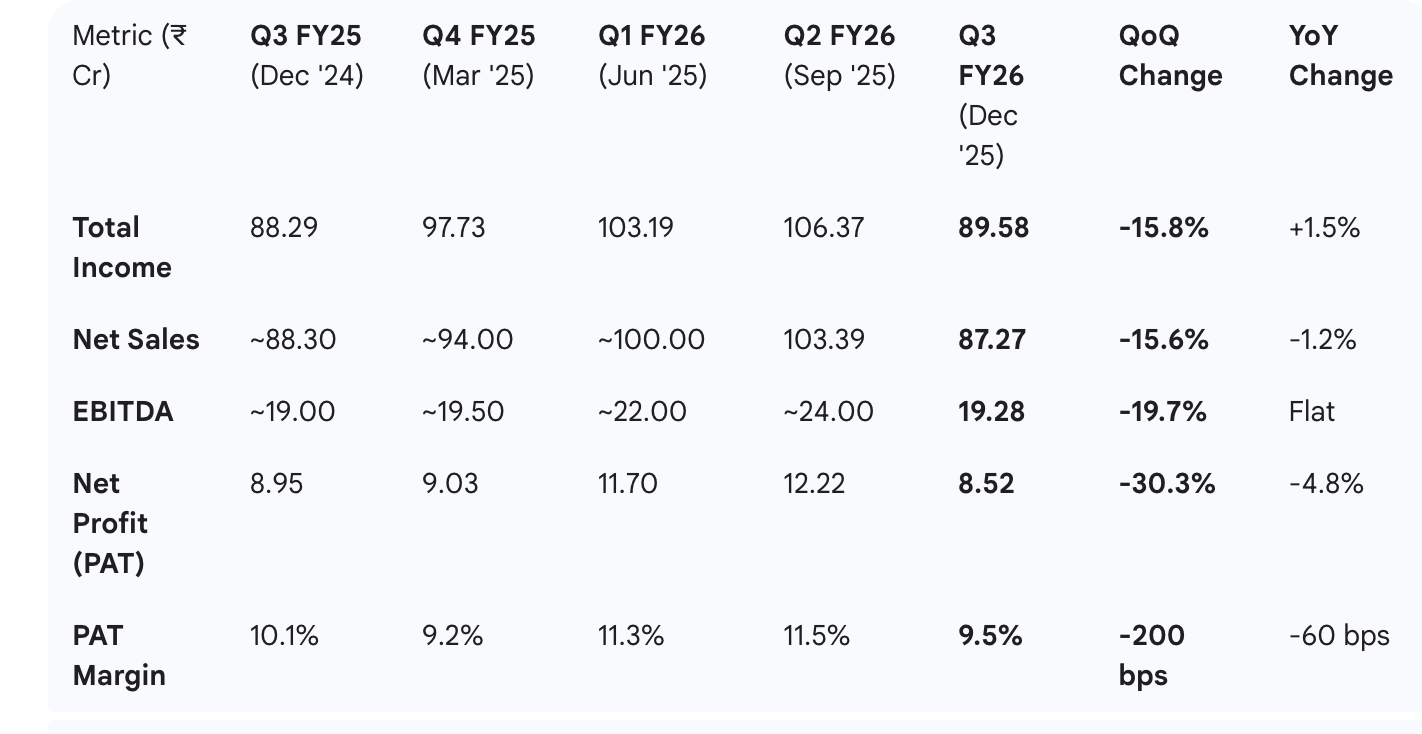
• The drop in Net Profit was on account of higher finance costs associated with CCDs issued in Nov 2024 and which are due for conversion in May 2026.
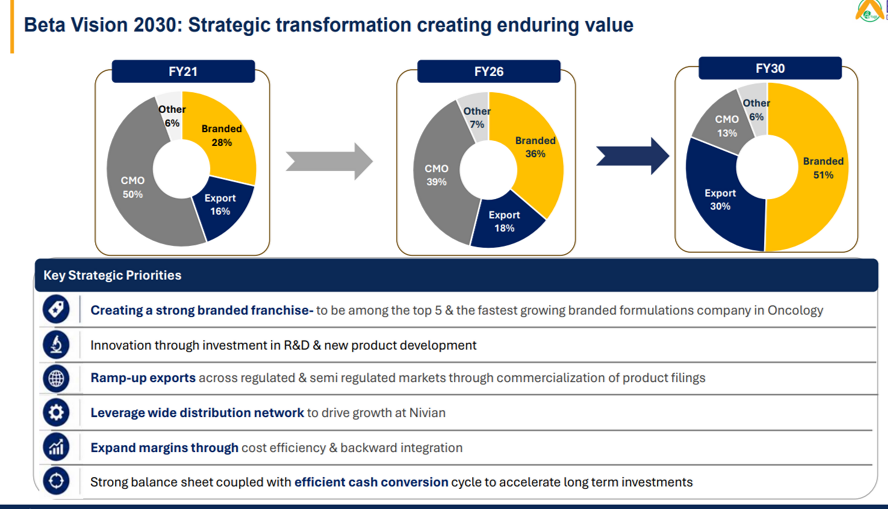
• Beta has set out a vision for 2030 which sets a target for accelerated growth and higher margins. We expect high margin businesses including own branded products and exports to contribute >80% of the total turnover by 2030.
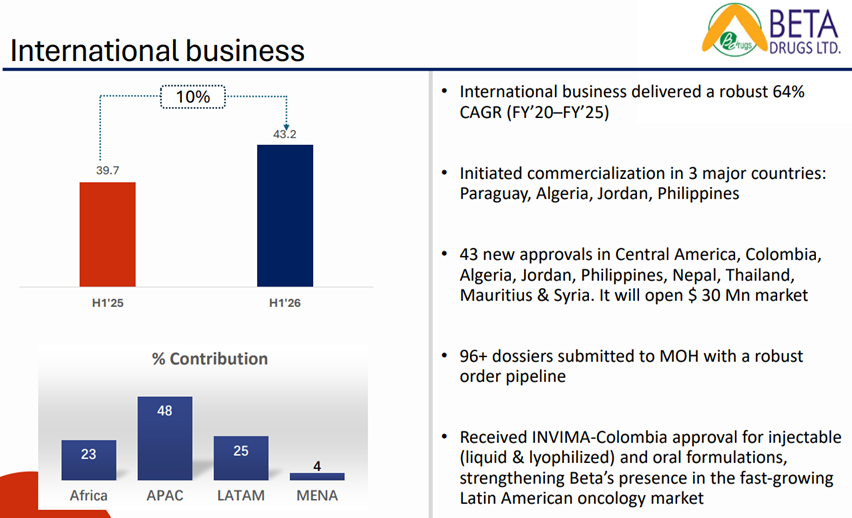
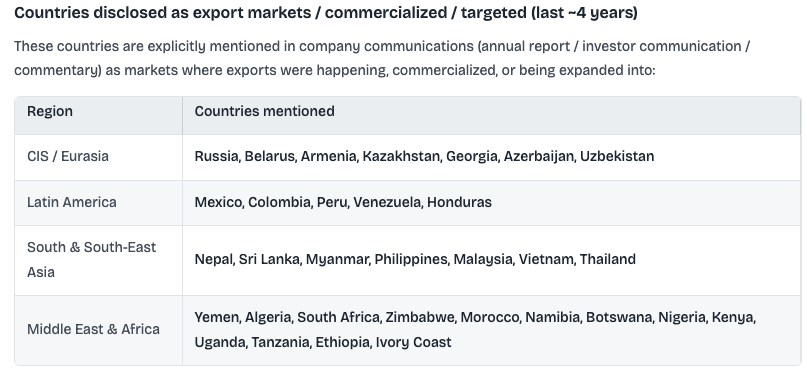
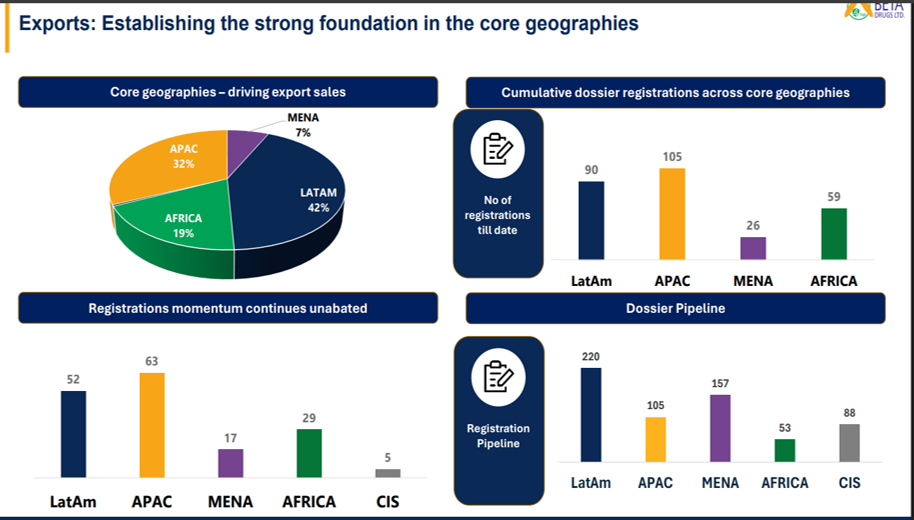
• The momentum in the exports business continues unabated as Beta recorded a total of 166 registrations in key export markets. We have partnered with very strong and influential players for international markets and expect our exports to grow significantly in the medium term.
• Our vision for 2030 is to be a leading formulations company with more than 50% of the turnover coming from own branded products. In this regard, our acquisition of Nivan Lifesciences Private Limited underscores our commitment to expand into complex therapies and reinforce our commitment to be among the leading company in the development, manufacturing and marketing of complex formulations
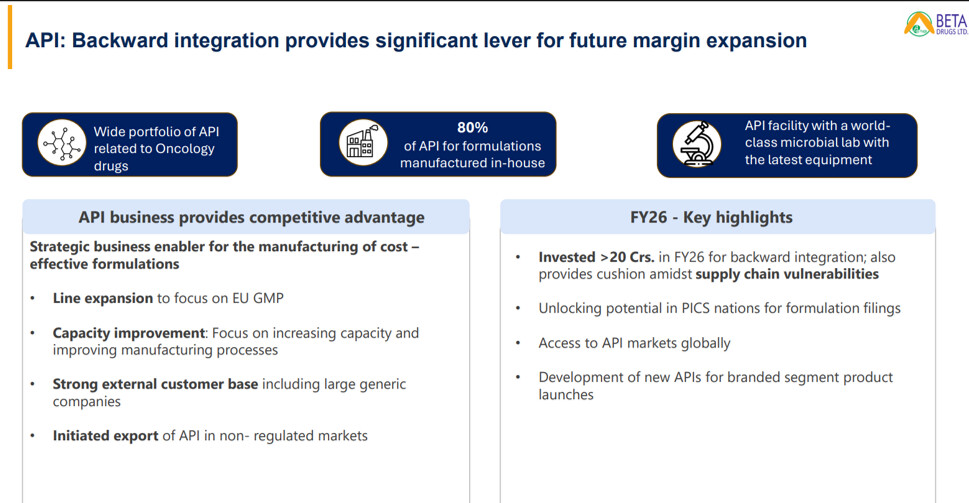
• Given our commitment to high quality manufacturing and strong control on supply chain we have expanded our API facility to backward integrate into key intermediates which will aid in enhancing margins, ensure consistent quality and reduce reliance on third party suppliers. Given the geopolitical conditions and the supply chain vulnerabilities, this provides Beta with tremendous flexibility and ability to protect margins in an increasingly volatile external environment.
• Additionally, the company expects the EU audit of the formulation plant in Q3 of FY27 which will expand multiple end-markets for Beta and provide a long runway for growth for the company.
• Q4 Gross margins improved to 61.6% (Up from 53% yoy)
Q4 Employee cost increased to 20% (up from 16% yoy)
FY Gross margins improved to 56.5% (Up from 52.7% yoy)
Q4 Employee cost increased to 17.7% (up from 9.3% yoy)
An indication of strategic reset and growth investments (Lower margin products stopped and higher hirings in senior roles for expanding operations)
•
•
•
(Big underperformance in exports – Guidance was for 140cr sales. Exports have shown degrowth from 78cr to 71 cr yoy. That’s the main reason for company’s flat performance.
CDMO revenues flat yoy. Platins segment stopped in Q4. That affected sales in CDMO.
Own brands and API have shown solid performance)
•
(5cr+ brands – 7 vs (6 in H1)
•
(70%, 55%,26% and 40% in FY25)
•
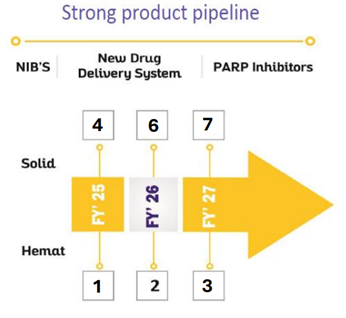
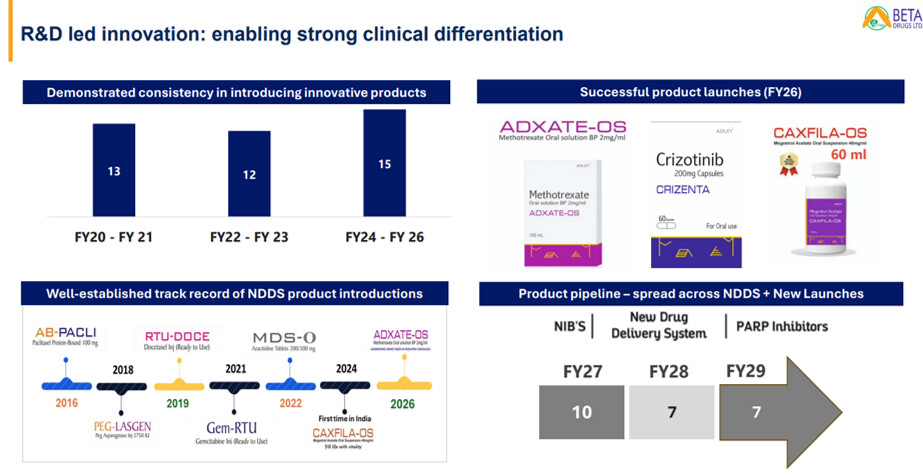
(FY28 – FY29 Product pipeline shared for the first time)
•
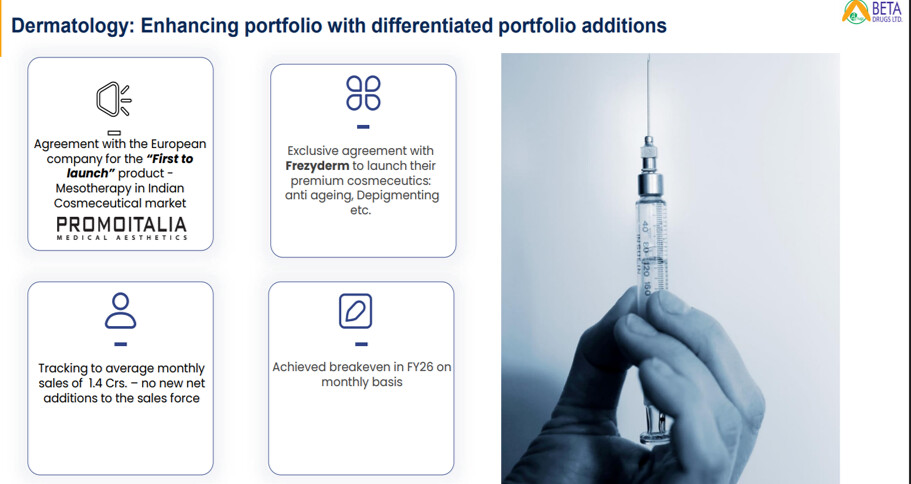
(Frezyderm agreement is new)
•
(Cumulative dossier registrations – 280 vs 230 in FY25. Dossier pipeline – 623 vs 706 in FY25)
• Strategy to shift NDDS products to CMO customers.
•
(80% of API for formulations manufactured in-house (vs 70% in FY25)
•
•
CONCALL NOTES:
• The CDMO sales grew from INR148 crores to INR149 crores, that is by 1%. The only reason of sales impact on CDMO is the Platins, which we didn’t supply in the last half year, which would otherwise have increased the CDMO sales by 7%.
• EXPORTS:
o Export sales have declined by 11%. This is only because the tenders which were supposed to be awarded in FY26 got awarded in March 26. The tenders got delayed by almost four months. We are happy to announce the tenders have been awarded and the supply will be starting from the first quarter of FY27. We are on track to have a growth of more than 50% in exports in FY27. We are expecting to close between INR105cr and INR110cr this year.
o Beta in last one and a half year has submitted more than 200 dossiers and expect new registrations close to 100 this year. We are investing widely on the dossier submission of new molecules in the regulated markets. The human resources in HR department have been significantly added to keep up the pace of dossier submission.
o Exports will contribute 30% of the total revenue by FY30. The results of the growth will start reflecting from Q1 FY27.
o Beta has already submitted three dossiers in EU for EU audit which is scheduled in September first week of this year.
o 200crs export sales by FY28.
o Southeast Asia right now will be the major growth driver for us apart from CIS and few countries in LatAm.
o Revenue impact of missed tender – 20-25cr. This year we don’t expect any such delays.
o Q1 exports will be around 20-22cr (vs 32cr in Q1FY26), but this year Q2 will be much heavier (11cr sales in Q2FY26).
When you are awarded with a tender, you have to supply in two instalments. So, the first instalment is always less, second instalment is always higher. So, the major portion of instalment will come in the second quarter. Like one tender we have supposedly we have been awarded a tender for 3 million. So, the first quarter we might be doing around 1.2 million, but in second quarter we’ll be doing around 1.4 million.
o We are expecting around 30% growth in H1 in exports. As of now we have around 50% of the order in hand and we are also expecting some more new orders.
o Tender details: These are public sector tenders. Actually, globally if you see, except India and some two or three countries except, where there is a share of 50% private market, 50% government market. Otherwise, entire globally, even in Europe also, 90% is government tender business in oncology. Not in oncology, any super specialty. So, it depends on a country to country when they call for a tender. So maybe sometimes in India also it happens. Like in Kerala, if the tender is due in April, they might call tender in – like August. It delays sometimes. So, it depends on a country to country and government to government.
o Export margins: The older margin available till now what we have been supplying is basically the unregulated markets and the little semi-reg markets. So, we were doing around 20%, 21% EBITDA margin in current export. But we expect the EBITDA margins to grow up to 23%, 24%, 25% when we enter the regulated markets.
Right now, our transition is towards the regulated market side. We are developing eight niche molecules; these are first or second generics in many countries. So, we are targeting those molecules to be registered globally.
• NIVIAN ACQUISITION (IVF):
o The promoter of Nivian has not diluted even a single share and will continue to run the business with full enthusiasm along with Beta’s operational efficiencies and bandwidth.
o We can improve Nivian’s gross margin with having better connect in the market as we are present since last four decades.
o We can enable Nivian to sell its product in the corporate hospitals where we have worked in N number of years.
o We can also leverage the manufacturing infrastructure in the near future.
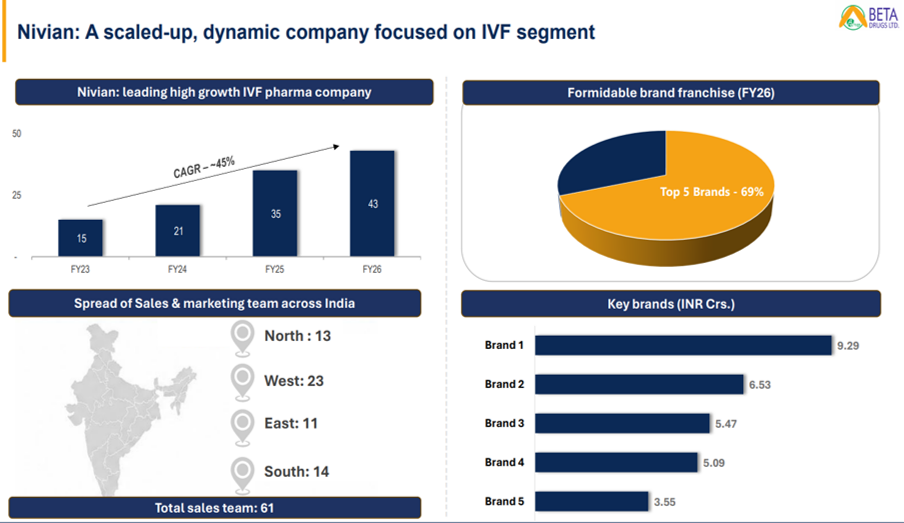
o Nivian will continue to grow at 30% for next three to four years.
o Sales- 45cr, EBITDA margins – 18-19%, PAT margins – 9-10%
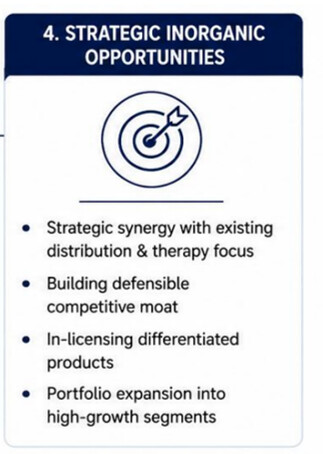
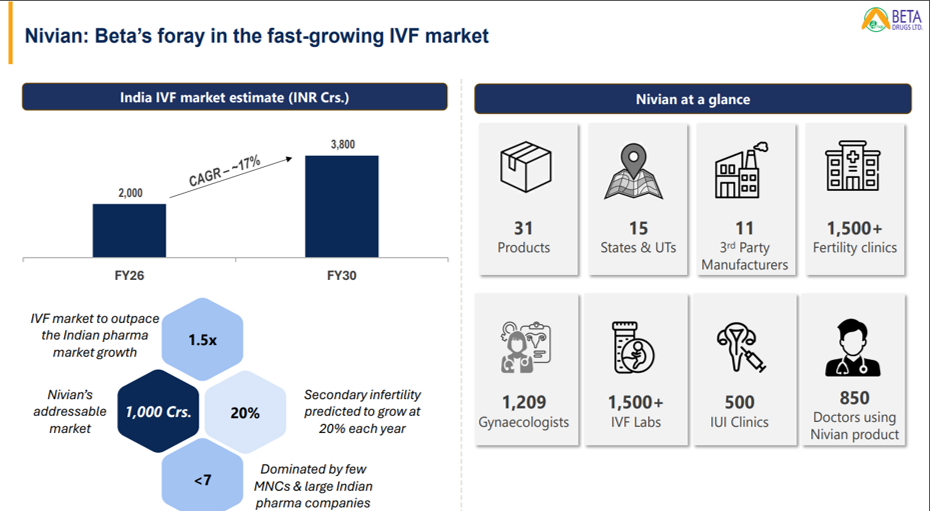
o The total market size is around INR2000 crores. Out of this, INR1,000 crores is a recombinant market wherein we are not present. So, we are planning to tie up with few companies from where we can in-license the recombinants so that we can increase our covered market, point number one.
Point number two is this market is growing at the rate of around 17% CAGR. So, we expect that in next three years’ time the market size will be close around INR3600 crores. So, we even if we continue the same kind of market share of 4.5%, then we will be doubling up our sales as far as infertility business is concerned.
o This financial year we are planning to launch around four new products and then we are also trying to in-license recombinants and there are few more products which is there in the pipeline.
o If you see the overall IVF business, out of 12 to 15 lakh cases which are ideal for IVF, only 3 lakh population is being served. So, there is a big gap in the IVF business. So, we are trying to, you know, tap those things plus the new clinics.
Apart from that, there are gynaecologists who are also practicing IVF. So, we are trying to cover that as well. So, all put together we have increased our coverage which includes the IVF centres, IUI centres plus gynaecologists
o There will be no compromise on the margin side. The business is already scaled up and presence is already there felt across all the hospitals. So, we don’t see any reduction in the EBITDA margins, rather Beta’s synergy will help Nivian to procure goods at a lower price what they are taking from the market.
o Nivian has a lot of benefits. One is the procurement. Till now all the procure products are being procured from outside. They don’t manufacture the product. That is number one. Beta, we are into this business since last four decades, in pharma we are known to everyone. We can get a product at a much-discounted price as Nivian is getting.
o The second synergy we find is that the Nivian right now is totally focused on the IVFs and the standalone clinics. They are not focusing on the corporate hospitals, like we talk about Max, we talk about Medanta. We have a proper access to these hospitals where we can get these products entered and they can scale up the sales there. Also, on the efficiency side, the logistics and the margins which they are diluting, we can play a major role in adding up on those side as well.
• OWN BRANDS BUSINESS:
o The branded oncology business has shown a growth of 20% as compared to last year in spite of all challenges faced of non-supply of Platins. We are happy to announce that our one brand has touched almost INR10 crores of sales last year.
o New NDDS Launches: One new NDDS will be launched in next 2 months. And one NDDS we have just got a BE approval, so we’ll be starting the bioequivalence very soon with CDSCO and will be submitting that report by November. And maybe in after this year, maybe by January/February we should get the approval of that product.
o Megestrol acetate NDDS has given a brilliant revenue last year. It had become the number one brand.
• CDMO: We have also shifted our high margin products to the CDMO partners where we are adding more and more molecules with our existing partners. This move of company will make more towards the growth of this vertical and will continue to make it 5% to 6% annual growth for next three-four years.
• INTERMEDIATES FACILITY:
o With the new intermediate facility, the API business will get a big boost and dependency on the import of key KSMs will reduce significantly as all the KSMs will be manufactured in-house. The development has already started and we will make it commercialized by this year.
o Margin improvements: What our workings have shown from the R&D for first 12 products, there will be a slight increase in the margins by 1 to 1.5%, but till the time API is not commercialized we cannot say because it depends totally depends on the yield when you are getting it.
o The main idea about it is that you have to have a proper control of the DMFs. When you are filing the dossiers, the DMF plays an important role. So right now, our main KSMs come from China. So, the documentation support becomes sometimes very difficult to get it from there. You have to send people and you have to get the QP audits done. So, in that case we are just making everything in-house and we don’t want to be dependent on anyone.
o Internal consumption vs external sales: Because we have come up with a good capacity, so there are companies who have approached us, those products which they are also taking from out from China, they also want those intermediate from India only. So, we might be exploring that potential and that market as well.
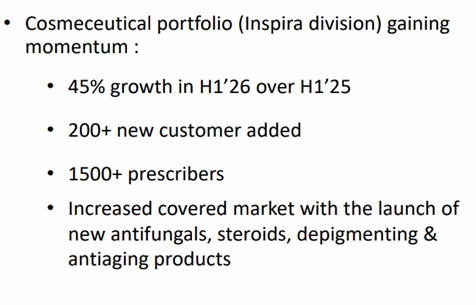
• COSMETOLOGY:
o The cosmetology and dermatology market is growing at a CAGR of 14% annually. Our current covered market is between INR3500 to INR4000 crores.
o We have achieved a PCPM of INR1.85 lakhs with 69 TMs on board and will grow up to INR2.3 to INR2.4 lakhs PCPM this year.
o The next three-to-four-years, cosmetic division will continue to grow at 30% to 40% annually.
o There have been recently launched fillers with exclusive tie-up with a European company.
o In April we got approvals to market mesotherapy in India exclusively from Europe.
o We have also tied up exclusively to market innovative cosmetology products in India where Beta is in process to register more than eight products from Europe.
o EBITDA basis we have already been positive since last 6 months.
o Dermatology this year we are expecting to grow by around 50%.
o Next three years we have a vision to cross INR50 crores in Derma in which the major thrust will be into cosmetology only, not into medical dermatology.
o And as far as margins are concerned, definitely the margins will improve because we are not increasing the field force. We will be increasing the sales, we will be increasing the PCPM, but not the field force. So, margins will definitely improve. So, what we are anticipating is that the EBITDA margins will be close to 12% to 14% if we are close to sales of INR50 crores to INR60 crores.
• We accept that the growth expected last year was not at all encouraging for the entire company. For last six months we have made different strategies to overcome the challenges.
• FY27 GUIDANCE: 20-25% growth along with 23-24% EBITDA margins (including other income) (guidance includes Nivian also)
• Vision of 900crs sales by 2030
• Segment-wise EBITDA margins:
o Branded – 35-36%
o CDMO – 17-18%
o Exports – 20-21%
o API – 21%
o Derma – Gross margins of 57-58%
• Last year Derma margins were 65%. The decline is there because of some schemes we have to give. That’s why the margin has reduced.
• Capacity utilization details: Oral its around 40%, 45% we are consuming till now. Injectable liquid we have an idle capacity for around 35%, 40%. In Lyo, yes, we do have capacity like we are using around 85%. But we have a lot of space in existing formulation plant, so we are planning to install two more Lyo’s there. So, the capacity will not be any constraint for any future growth.
(decent amount of operating leverage still present at capacity levels)
• With current asset base, we can easily scale upto 700-800crs without new capex.
• CAPEX PLANS: See, last year we invested close to around INR45 crores in all the three plants together in which there was a land which we bought and we were planning to open a R&D office and corporate office together, but we have just dropped that plan. We have just taken a building adjacent to our office only so that become a big office now. So, we are just planning to dispose that land since already the R&D setup will be there.
So, capex plan if we see totally for next 2 years, we don’t see any major capex happening apart from what we have done for the intermediate plant where we have already bought an existing plant for INR9 crores and we have invested close to around INR15 crores to INR17 crores for the intermediate plant. Otherwise, total capex we see that is not more than INR25 crores in next 2 years.
• Finance cost will see dramatic reduction since debentures have been converted in May 2026. (only March-April finance cost will be there)
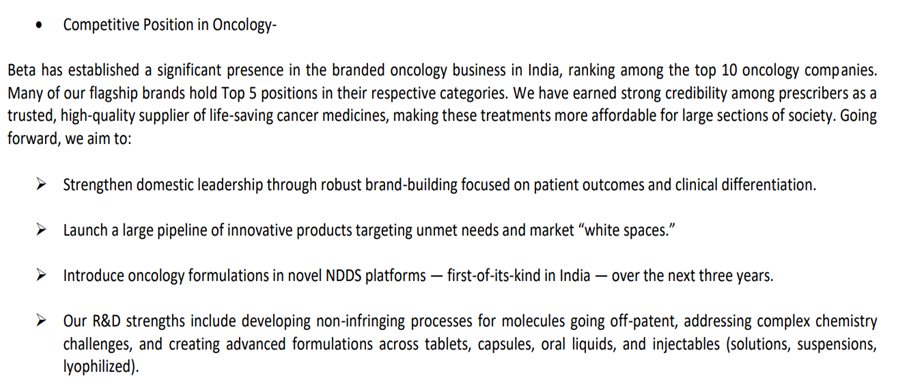
• Oncology business will never slow down. You have seen how many cases are being diagnosed every year and it’s globally. It’s not only in India, its globally patients are being increased further who are suffering from cancer. So, this business is never going to be in a slowdown.
• DIVERSIFICATION RATIONALE: We are always aim at like having some more super specialty in the basket. A pharma company is a company where it has to have multiple segments.
Isn’t it too much of a diversification or dilution? Though you’re saying those are specialized line of businesses, do you see them growing significantly over the next few years?
Management: See, I’ll tell you, it’s about bandwidth. Once you are doing certain business, the business become on auto mode where you as a person sitting there, if you are sincere thinking on a strategic point of view, so you don’t have work to do. You have selected the product which has to be developed by R&D, you have selected the product which need to be registered in those countries, you have selected the product where RA has to work and give the dossiers on time, then there is nothing new left. So, it’s about bandwidth. When you have opportunities, why not utilize that bandwidth and become a better and more diversified company.
• Reason for delay in EU GMP: EU GMP what happened was we were supposed to get an audit in April. But exactly what happened, the new rule has come where earlier there was a line inspection, that the auditors come and used to inspect the line. The dossier was not to be filed mean you need not to file a dossier at that time. But as per the new rule, you have to file a dossier first. So, we have already filed three dossiers and now based on the dossier base they will be coming for an inspection. So that’s a new rule which has come in place in February-March, so that’s why our audit got delayed.
• For all the three divisions we have a separate team, separate managers, separate GMs who will be focusing on this particular segments.
• PLATINS ISSUE: We used to do around INR30, INR35 crores business from Platins only. Not only we, the entire industry, the entire oncology treatment depends on Platen. Today doctors, hospitals, they are starving for Carboplatin.
The chemotherapy starts from Carboplatin. But unfortunately, in India, the Carboplatin NPPA price is INR2850 and the costings which company are getting with Carboplatin is around INR2300, INR2400 as on today. So, there are no margins for hospitals. You have to give 20% to the retailer, 10% to the wholesaler. So, these are things which are beyond control, right? But now in last quarter we laid down certain strategies where we could manage to get 10% growth as compared to quarter of December. That was less of Platens.
So last quarter we just managed to do a very little business of Platens because there are some export orders where we could get margins where there was not a NPPA blockage, where there is no price blockage. So, export there is no MRP. We supplied certain products there, but in domestic we didn’t do any supplies either for CDMO or for own brands also.
(UPDATE: NPPA has approved a 50% hike in carboplatin and cisplatin injections due to severe shortage in hospitals. So platins sales may recover in FY27 for BETA.)
THINGS TO TRACK
• EXPORTS DIVISION PROGRESS: Will sales bounce back as guided? Track progress in terms of Dossiers filed and approvals received and products launched and sales started in newer geographies.
• COSMETOLOGY PERFORMANCE: What would be the impact of Italian company products on overall cosmetology sales? How would margins shape up?
• DOMESTIC BRANDED DIVISION PROGRESS: In terms of sales, prescribers and hospitals covered. And products launched.
• API DIVISION PROGRESS: In terms of new products commercialized and new products developed and External sales growth.
• IVF SEGMENT PROGRESS: As this is a new space for the company, can it successfully achieve synergies and growth targets set by the management?
• INTERMEDIATE PLANT PROGRESS: Can they successfully commission it on time? What impact will it have on margins? How many Product launches?
• BIOSIMILARS PROGRESS
• PLATINS PRICE HIKE IMPACT: Will they begin selling platins again? How much sales and at what margins?