Beta Drugs Limited

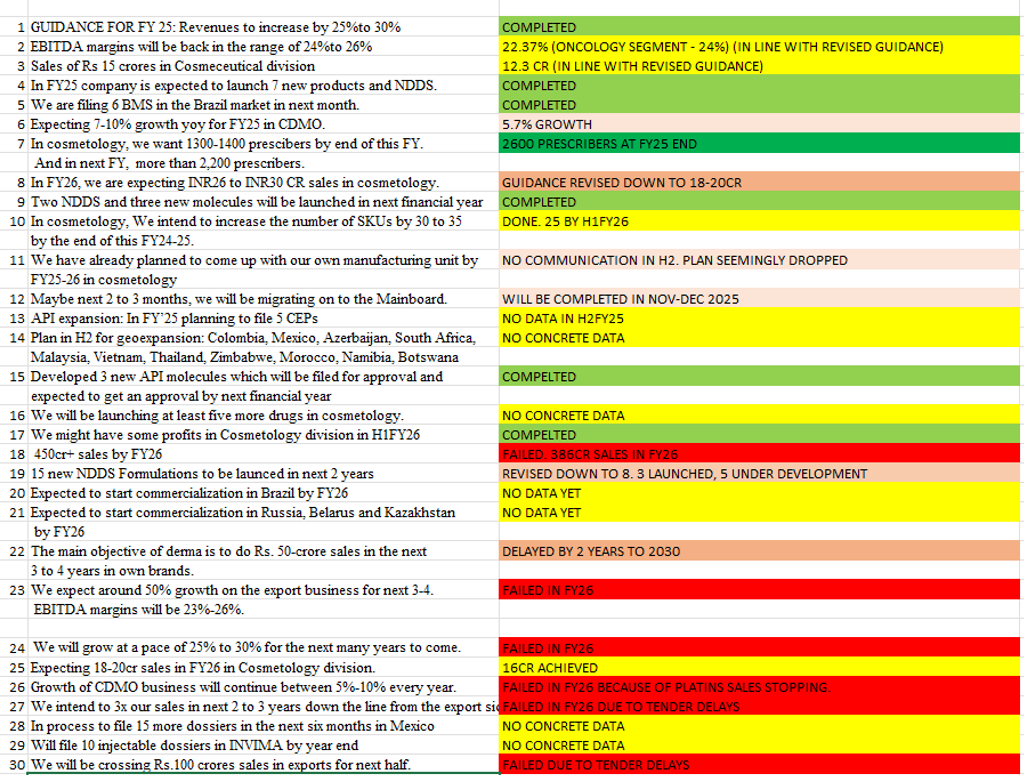
Monitarables tracker for Beta Drugs. As one can see, execution has been poor for last 1 and a half years for various reasons. (Platins-tender delays-facility audits-floods etc.)

But i feel the worst is behind now and going forward all growth engines should fire.

Platins price hike by 50% will be another big boost to sales number.(Management guidance of 20-25% sales growth was without platins segment)

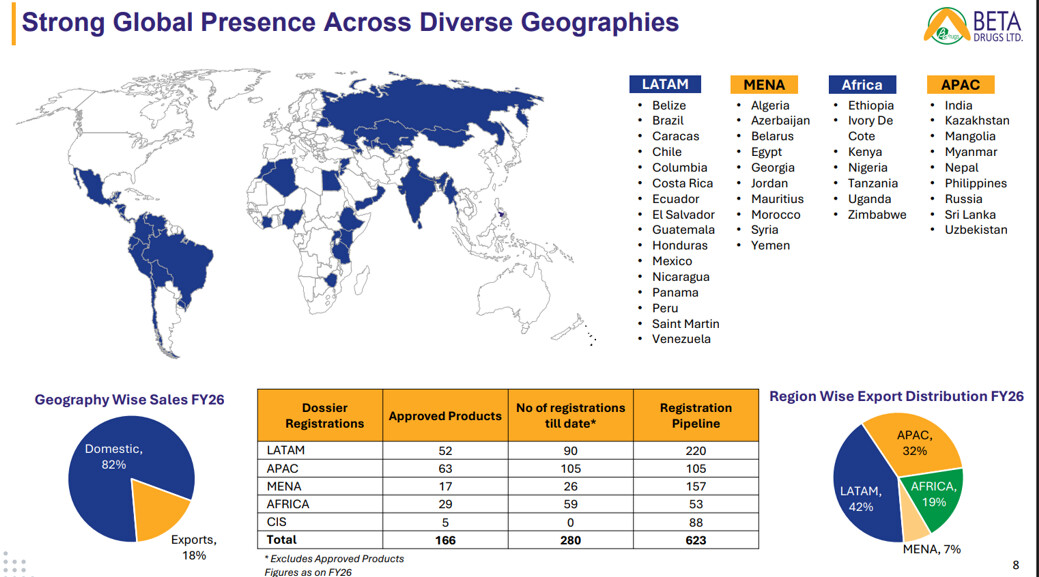
Exports groundwork has been laid with registrations. Big increase in manpower costs in last 1-2 years for exports and derma has built up operating leverage in numbers and the results of that should now come to fruition.

Re-rating recently from 1000 to 1800 has been explosive and i think it confirms my thought that execution issues are behind now (though one can never be sure about market movements)

The business fundaments are rock solid with clean balance sheet (debentures converted in May), multiple high speciality growth drivers (Nivian acquisition looks very smart) and a very long runway for growth.

Current valuation reflect all that promise i feel.

DISCLOSURE: INVESTED. One of my core holdings

4 Likes

Very detailed breakdown of value chain and good insights over Beta Drugs and Sakar Healthcare.

Worth reading.

2 Likes

Q1FY27:

• Gross margins 56.6% in Q1FY27 v/s 50.4% in Q1FY26.

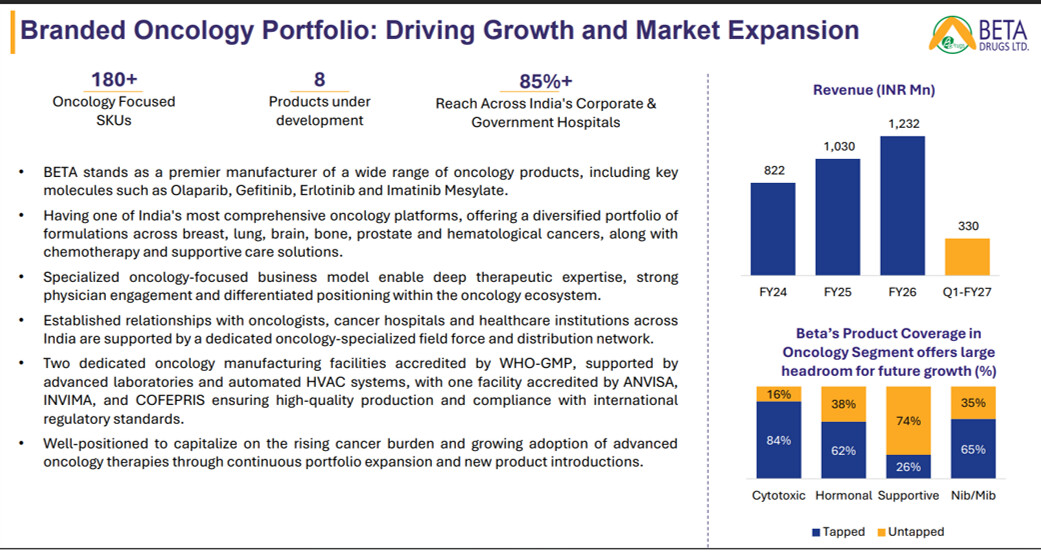
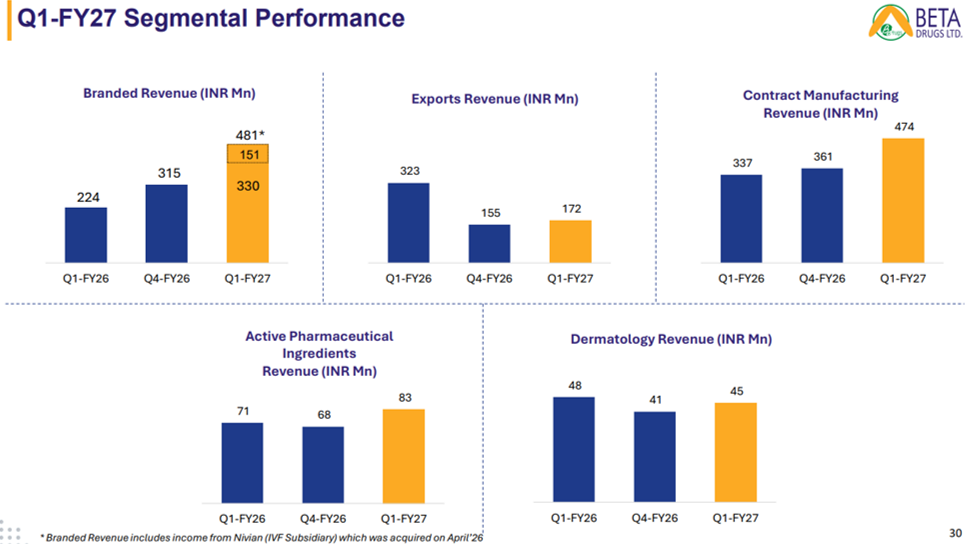
• Branded oncology: Growth of 47% y-o-y recording sales of INR 33.0 Crores. The growth was on the back of improved performance from existing products and increasing acceptance of our new launches last year.

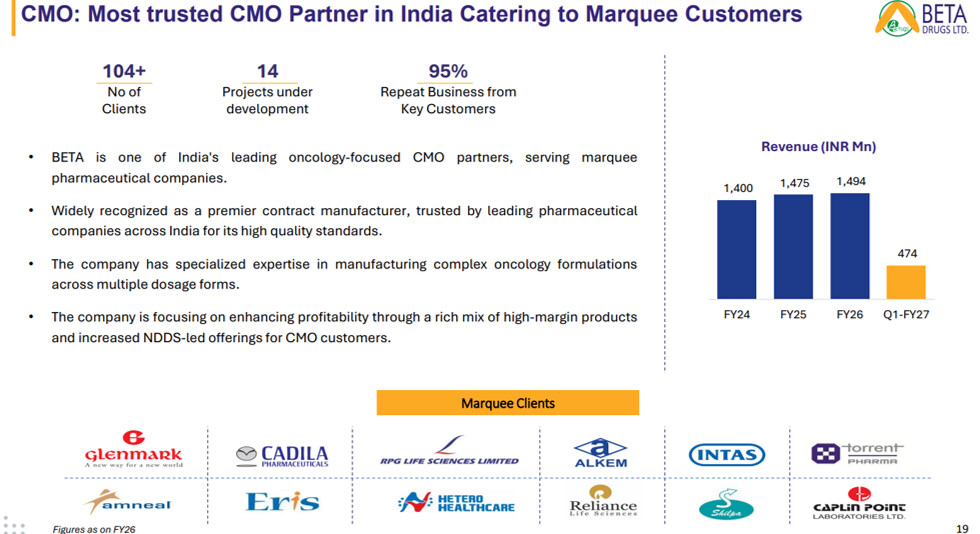
• CMO: Grew by 41% y-o-y on the back of strong traction with our customers and new launches including our proprietary NDDS products in CMO segment. With higher realisations in platins going forward, we expect this business to deliver better performance in FY27.

• Exports: Our exports business delivered INR 17.2 Crores in Q1FY27. The business is expected to record a higher growth for the remainder of FY27 as the orders have started to accelerate.

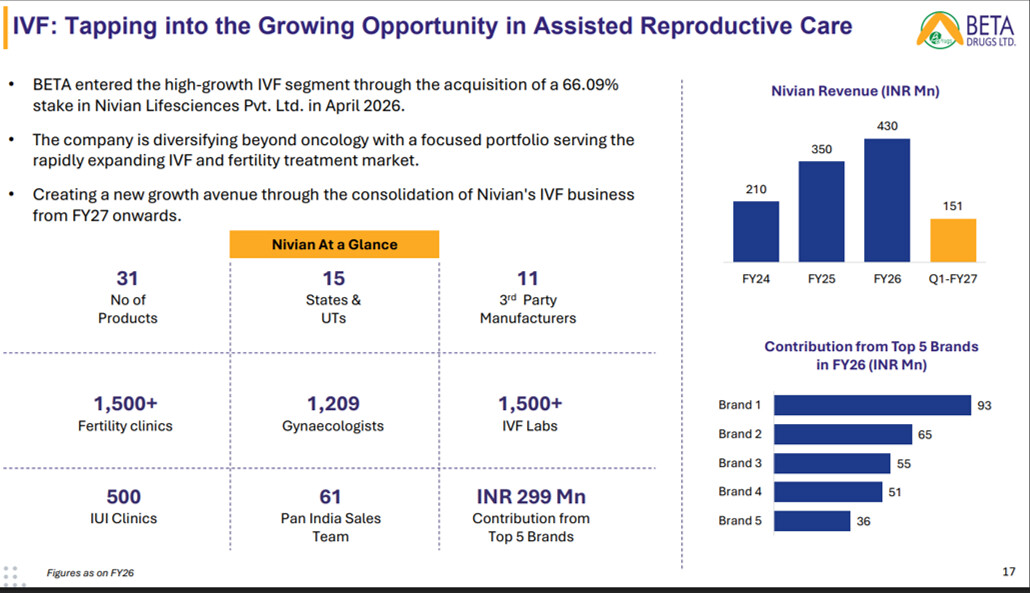
• Nivian: Nivian delivered a growth of 45% y-o-y. The higher growth stems from increased penetration and full quarter performance of new products launched in the last quarter of FY26.

• Net of Nivian, Beta delivered EBITDA growth of 24.5% y-o-y.

• Improved margins are driven by higher Gross Margins (56.6% in Q1FY27 v/s 50.4% in Q1FY26) on account of change in sales mix towards branded businesses including Nivian. This improvement in EBITDA margins is expected to continue as the business mix moves favourably towards higher contributions from branded and exports.

• The interest cost associated with CCDs was INR 0.75 Crores for Q1FY27 compared to INR 2.1 Crores in Q1FY26.

• Beta continues to be one of the fastest-growing players in the Indian branded oncology pharmaceutical market, gaining market share y-o-y and is also emerging a strong innovation focused player.

• We are on track to deliver a 20-25% growth on a consolidated basis for FY27.

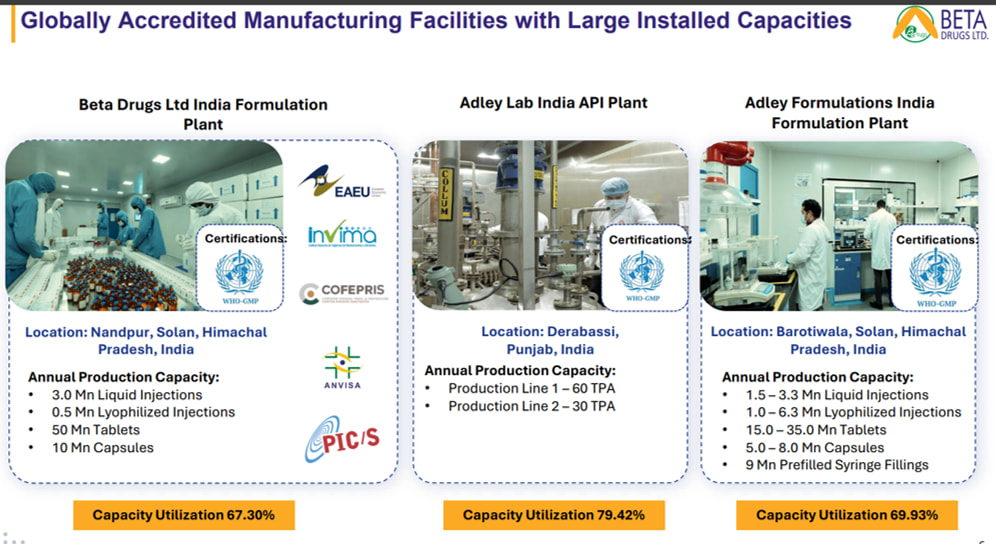
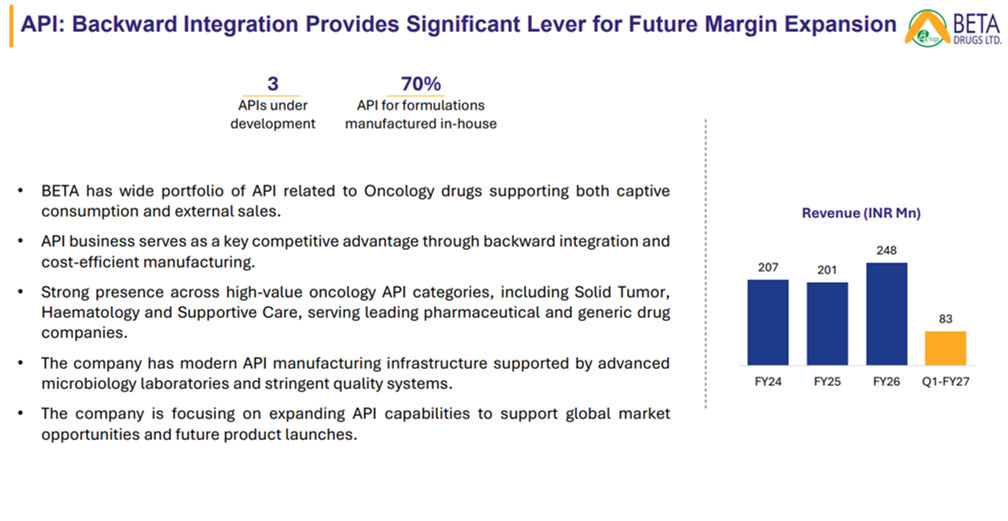
• Our backward integration in KSMs and advanced intermediates is expected to result in strong improvement in our operating margins coupled with change in product mix towards branded business

• Synergies with Beta are expected to result in higher operating margins for Nivian in FY27 and thereafter.

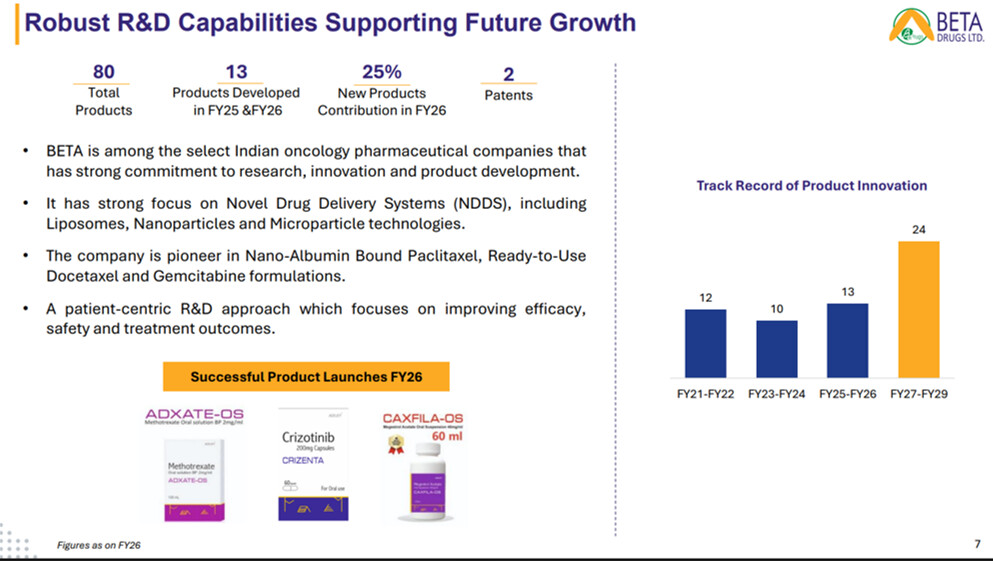
• We continue to invest in R&D and have a robust pipeline of NDDS products for launch in FY27 and FY28. This is in addition to new launches where Beta will strive to be either First to Launch / First few to Launch in India.

• Global Clients – 246+.
SKU’s - 220+
Dossiers Registered Globally - 280+
Territory Managers - 66+

•

•

•

•

•

•

•

•

•

4 Likes

Beta delivered a brilliant all round performance in Q1, getting back to its compounding ways after subdued performance for last 1.5 years.

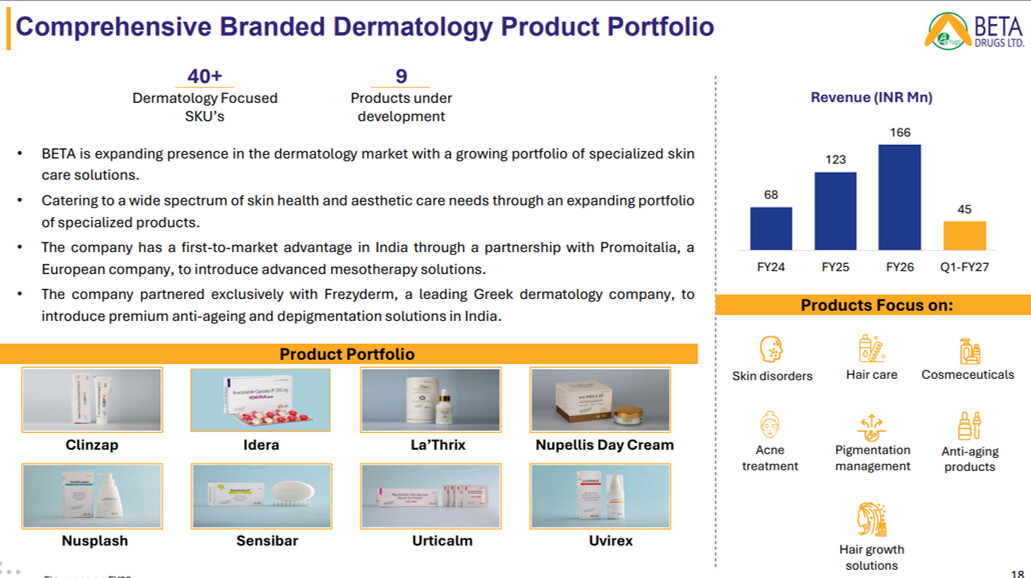
Almost all growth drivers were firing on all cylinders, except derma and exports (exports due to tender timings).

Nivian already seems like a great acquisition, especially considering the long term secular growth runway for the IVF industry in India.

I believe Q2 would be even stronger given that exports will be much better and platins price hike by NPPA would have its full effect.

DISCLOSURE: INVESTED.

8 Likes

I had talk with management of beta drugs on call.As per him, there will be no effect of new policy on margin of beta drugs. He has given below example.

Suppose, beta drugs is sellling one drug at Rs 1500 to retailer or hospital pharmacy and that retailer/hospital is selling at Rs 7000(MRP).As per new govt policy, MRP price will be reduced at around ,say @Rs 3000-4000.But manufacturer’s margin will not have significant effect..Other manufacturer of onco drugs, like sakar, torrent, Natco will have same effect

I have asked, why other companies will not start selling at Rs 1200.
As per him, it is difficult for onco drugs to be sold below such prices.

He told, overall negligible effect on beta drugs.

And lastly, this minimal effect is only for branded business.Other verticals like API,cdmo and export businesses will have no effect at all.

6 Likes