The guidance was 30-35% growth, they delivered exactly that number
1 Like
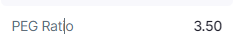
PEG ratio means PE/growth . In this case it is 60/30 =2 . not 3.5
Disc- Invested
1 Like
It’s showing 3.5 on the screener. Perhaps the numbers haven’t been updated.
they have met the guidance on growth and EBITDA - one at the higher end of the range and other at the lower end of the range
2 Likes

I like how AurionPro makes strategic acquisitions. First Arya.AI, which acquisition enables them to enhance their own suite of offerings with Arya.AI’s cpabilities in AI.
Now, they’ve acquired Fenixys, a consulting firm focussed on Europe and ME. With this, I think AuriooPro could get good cross selling opportunities with Fenixys’ clients, and a foot in the door to Europe!
6 Likes
Aurionpro | Q3 FY25 Results
33% YoY growth to INR 306 Crore!
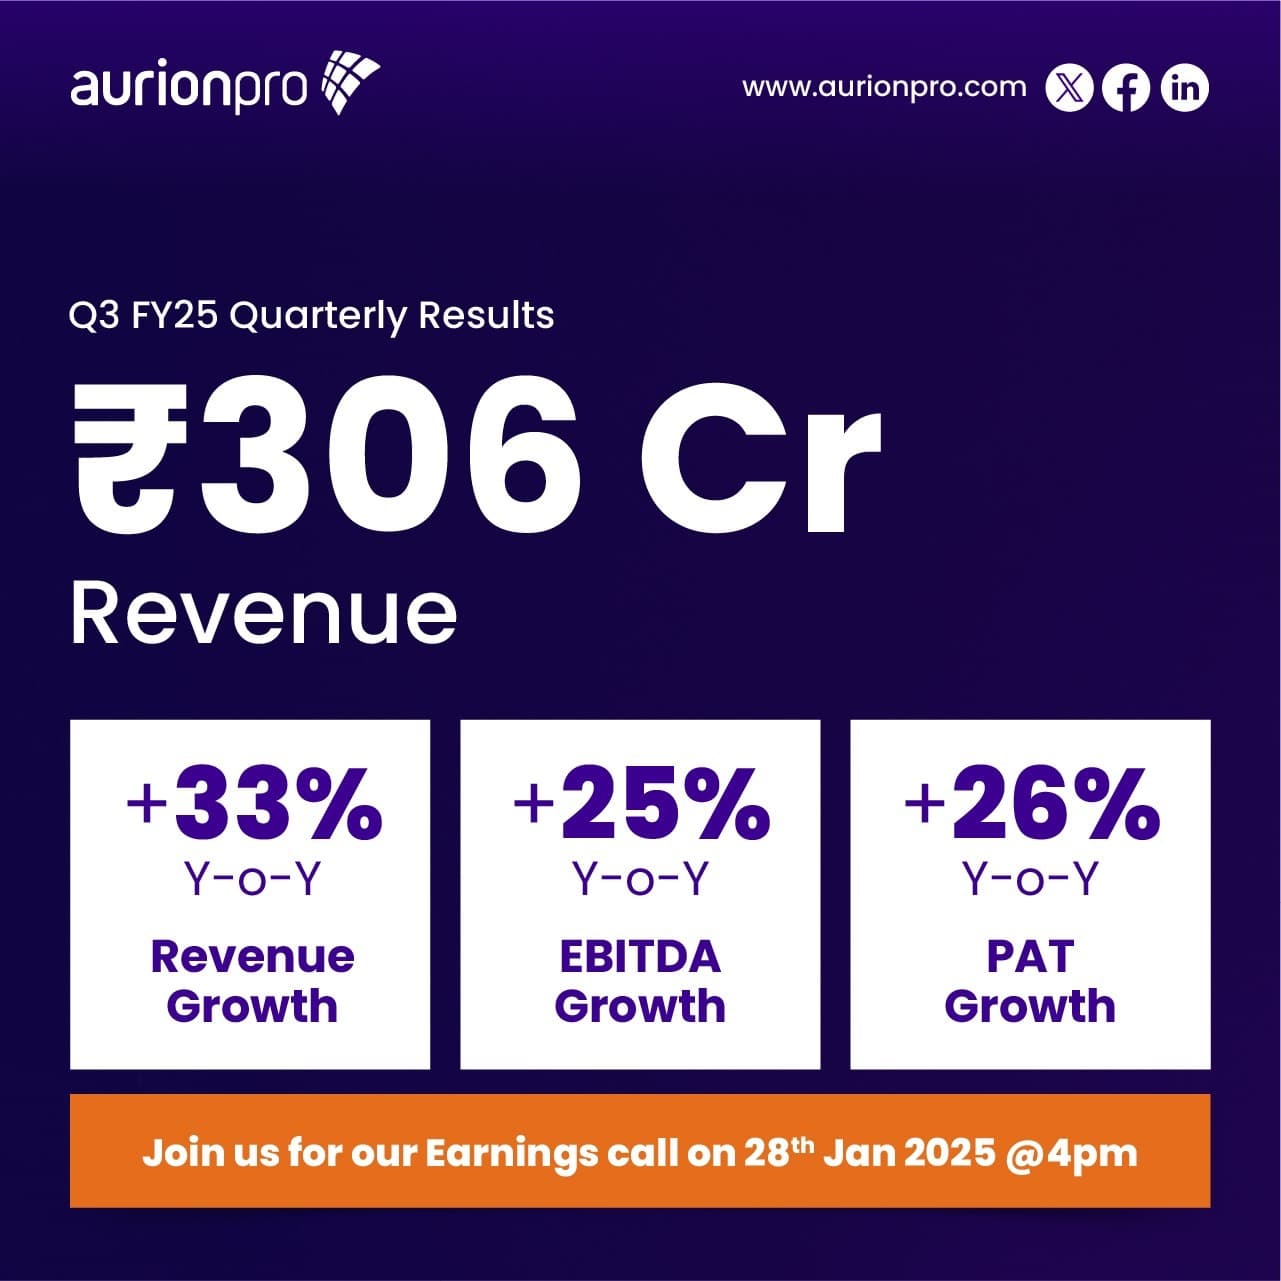
This achievement reflects our relentless drive for innovation and our commitment to creating value for our clients and stakeholders.
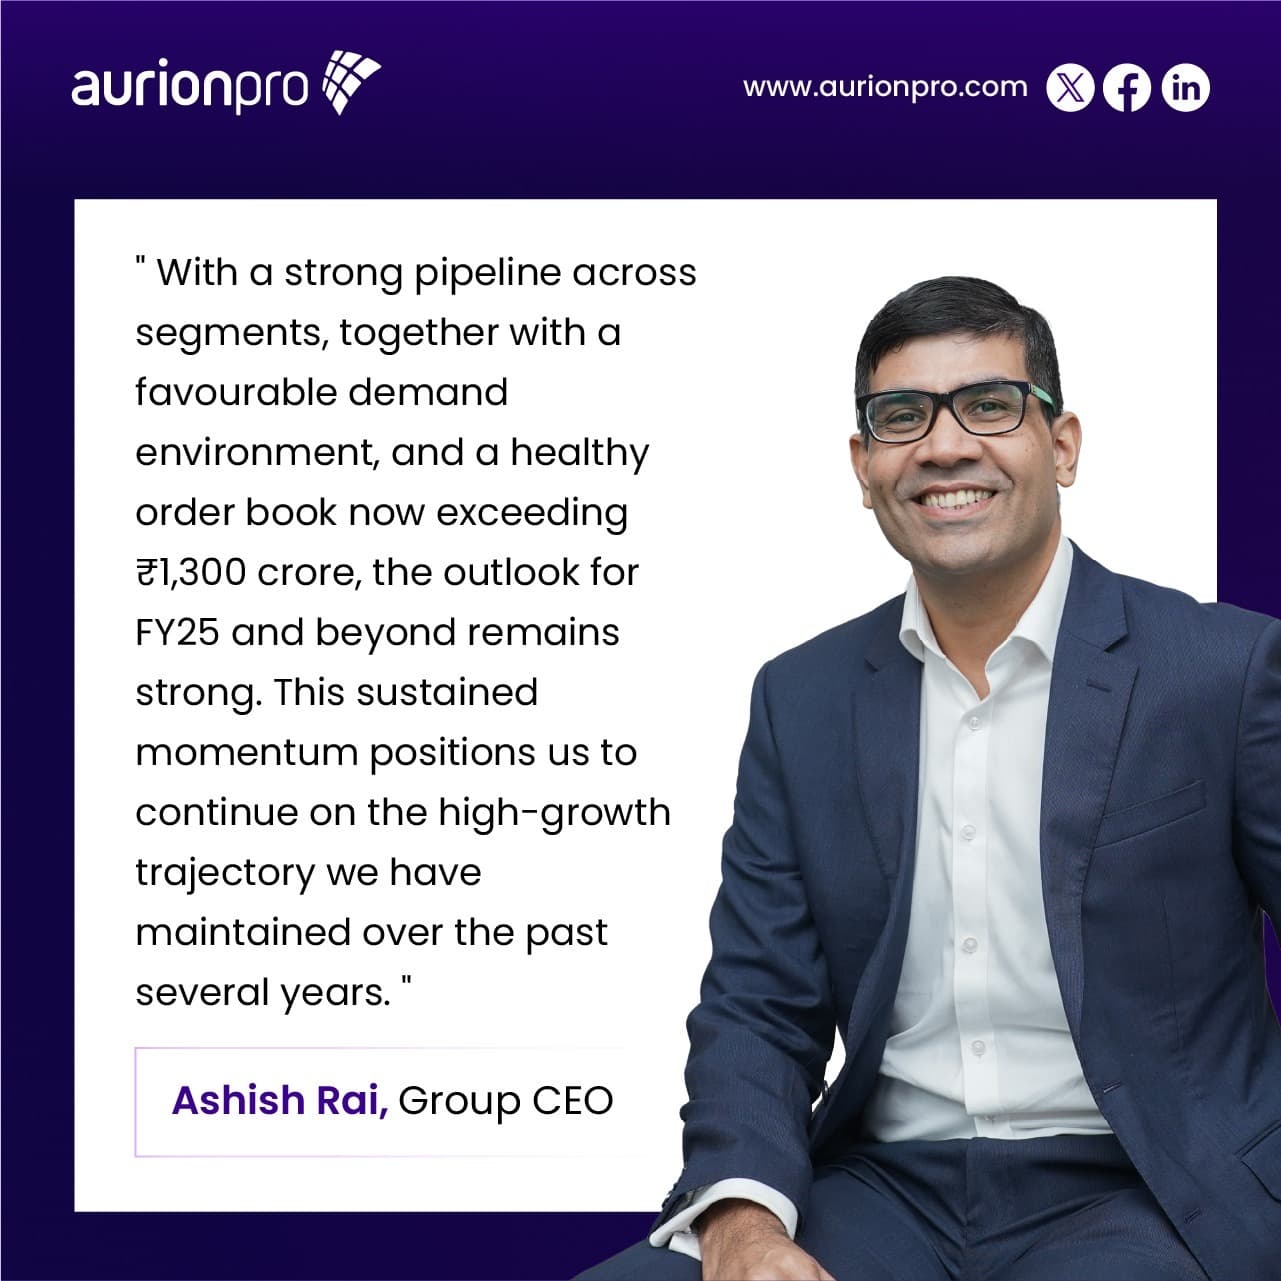
Outlook for #FY25 and beyond remains highly optimistic’
Company remains confident of achieving guided growth of 30%+ for FY25
4 Likes
Excellent results and very upbeat tone at the concall. I think they continue to execute very well (on target to end the year with 30-35% growth in revenue) and the overall correction has made the price a bit attractive!
The great thing this quarter has been that both banking and the TIG segments have grown very well! And Rai emphasised ‘unprecedented demand levels’, esp in the banking vertical.
4 Likes
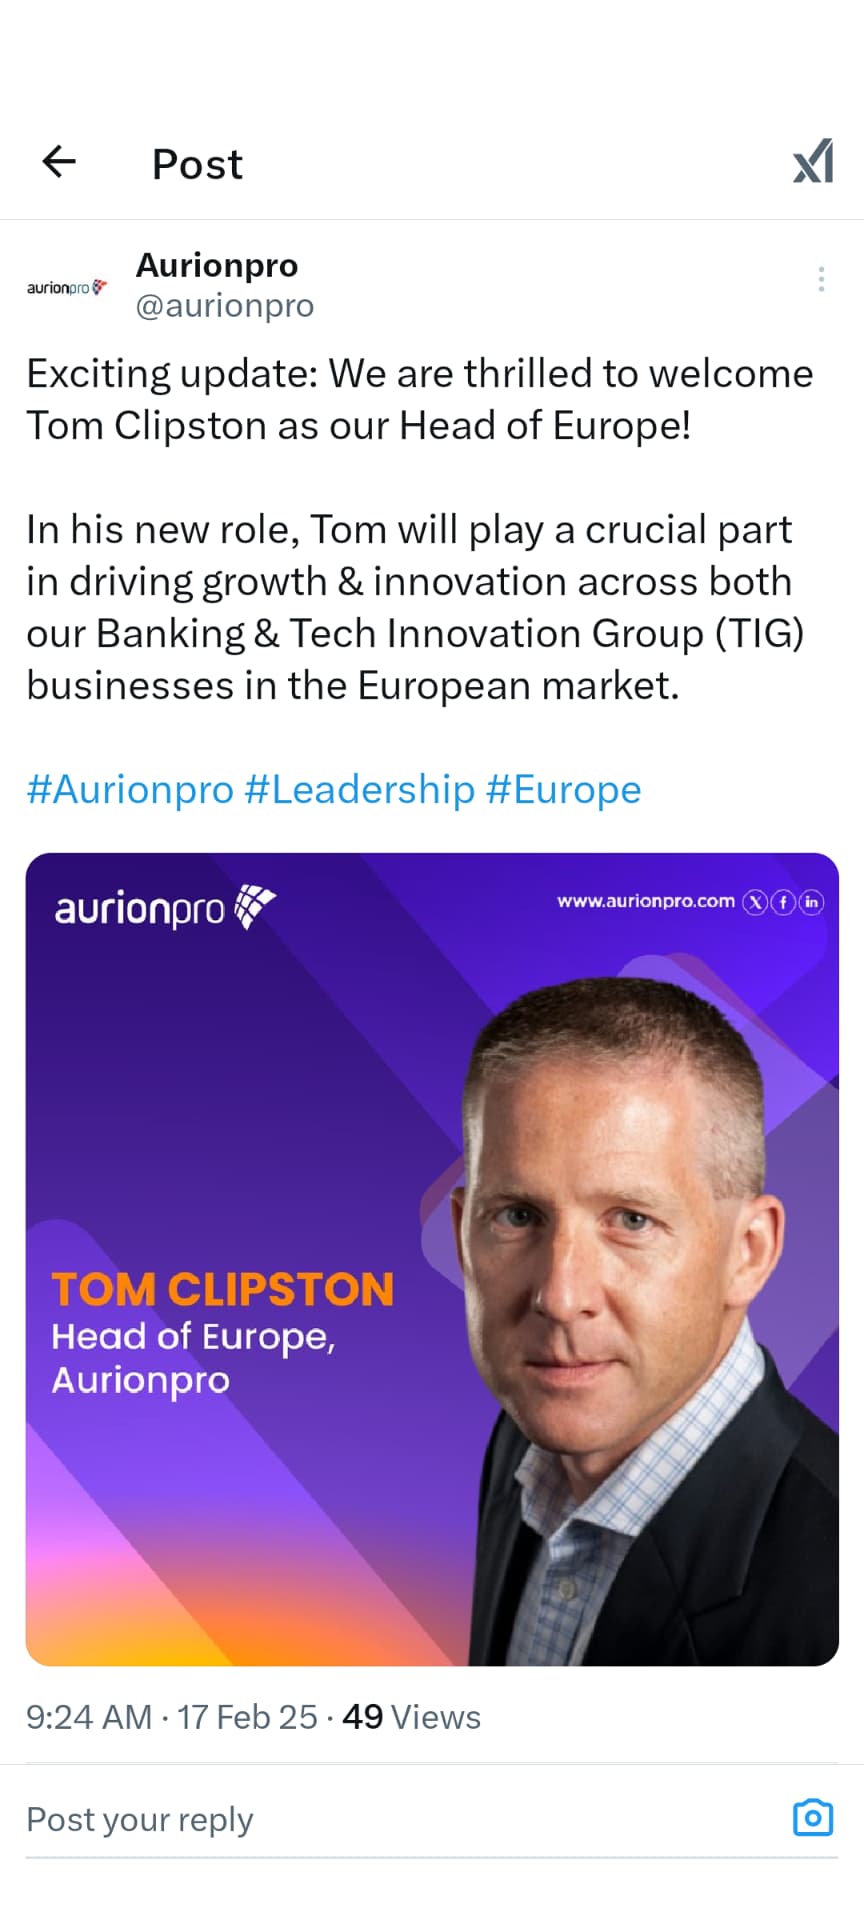
" Exciting update: We are thrilled to welcome Tom Clipston as our Head of Europe!
In his new role, Tom will play a crucial part in driving growth & innovation across both our Banking & Tech Innovation Group (TIG) businesses in the European market.
"
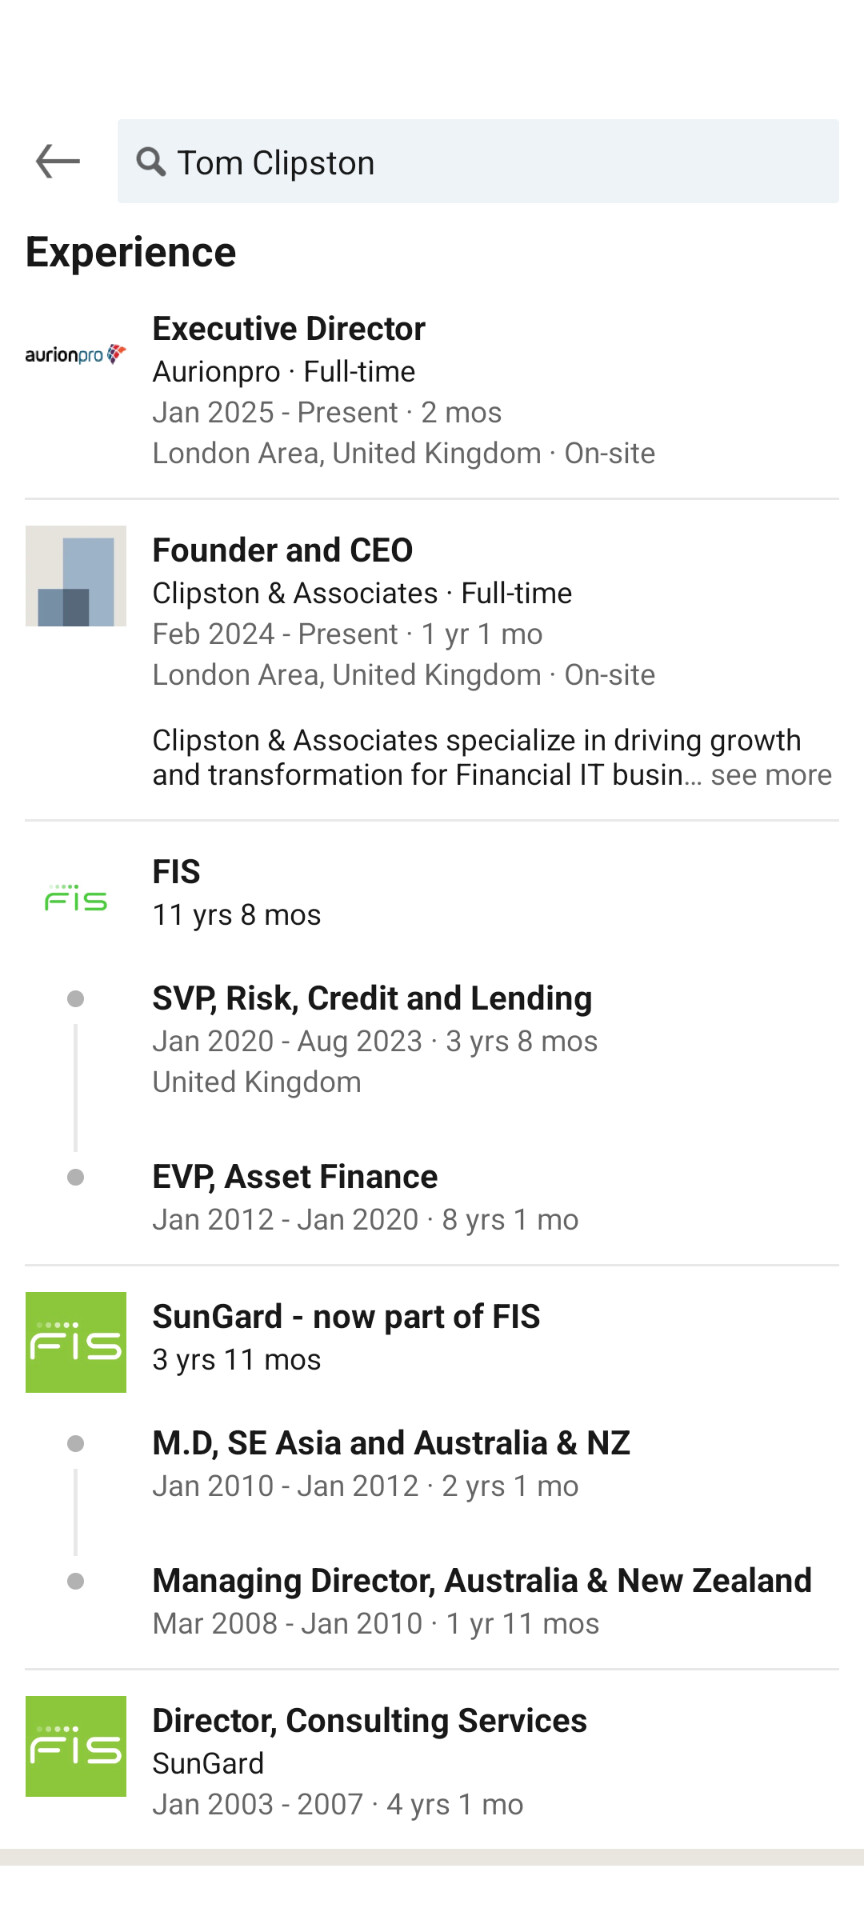
I read this as an indicator of how seriously they are now focusing on Europe. His credentials seem very compelling to put their name out there about European banks!
2 Likes
is Aurionpro’s business model prone to disruption due to innovations in AI?
whats gonna be the effect on the company due to AI?
They have acquired an Ai company, Arya.ai to provide Ai capabilities to their existing products in financial sector
The way I see it, the opportunity lies in incorporating AI tools into products. For instance, if a company has a credit control and management product for banks, incorporating AI into it for credit evaluation would add a lot of value. Sooner or later, every company will have to do it. I see their acquisition of Arya.ai in that light.
7 Likes
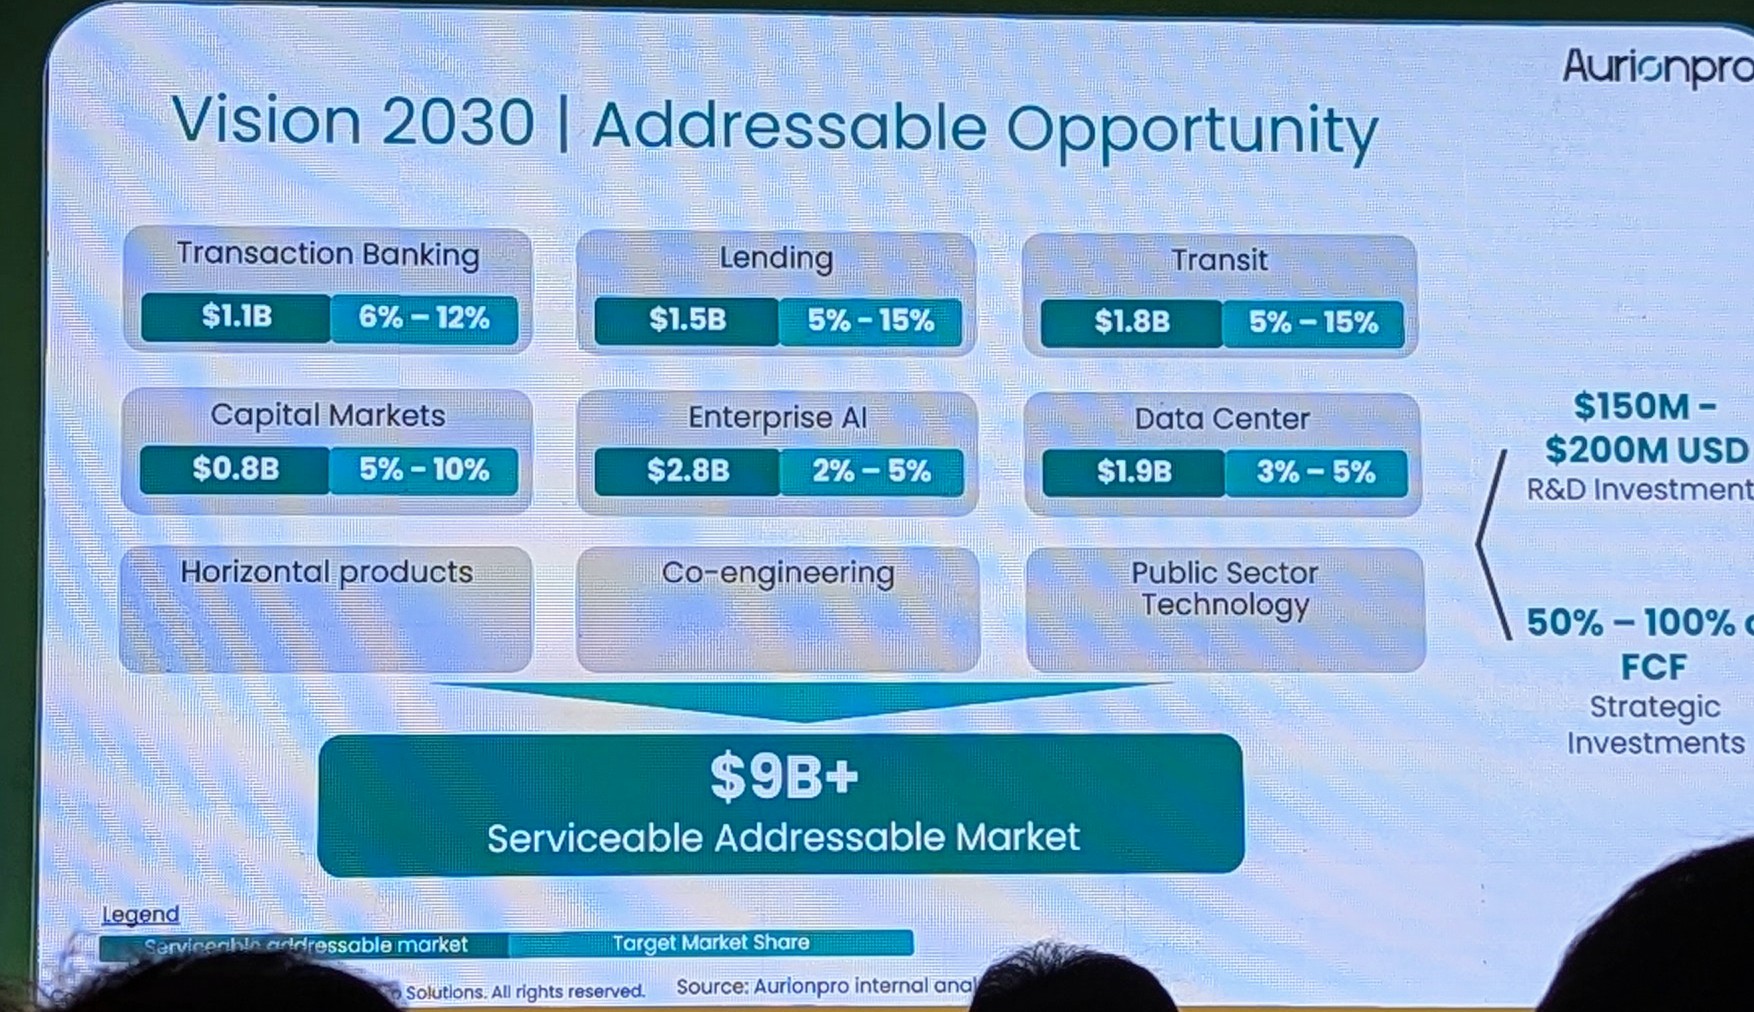
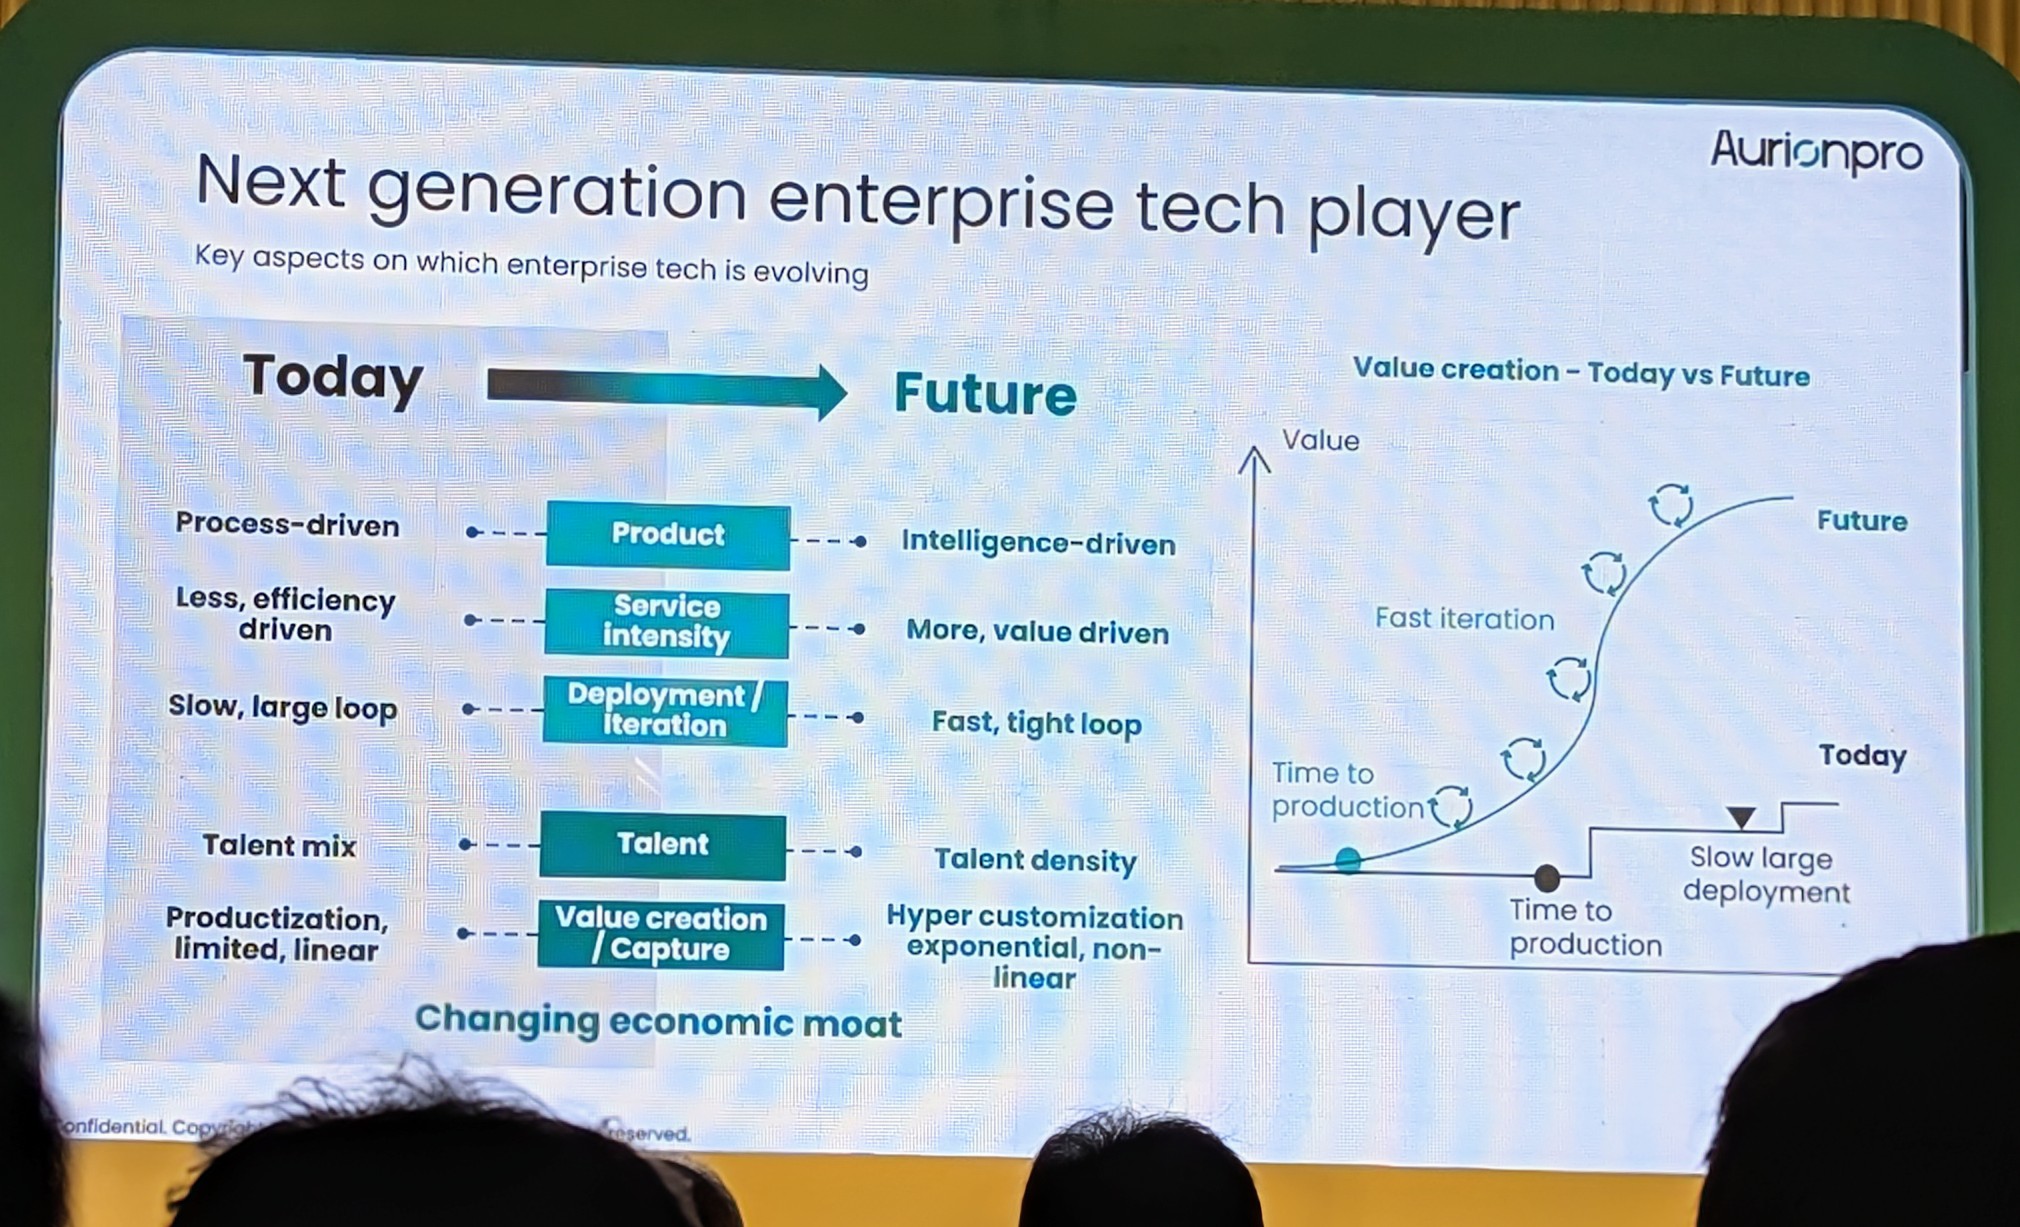
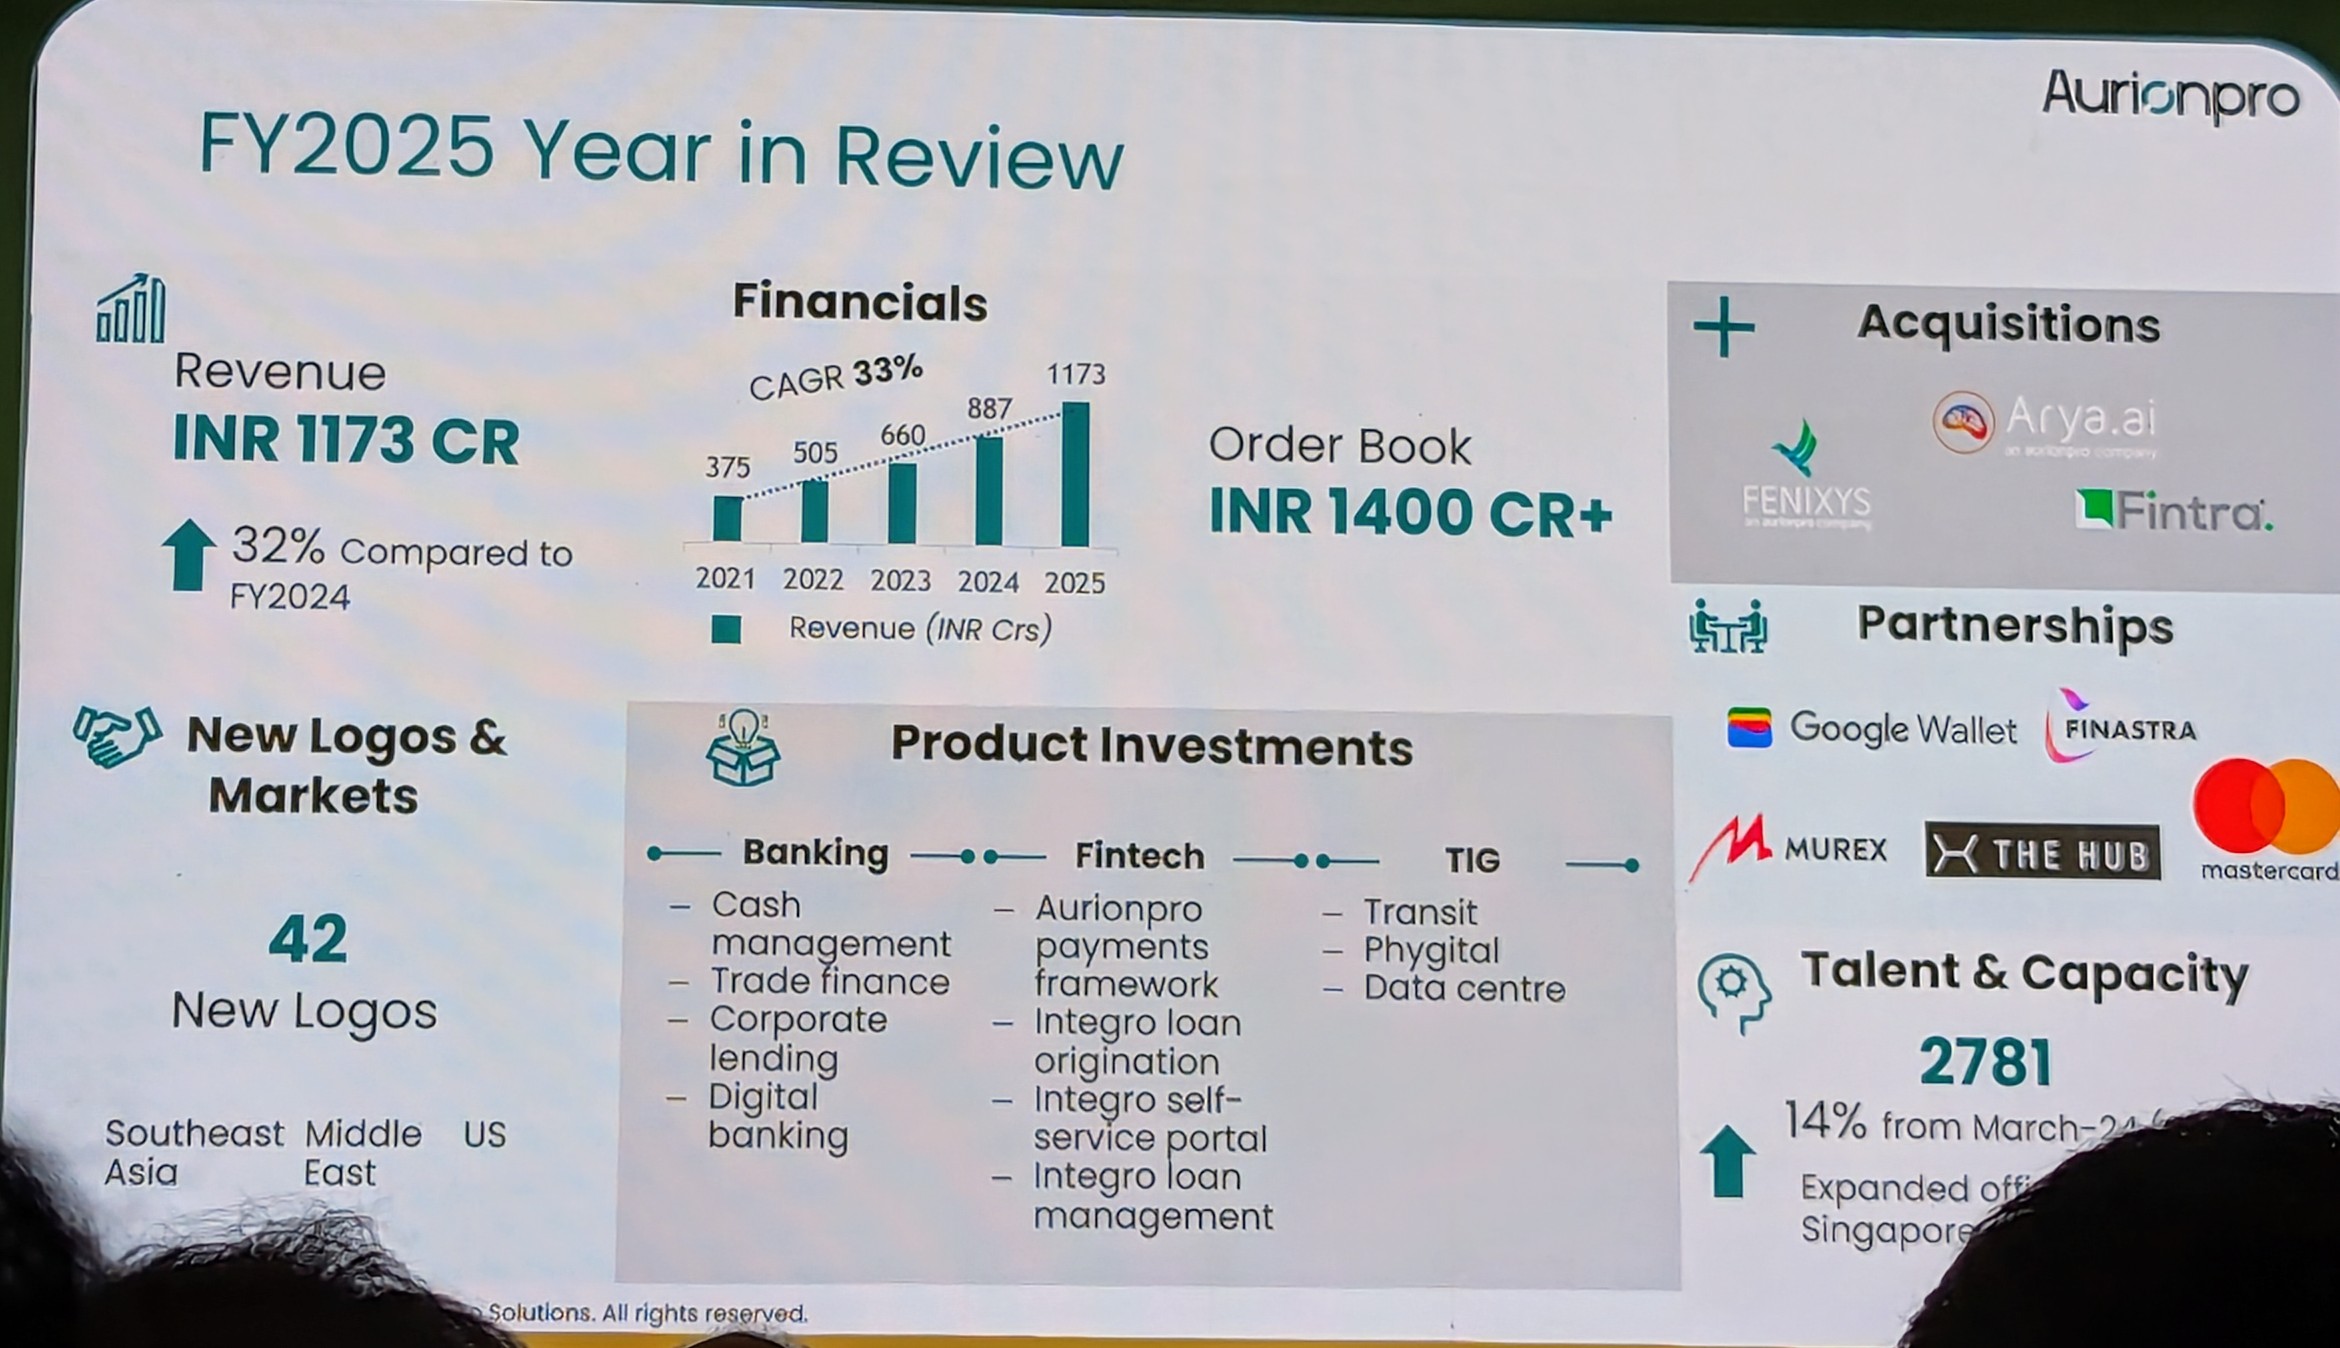
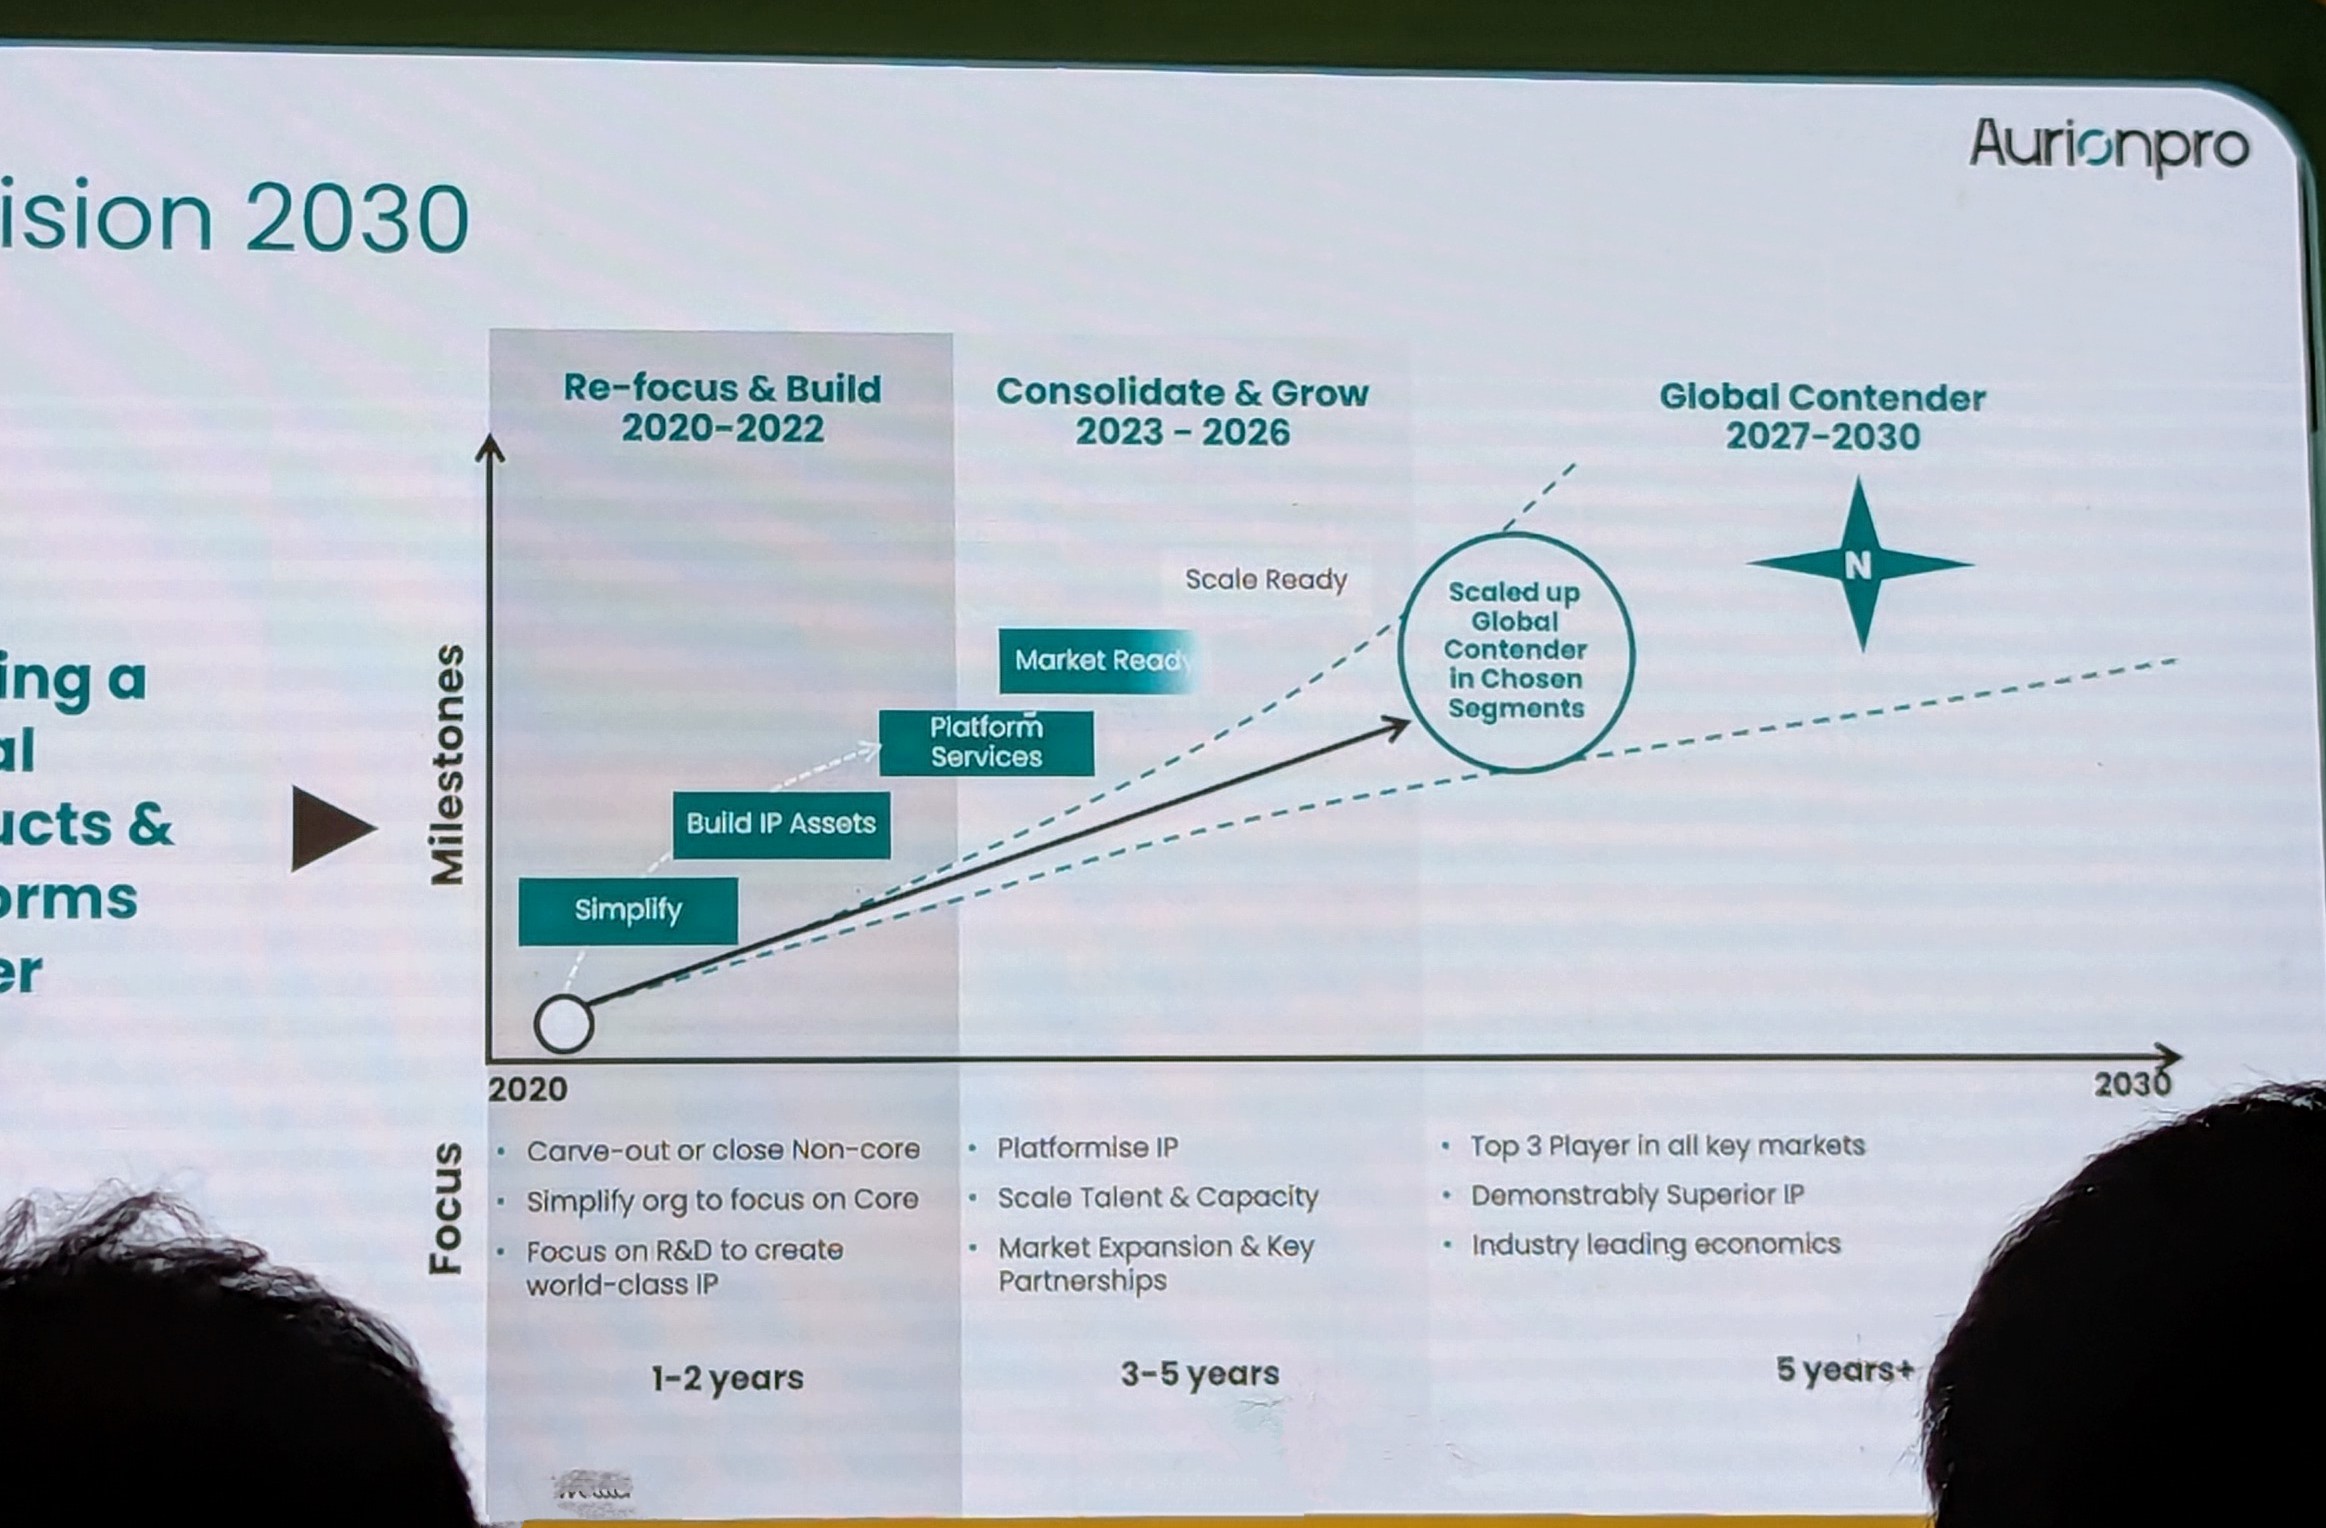
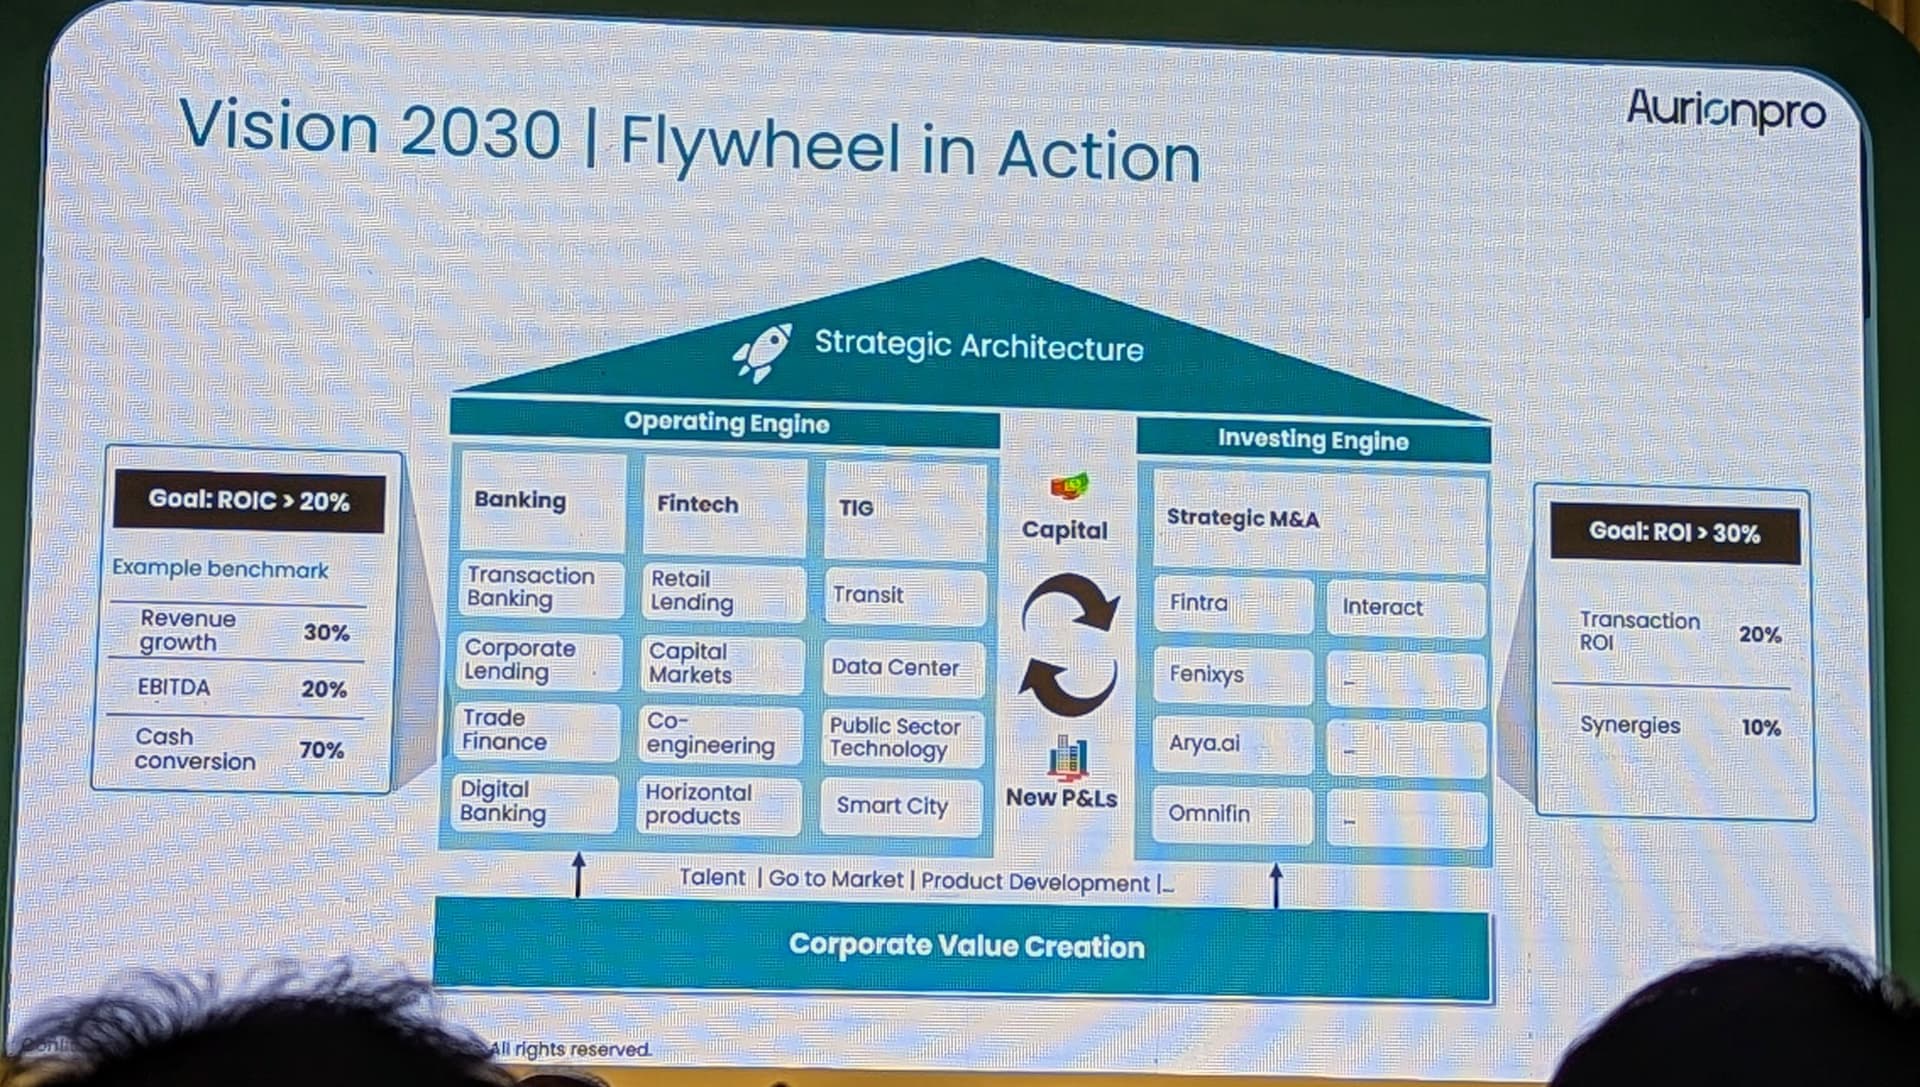
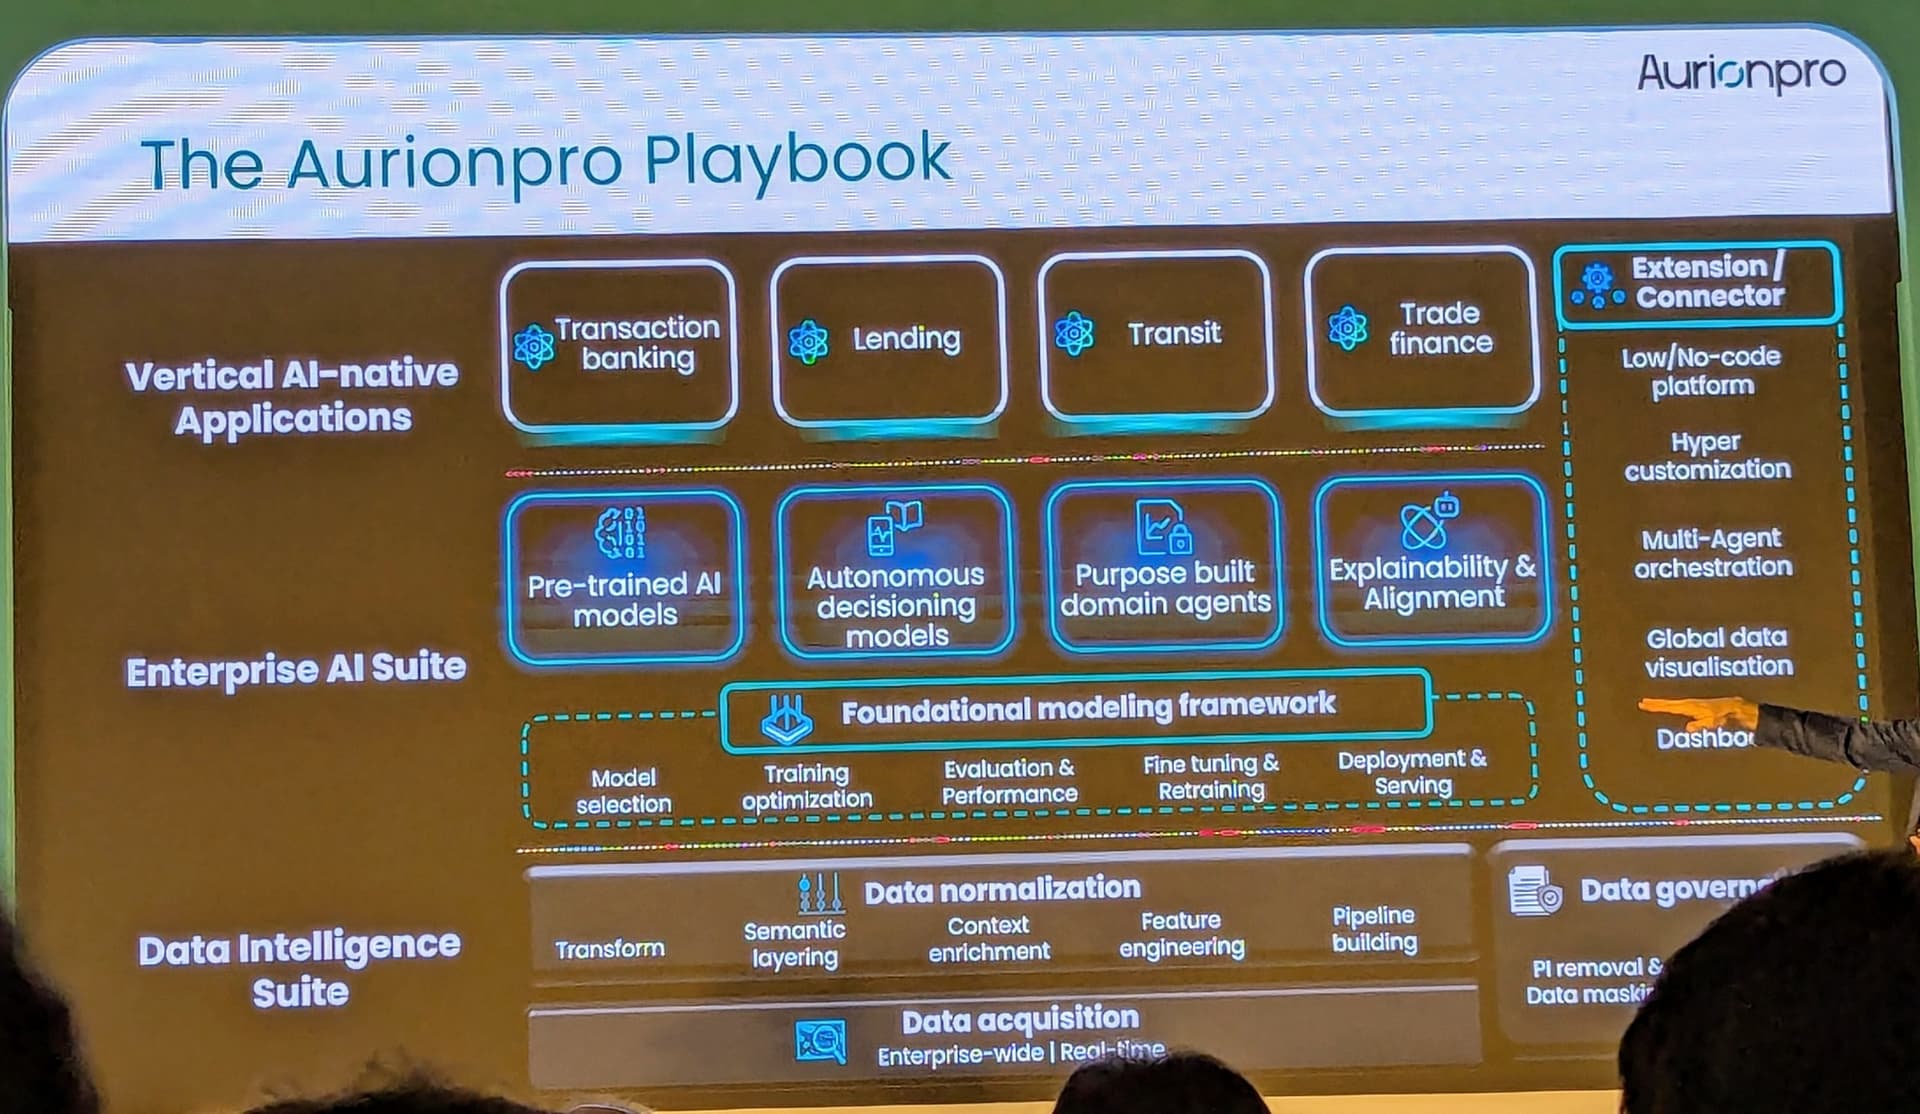
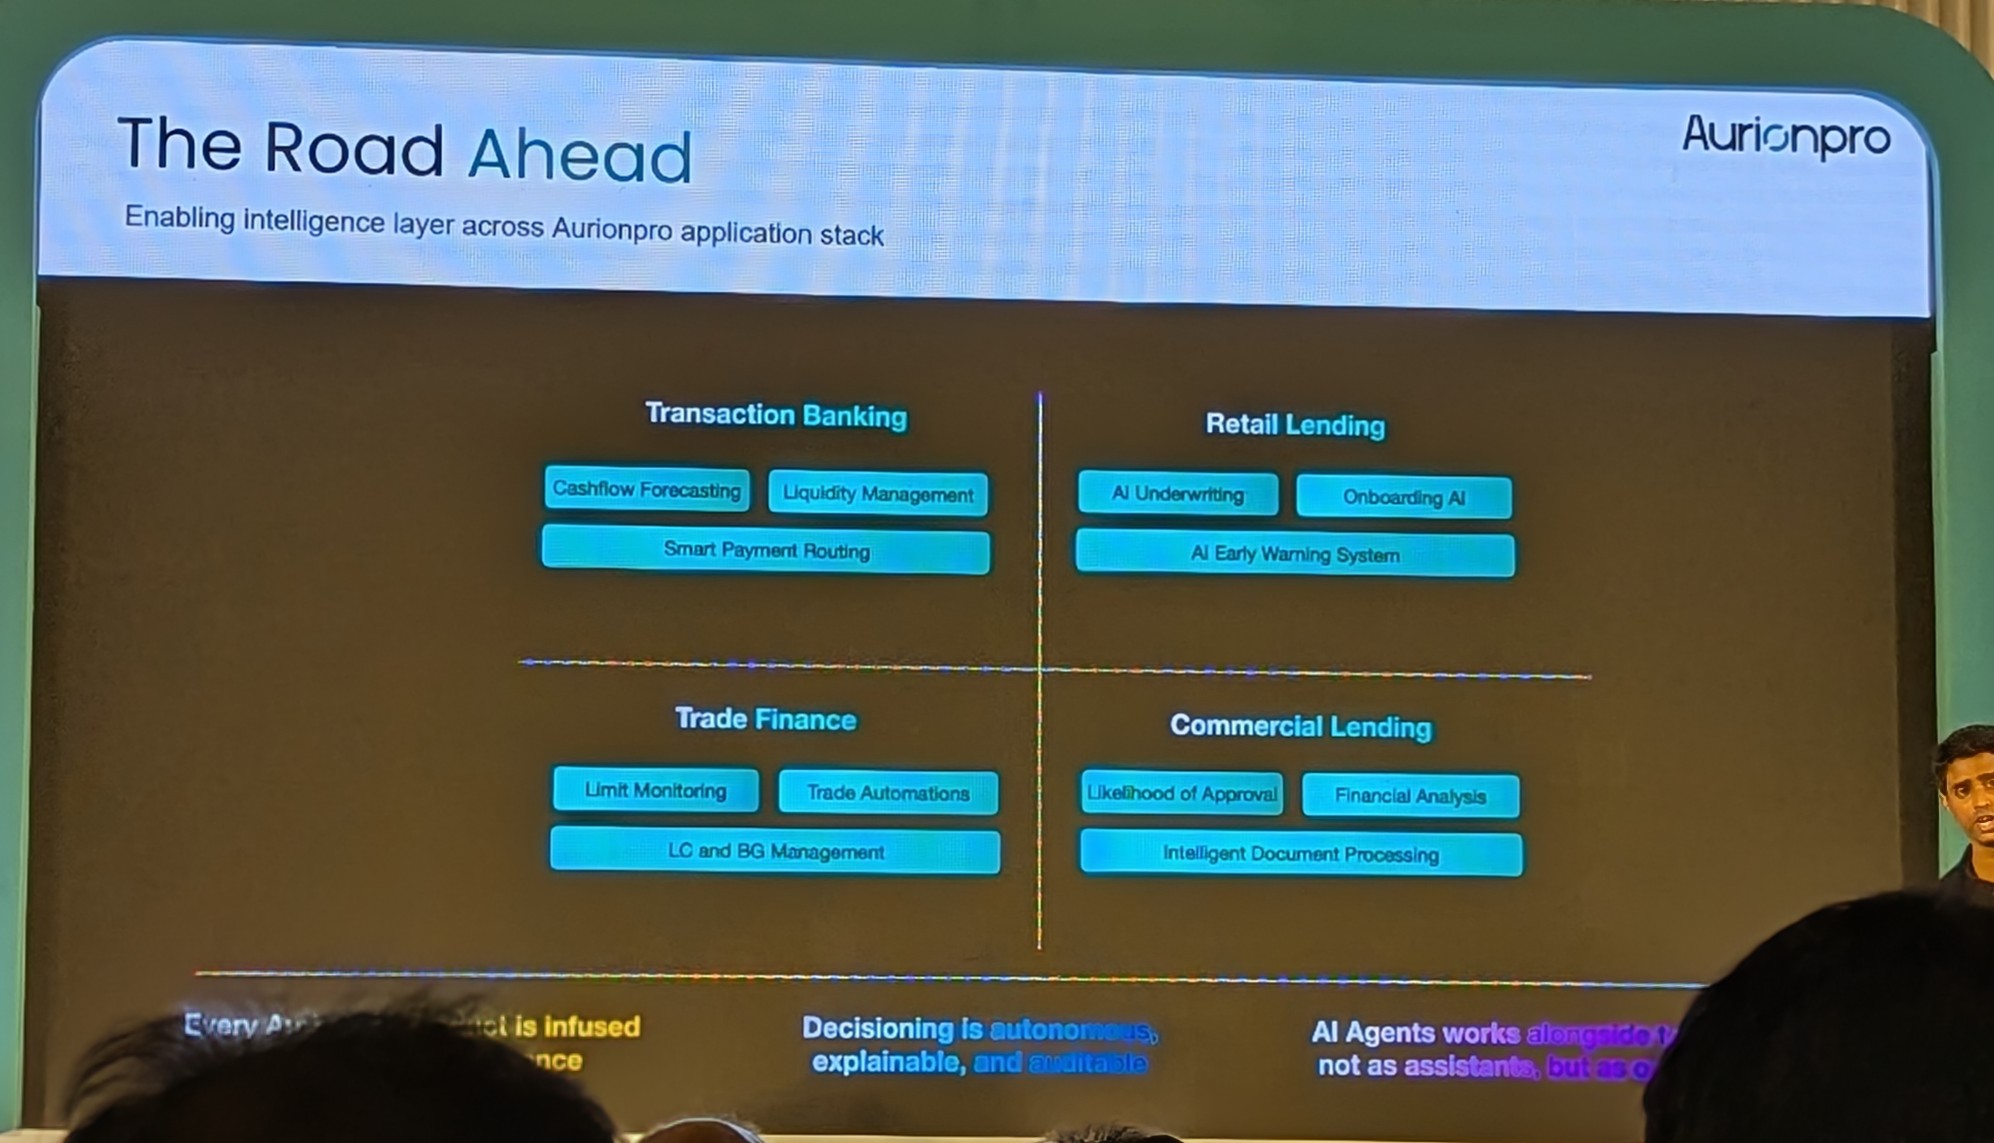
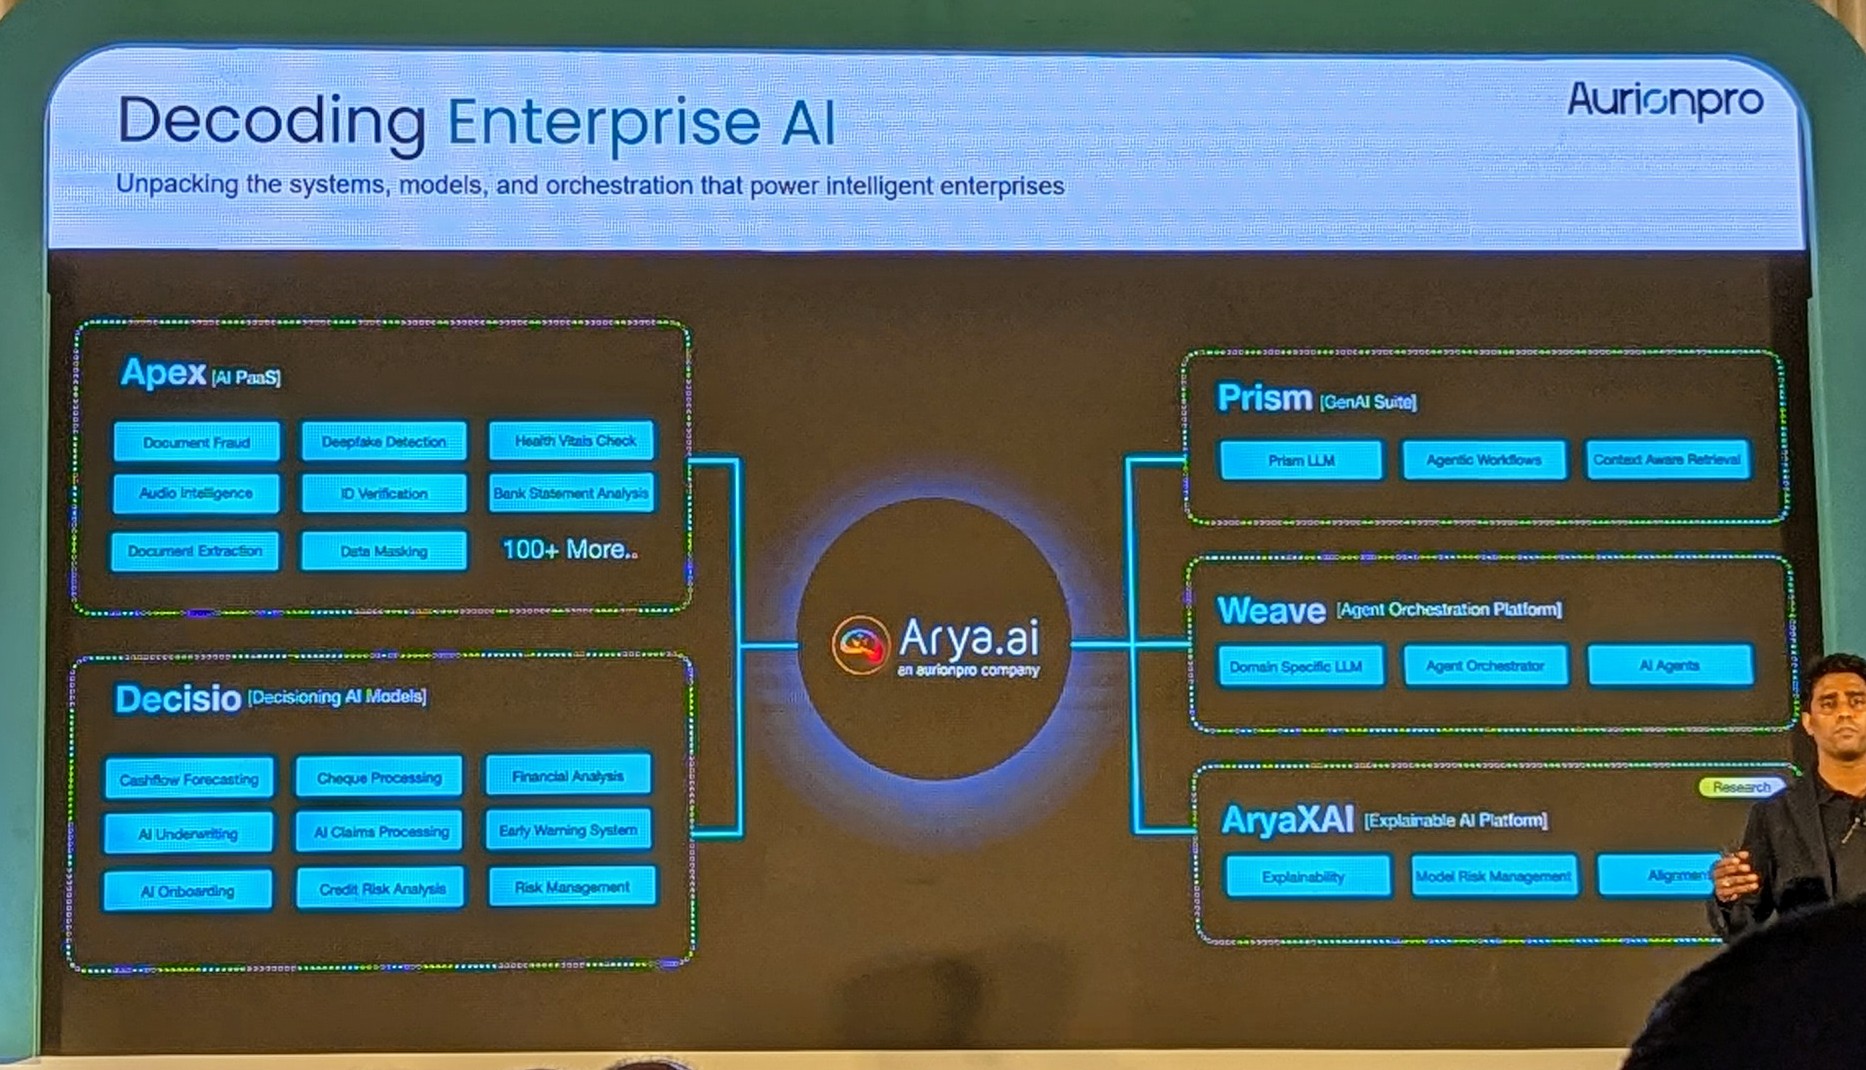
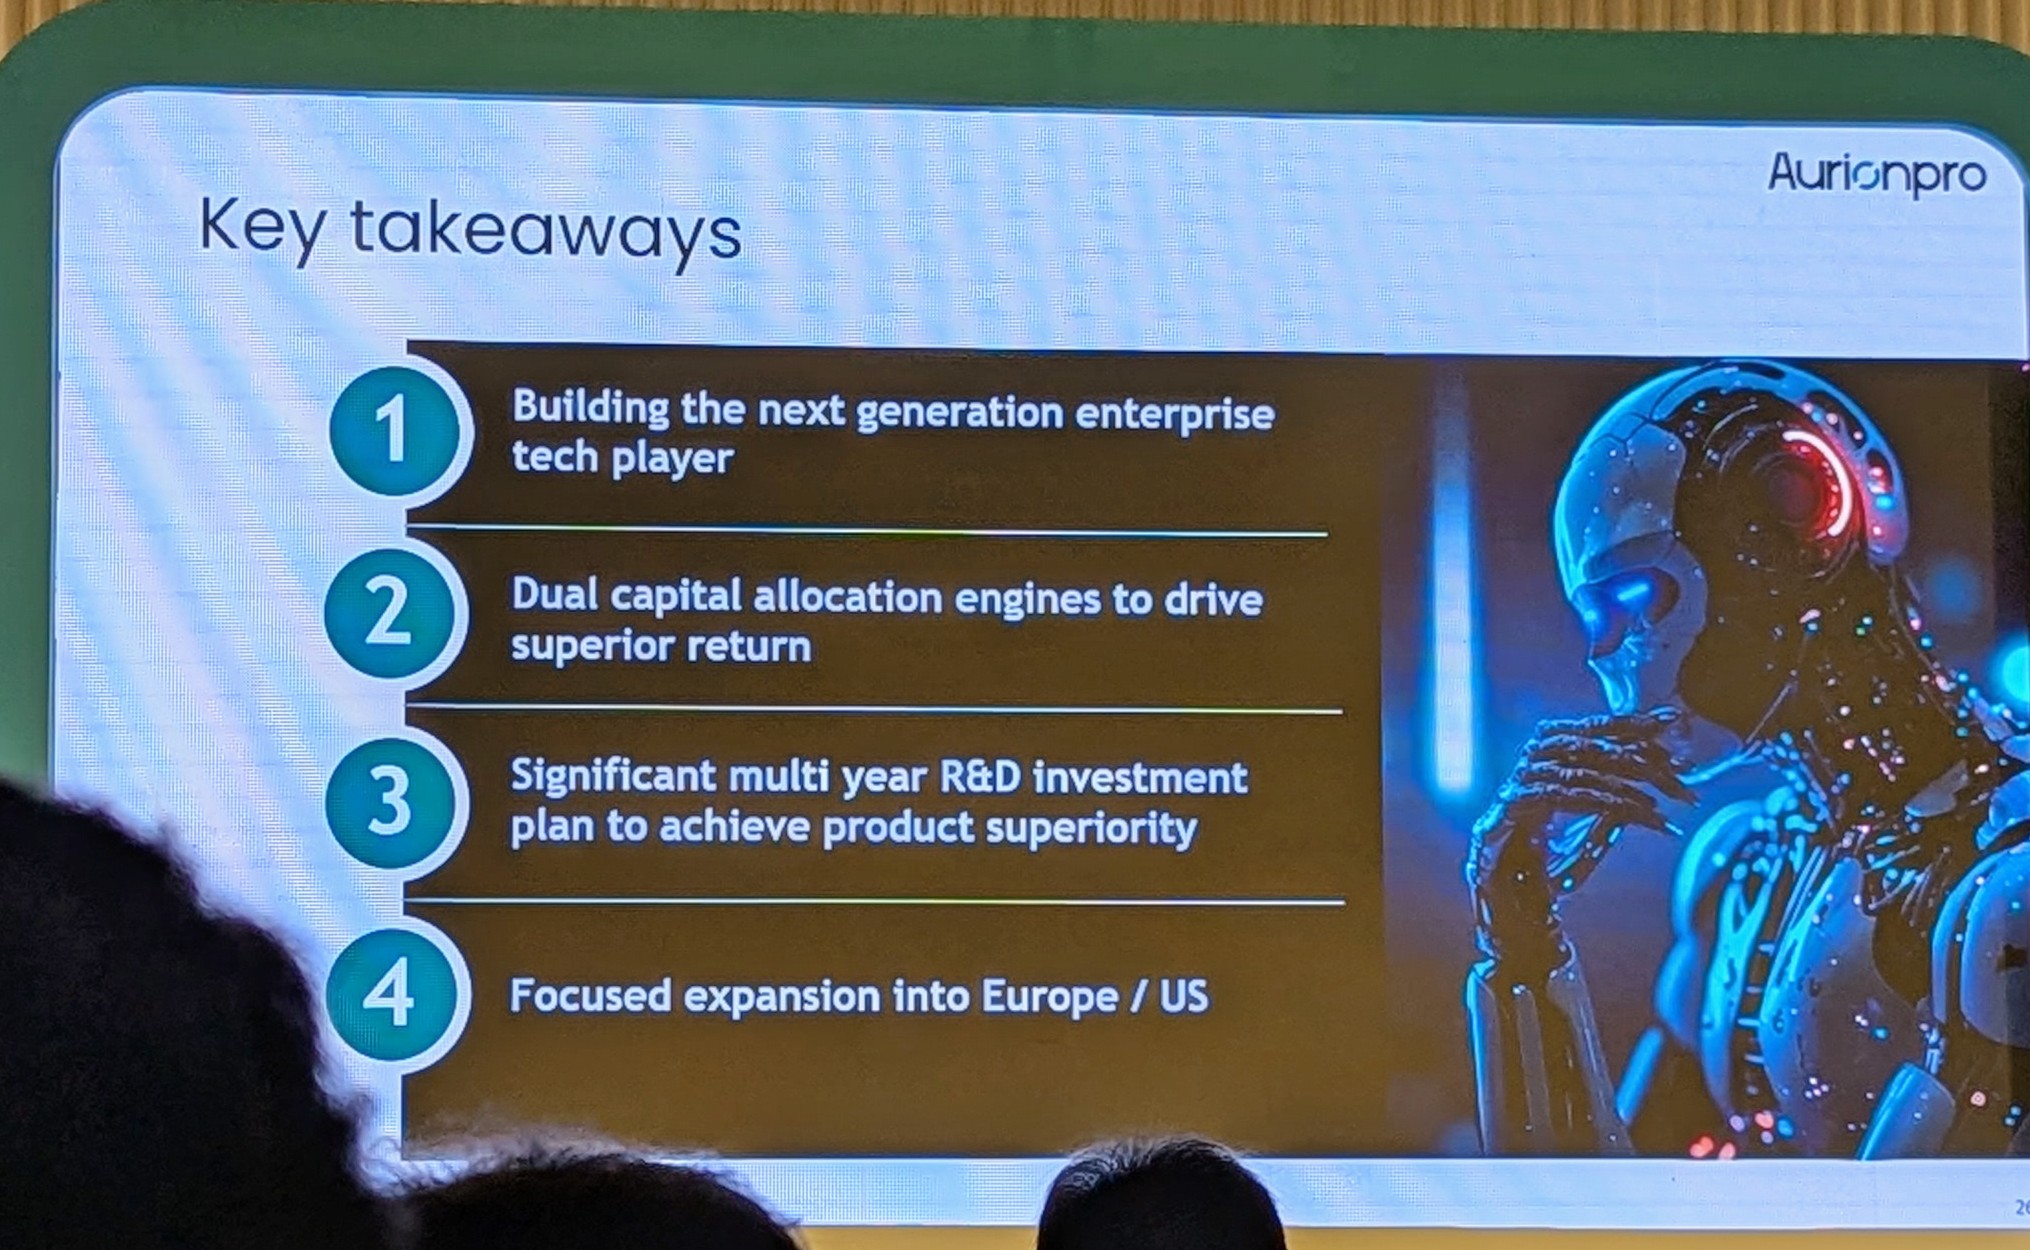
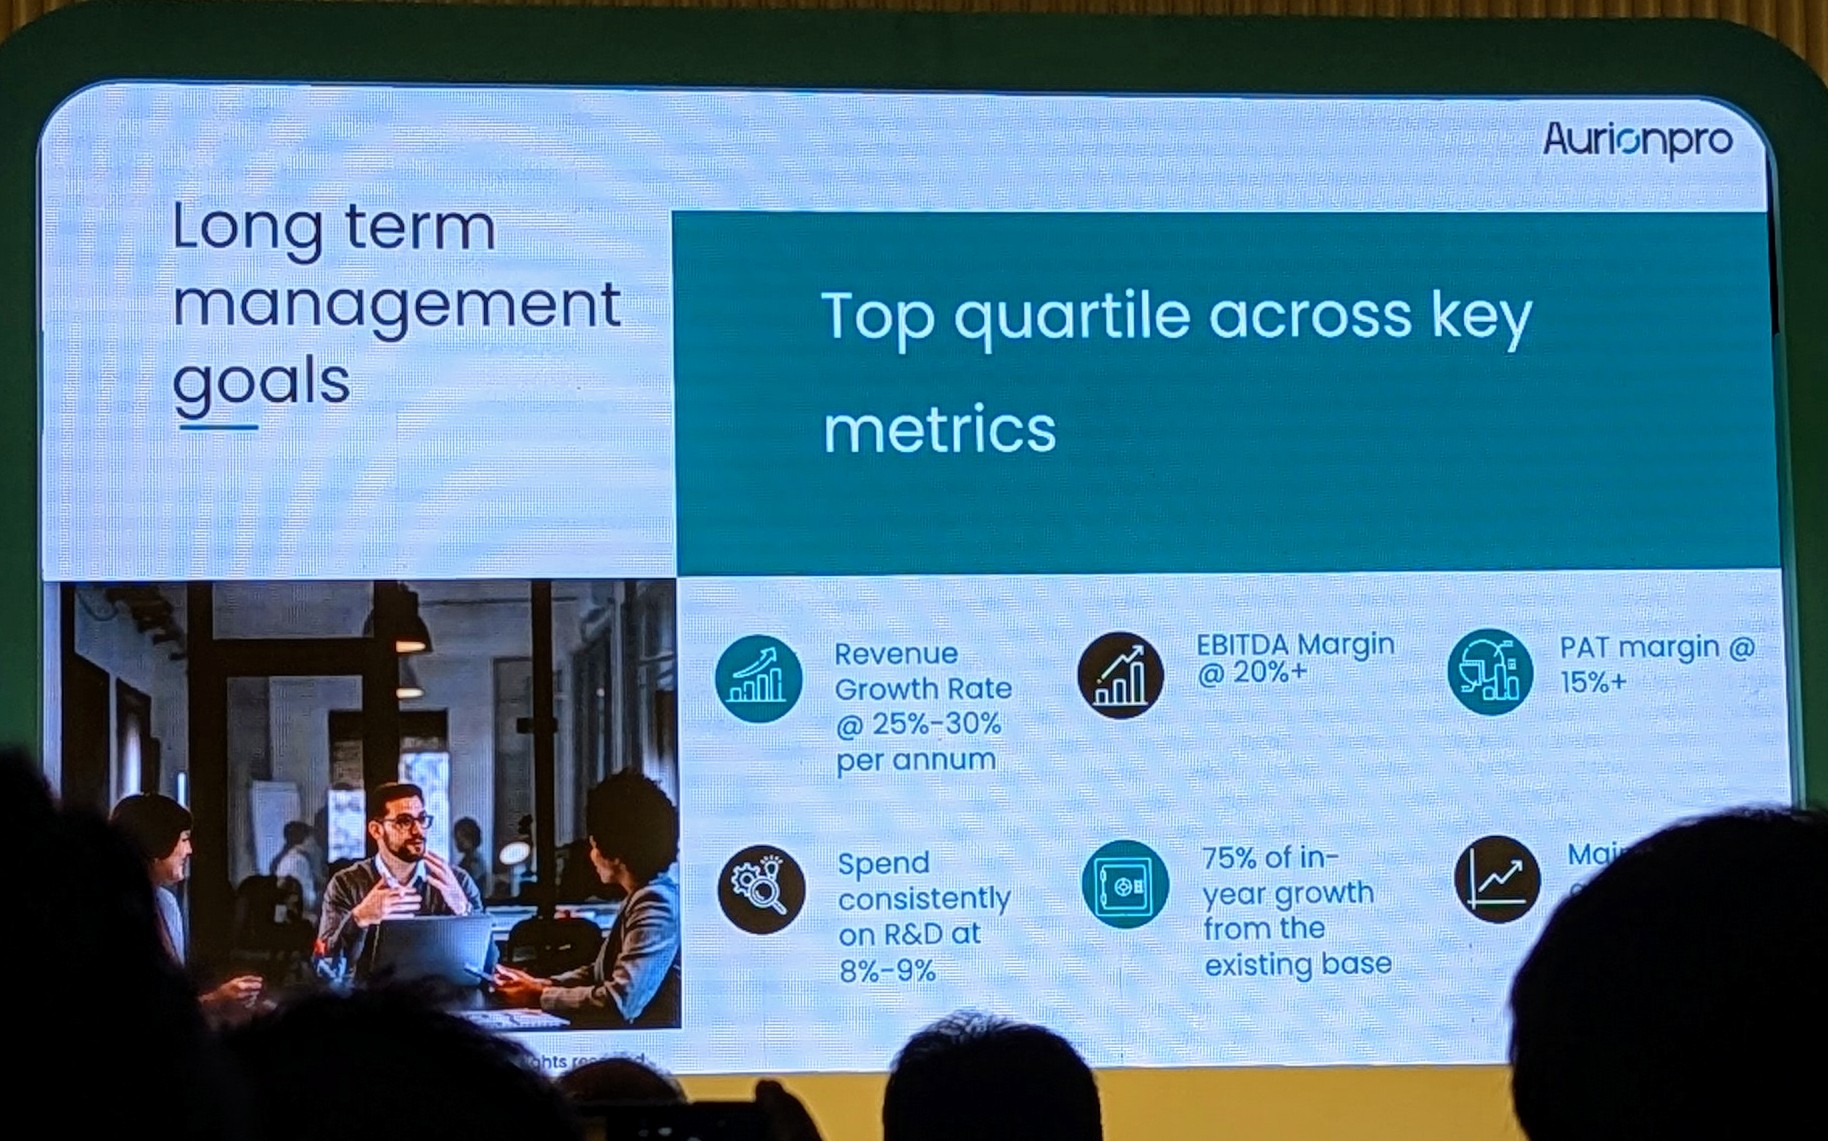
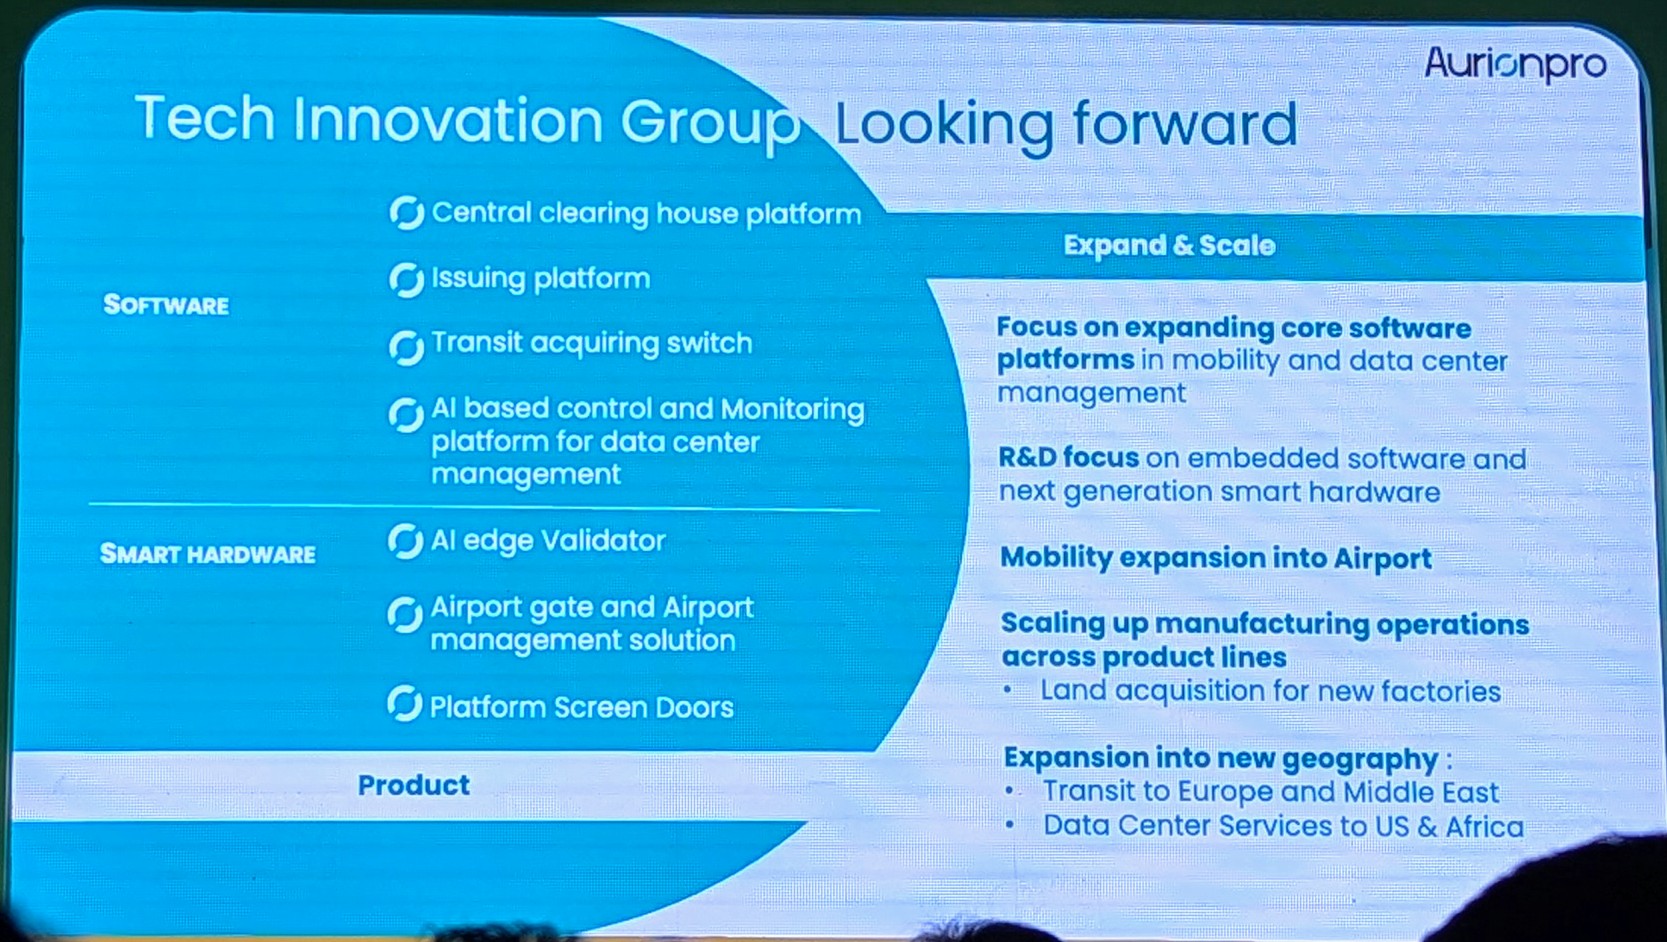
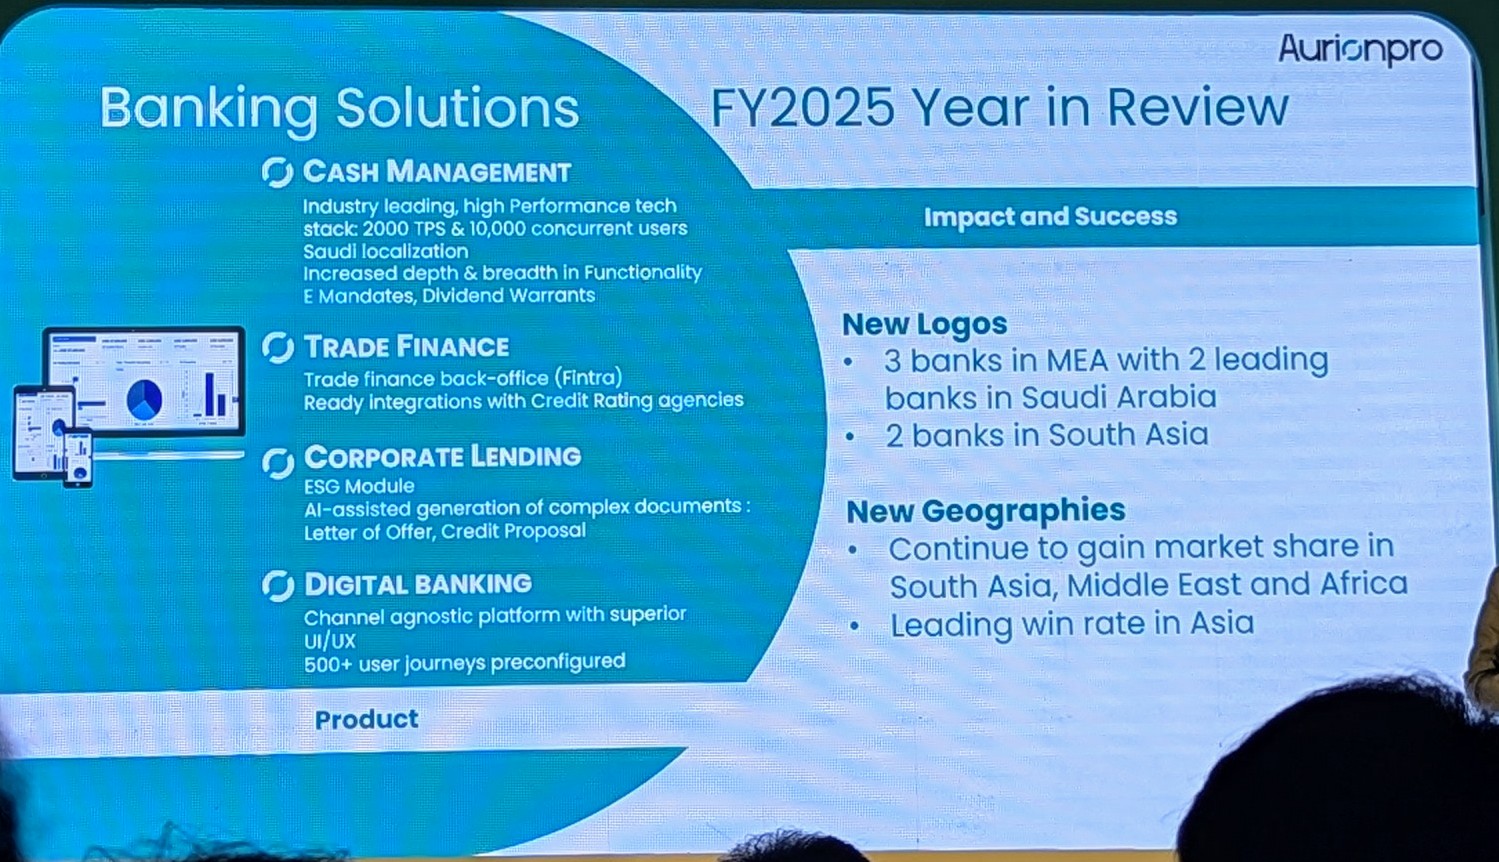
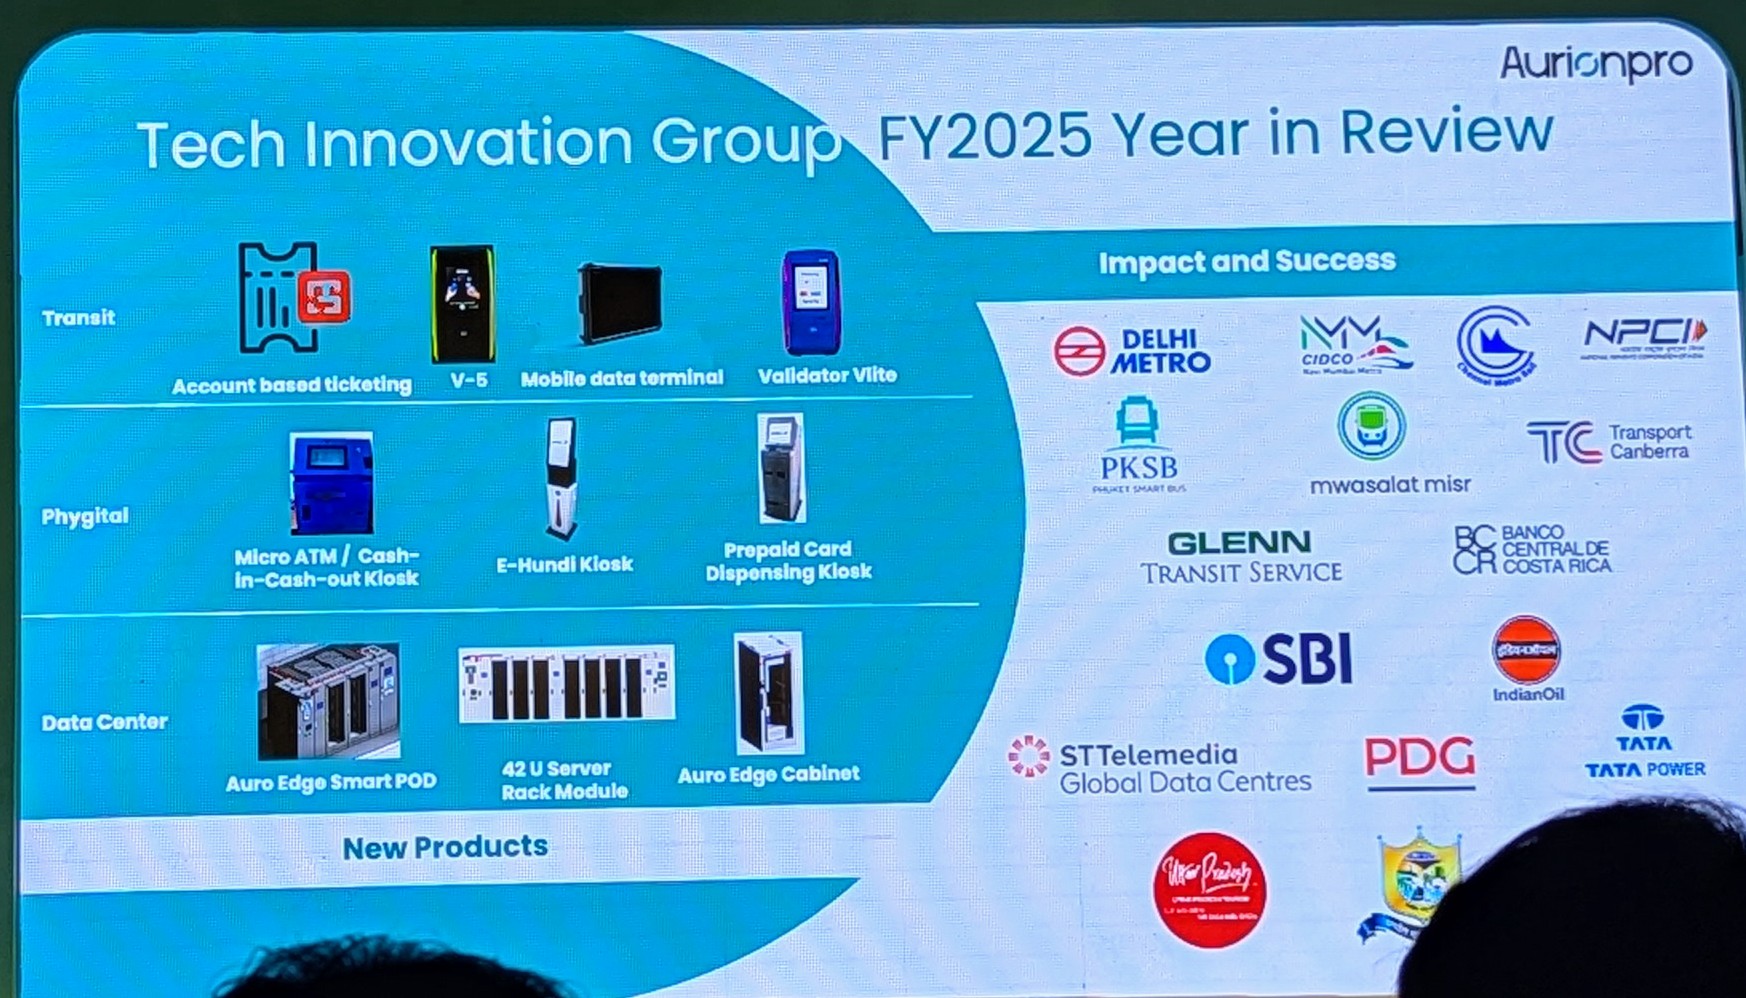
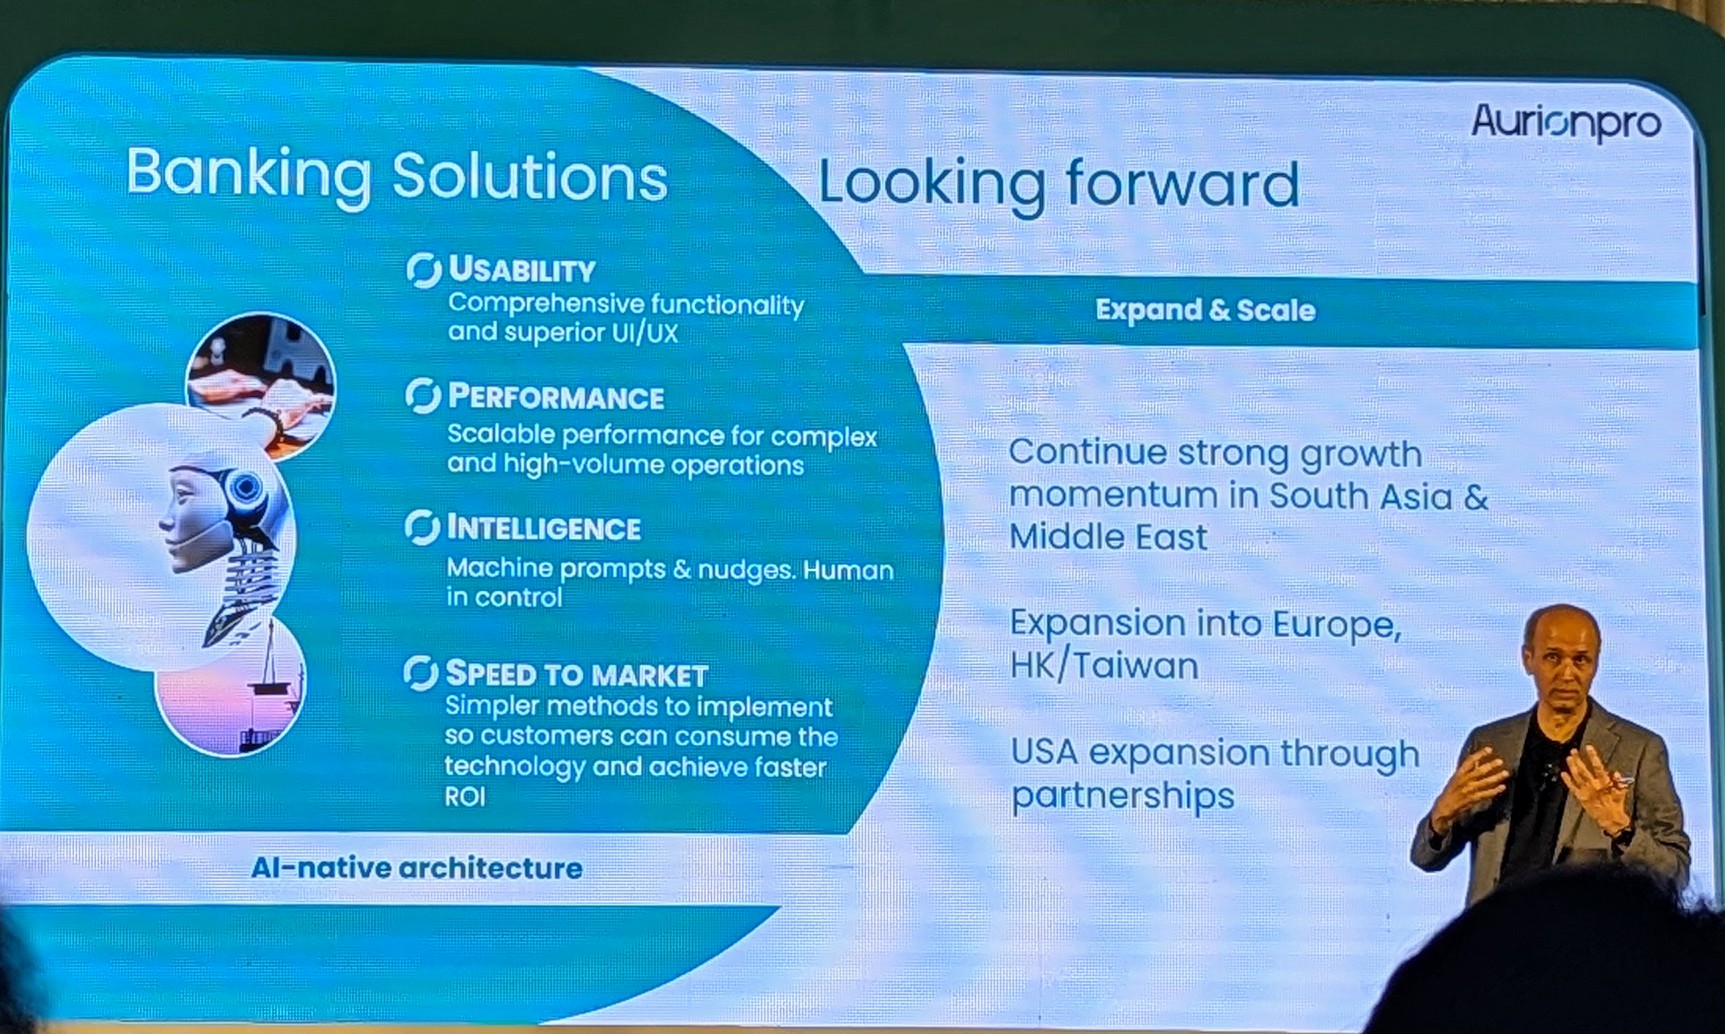
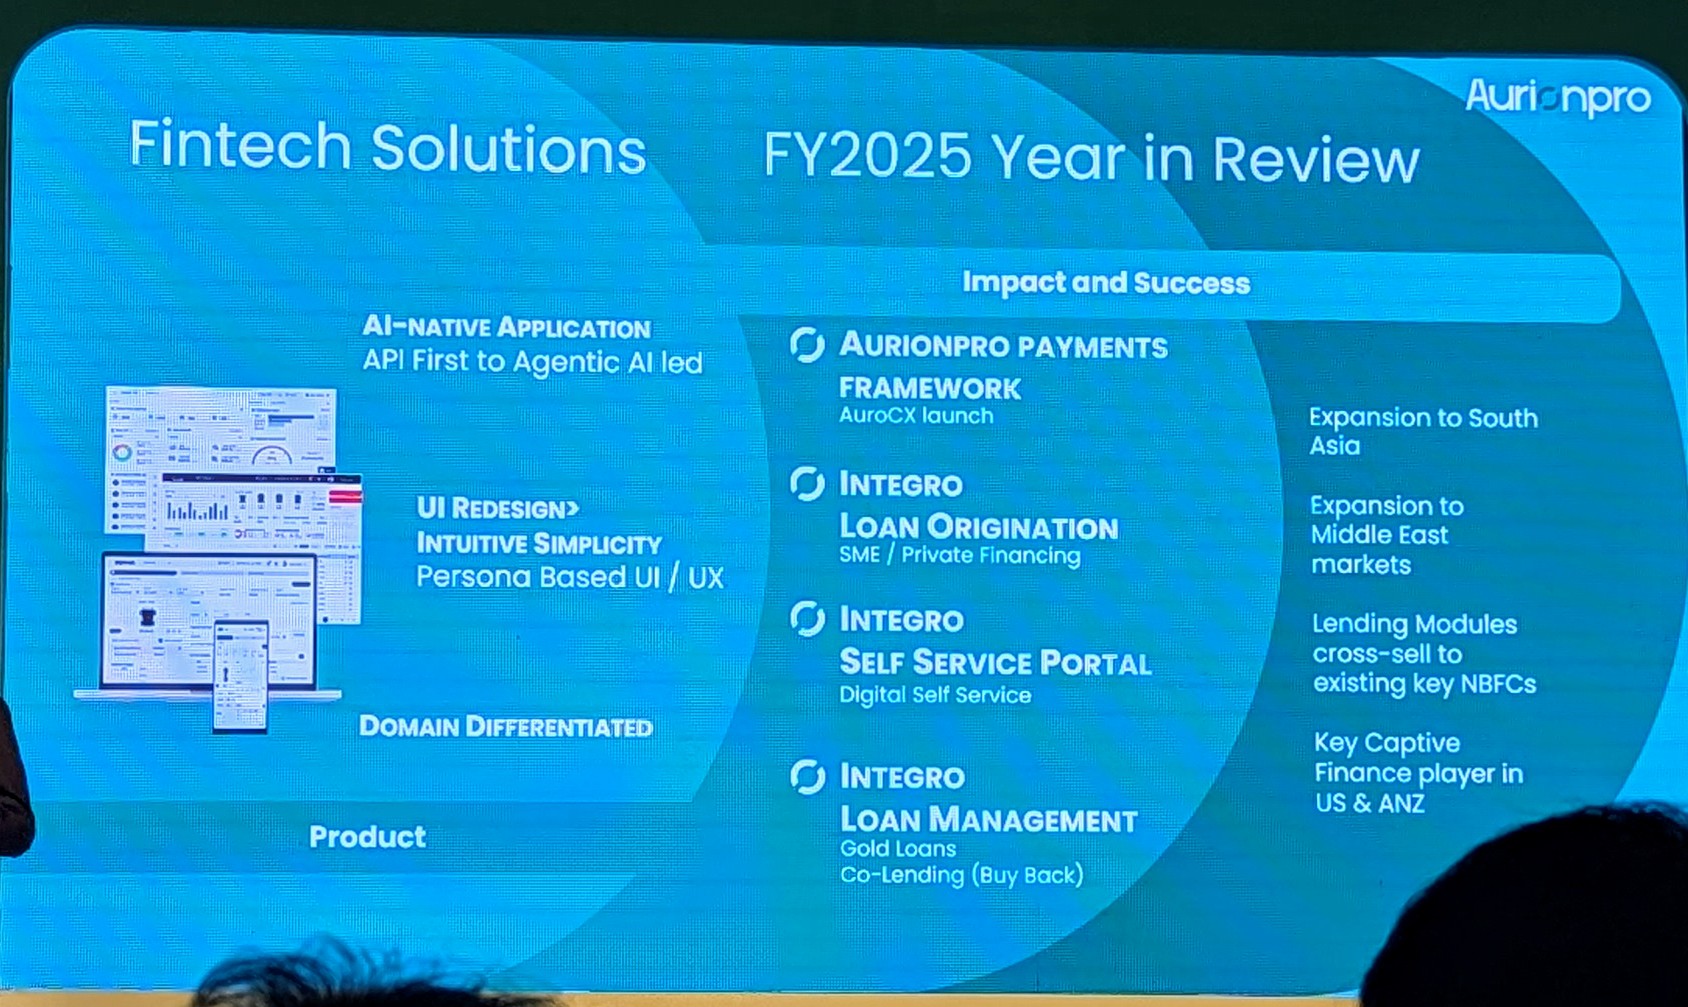
Aurionpro conducted its Investor Day. I feel they are on a solid growth path. Strong IP led solutions for banks, expanding in their home territory of Asia and also focusing now on GCC countries (new office in Saudi) and Europe (powered by the Fenixys acquisition). Arya.AI is letting them bake AI smarts into their applications and venture into enterprise AI.
5 Likes
MONARCH BUY TGT2050 JUNE 25.PDF (644.6 KB)
DISCLOSURE INVESTED SINCE LAST 2 YEARS WITH NO SELLING
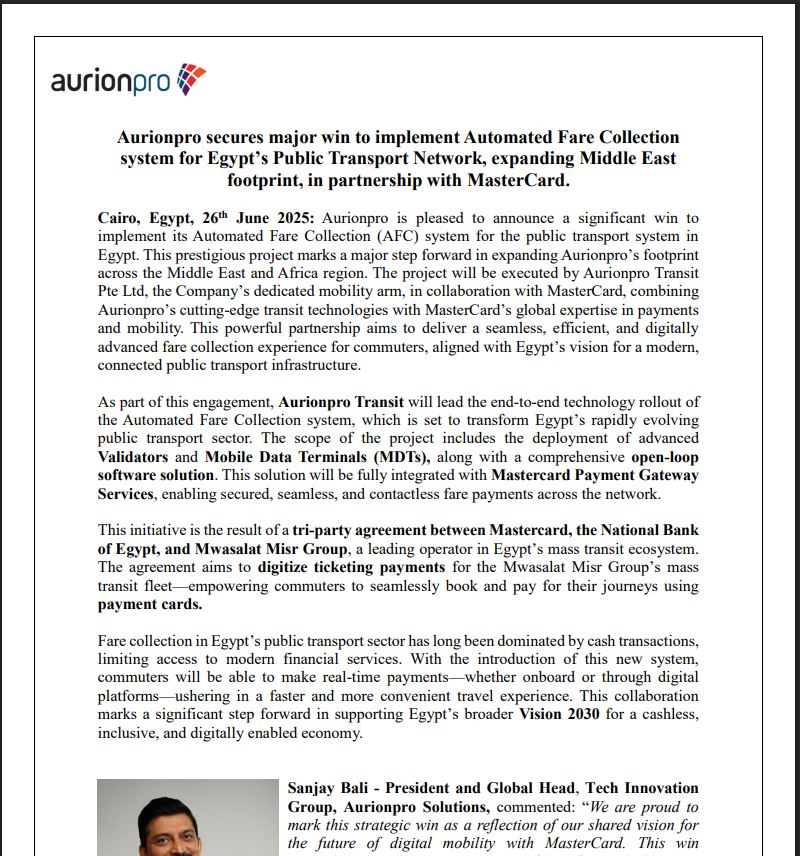
![EGYPT NEW ORDER TRANSPORT MASTERCARD PARTNER|467x500]
(upload://7RPnGr4lcHgEeo8O4Boq9HXvJr2.jpeg)
BIG WIN IN NEW GEOGRAPHY IN PARTNERSHIP WITH MASTER CARD FOR TRANSIT SOLUTION. OPP SIZE KEEPS INCREASING AND SIMULTANEOUS BEAUTIFUL EXECUTION UNDER DYNAMIC CEO ASHISH RAI AND HIS TEAM OVER LAST 4 YEARS
2 Likes
big step in expanding in new geography like EU & west with promising AI vertical
good execution continues
Aurionpro Solutions Secures Breakthrough European Deal.pdf (729.0 KB)
8 Likes
Decent results announced by the company yesterday. In addition First interim dividend @ Rs 1 per share has also been announced. Media release attached which reflects an extract of the results. Let us now await the conference call where further clarity on the future of the company will emerge.
Aurionpro Solution.pdf (529.7 KB)
2 Likes
What am I missing in the Q1 results?
I found the results to be pretty nice, given the uncertainty in IT and little to no growth shown by other companies, but -7% fall after the results, not able to understand what triggered it.
Probably decreased PAT margins is the reason. Please share your inputs.
There could be several factors, market may not like:
- Low ROE
- Margins getting squeezed due to various factors
- Topline growth is slightly below the expectations
- Dependence on inorganic growth path
- Growth challenges in near future term
- Sector sentiments
3 Likes