The promoter has given the parent company an interest free loan, which in turn has given interest free loan to Humro. At some point in future, Humro will convert that loan to equity and the parent company will get additional shares, so ARAPL’s holding will increase in Humro. Further, ARAPL will also convert the loan given by promoter in equity shares, here the retail/non-promoters will get diluted. Its going to be a difficult jouirney holding ARAPL. Their legacy business is not growing, is pretty lumpy, they are now attempting to export car park solutions (not sure if that is a good move, is there really scope/demand for it?), surprisingly robotic welding business is not growing. Turning profitable is good, but should stay profitable.
Humro has struggled to scale up.
Another “soft signal” which I didnt like was that this time they limited the call to striclty an hour, whereas previously Milind always used to ensure that all the paticipants queries are addressed, even if meant going beyond an hour.
Now promoters are saying fund infusion in parent entity through preferential or rights. I suspect the promoters could do rights and not participate further trapping minority investors.
the true intent of the promoters will be seen soon. lets see if they do a preferential and put money themselves or trap minority investors once again.
I suspect that this will be a preferential issue to promoter in-lieu of the interest free loan given to the company, so yes, retail investors will get diluted further. The listed entity as well as the subsidiary, both recently raised funds, and they havent utilised so far I believe, so they shouldnt be in need of additional funds so soon.
Ok so promoter stake will go back up in the listed entity but what does this mean for the loan given to the main subsidiary? Why isn’t that also an equity transaction? If the parent did an equity investment in the subsidiary then humro would have still been a subsidiary and not a Jv/associate like it is now.
I wonder if management will convert the parents loan in humro also to equity. But I don’t trust this management so don’t have any expectations of them doing it.
I won’t be surprised if management stops doing investor calls soon. if they don’t increase the company stake in the subsidiary, at some point they will get questioned by everyone. and they may just stop doing calls so as to not deal with the headaches of explaining to investors their wrongdoings.
If you read their release, they had clealy mentioned by the company that a 13 crore order, that was supposed to be release in Q1, got delayed Q2 and the cost has already been incorporated in Q1 numbers.
Invested since 2022 , management words always get deffer. always misses their target. On top of that arapl raas not going to a subsidiary after the fund raise. emerging sector but no clarity . opted out this quarter.
may the business flourish and do well , but to much red flag for me .
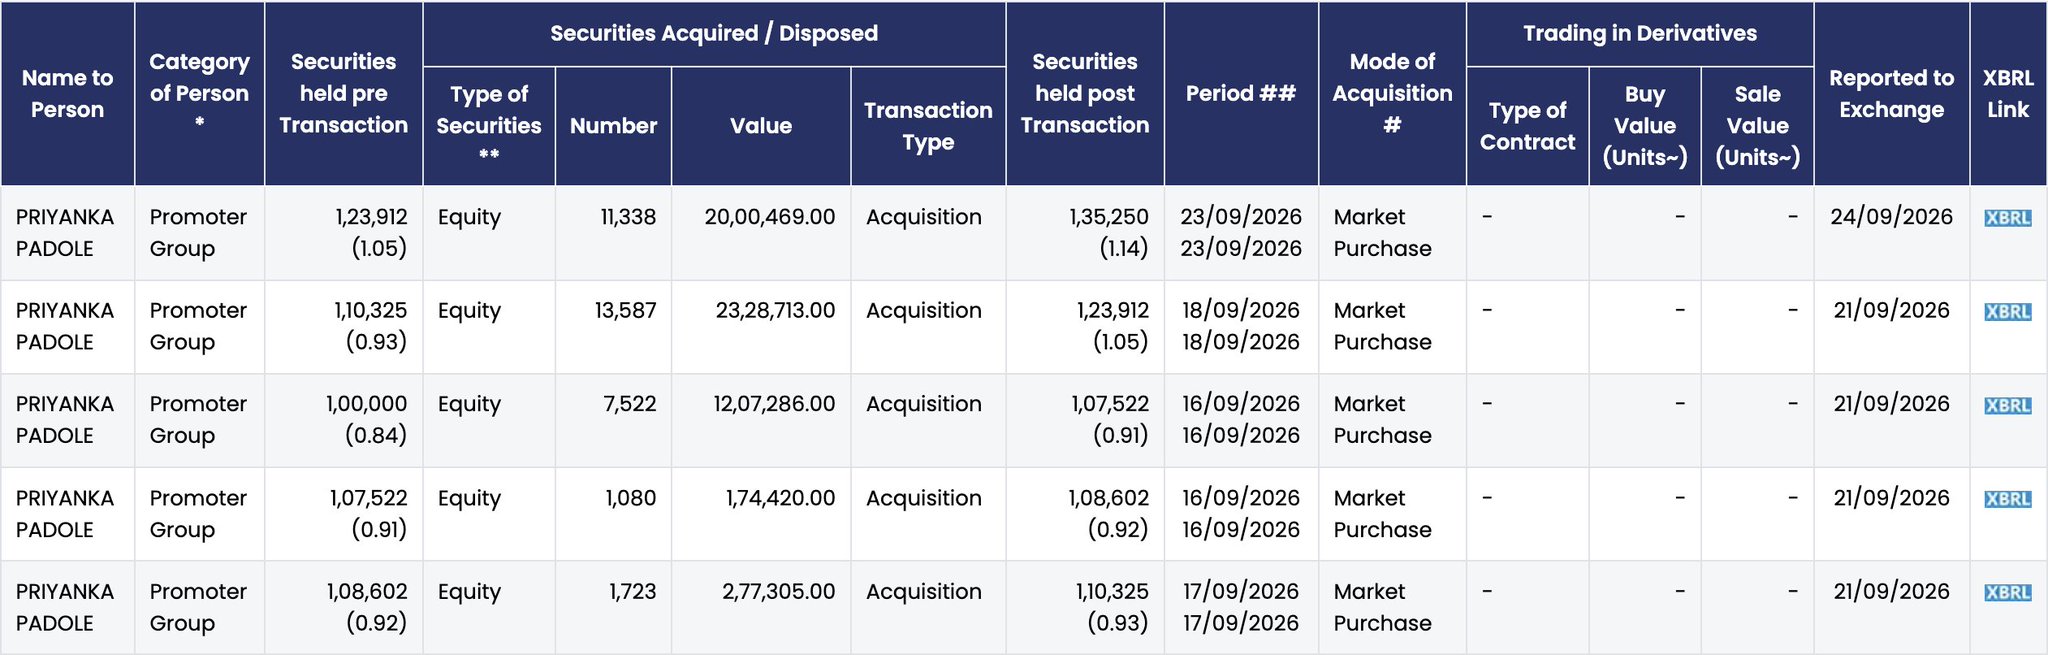
Promoter Group is increasing its stake through open market purchases and by converting convertible warrants into equivalent equity shares. The total increase is around 4%.