
Still that would be considered as source of working capital only need to ask management as it’s not just for FY26 they have been doing this from a very long time atleast from FY 22 as I have not gone beyond FY22
1 Like
Did this correlation of permit data and revenue also stood in previous FY? Also in other companies?
I would have cross checked them both but i am not able to find older data. I can only see the current half yearly one on the site. If you checked kindly share your findings
So the thing is vintage coffee was not in the top 20 exporter and hence there is no data for last year. You can cross check with Q4 data and it matches but yeah that is tha.
1 Like
What is the source of export permits for June for Vintage coffee ? There were no company announcement I could find. Further, would you know the profile of customers they supply to ? Are these brand owners or overseas distributors?
1 Like
Does anyone know what is the impact of rising prices of coffee on Vintage Coffee…?
Click on Export info.
1 Like
higher realization but same margin
1 Like
Updates estimate for Q1 after Coffee board data upto June 30 and discussion with people from the coffee industry.
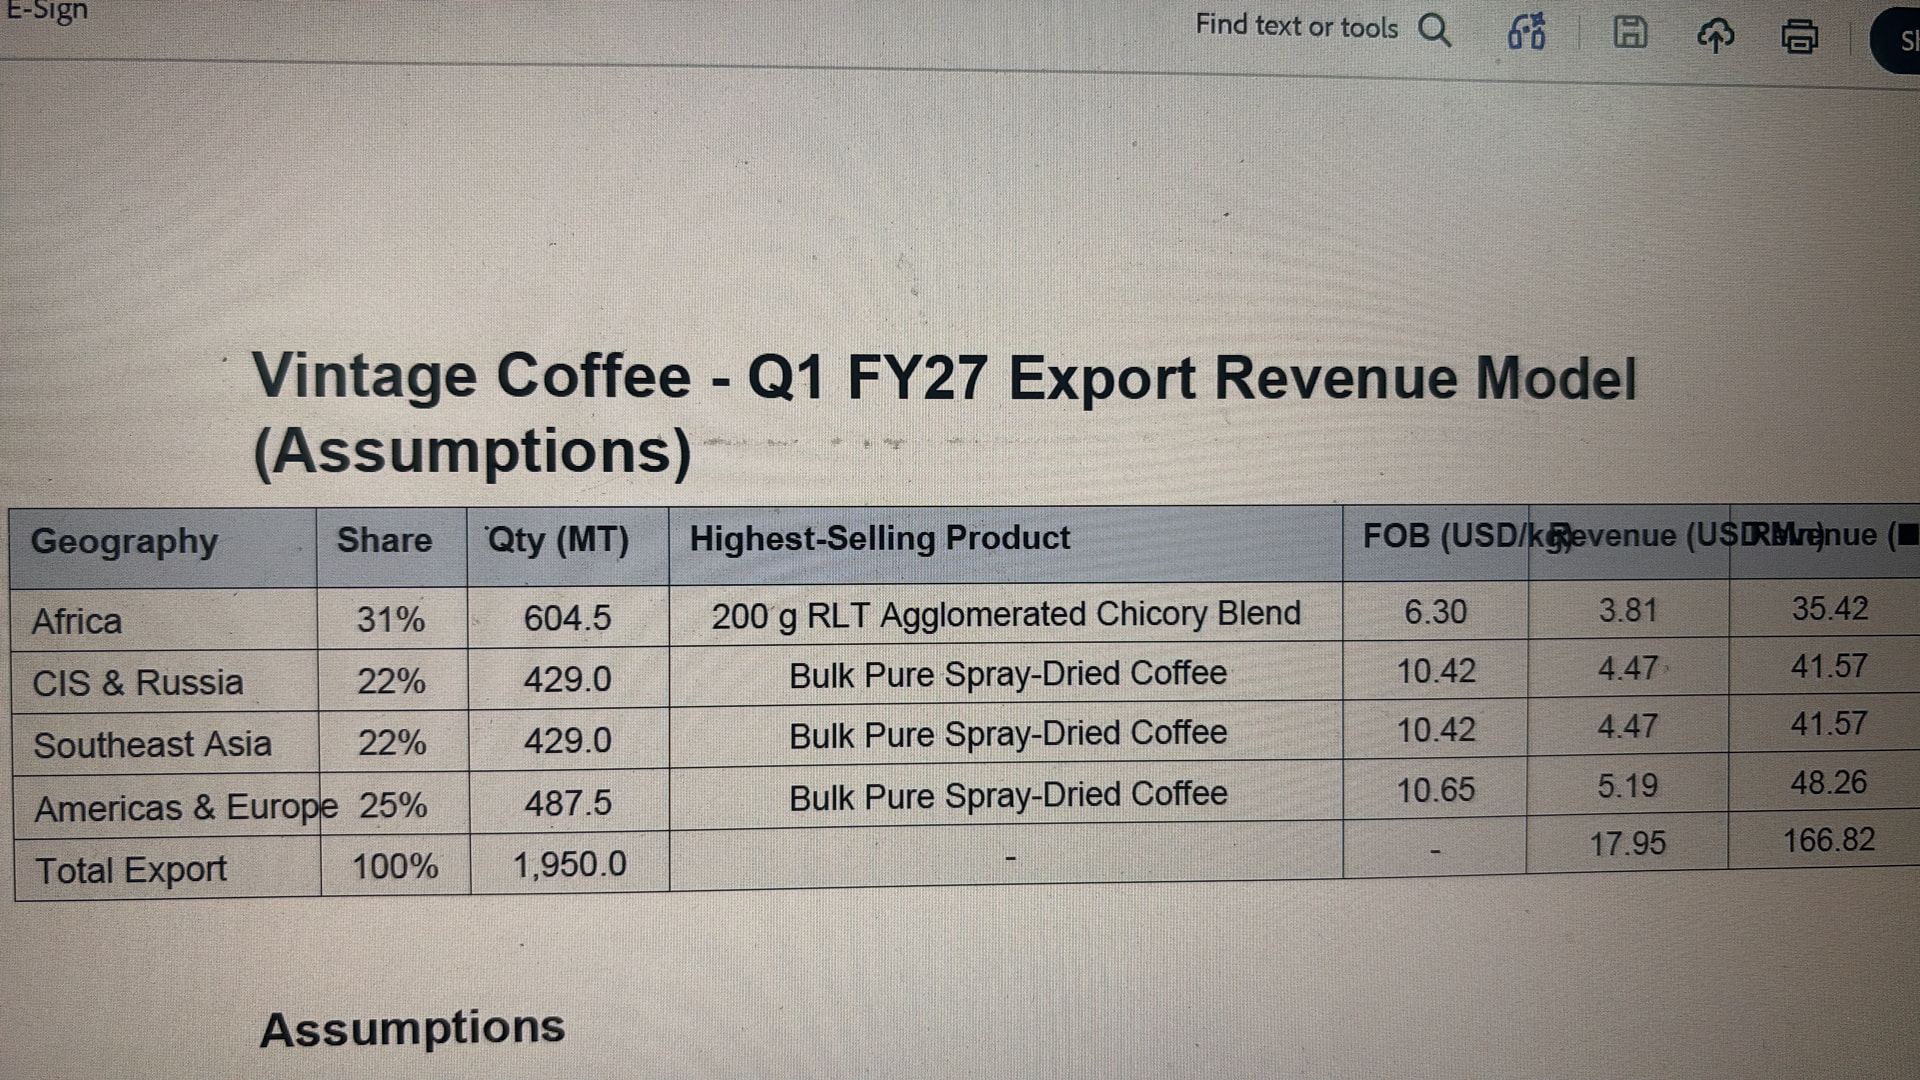
The most important assumption here is that, since I don’t know the bifurcation of product in each geography I am just using the highest selling product as the only product for that geography.
This is only for export.
Domestic sales will be an add on for this number
1 Like
Vintage Coffee reported its Q1 numbers, which received a mixed reaction from the market.
The numbers, however, were quite strong:
• Revenue grew 58% YoY
• EBITDA grew 75% YoY
• PAT grew 46% YoY
• There was no growth on a QoQ basis
Management had clearly stated earlier that Q1 is generally a lean quarter. Perhaps the market was expecting stronger QoQ growth, which could explain the reaction — though, IMO, it was unnecessary.
Meanwhile, Coffee Board export permit data till 28th July shows volumes of 635 MT.
At the current run rate, Q2 volumes seem on track to reach ~2,200–2,300 MT.
Q1 was strong, and Q2 seems to have started on a healthy note as well.
Disclaimer: Invested.
6 Likes
Hi, thanks for the updates. I just had a few questions since you seem to understand the business a lot better than I do -
- What do you think revenue for FY27 and FY28 is going to look like?
- What are margins going to look like?
If I build in a 30% revenue cagr for the 2 years and keep margins where they are, there seems to be a good 40-60% upside from current price levels.
Tried to develop rough projections, consider referring the revenue assumptions, looking forward to suggestions, improvements and dialogue
Disclaimer - Personal activity - does not represent an institution work
1. Vincoffee Fin Model_v3.xlsx (178.5 KB)
2 Likes
Potential governance flag (Aug 19): A 12Cr deviation in preferential-issue fund utilization, money raised for stated “plant and machinery upgrades” was instead used to purchase land, without shareholder approval before the fact. Management’s stated reason is “operational efficiency,” but this is exactly the kind of disclosed-after-the-fact capital-allocation deviation that raises eyebrows, it’s a smaller-scale echo of the same pattern that made me cautious on Sigachi’s warrant dilution, where money was not used as originally promised to investors. I hope they don’t repeat this.
3 Likes