Been finding it difficult to value and find logic in valuation of holding companies. Take any example say JSW holdings with a m-cap of ₹12k cr with holdings in other JSW companies, the worth of those stakes and holdings is around ₹23k cr. I’m aware of the holdco discount concept but logically doesnt make sense, does anyone agree?
But there is market wisdom baked into this. Not all are same, but the market treats them similarly. Read this SEBI order, very recent one - SEBI | Order in the matter of Nalwa Sons Investments Limited , but relates to a matter 12 earlier, involves 2 listed holdcos. Think to the time and the value lost in those years.
Holdcos you need to be very selective. Understand management responsiveness or intent, and then act. Value unlocking is all on management, get that step wrong and its over.
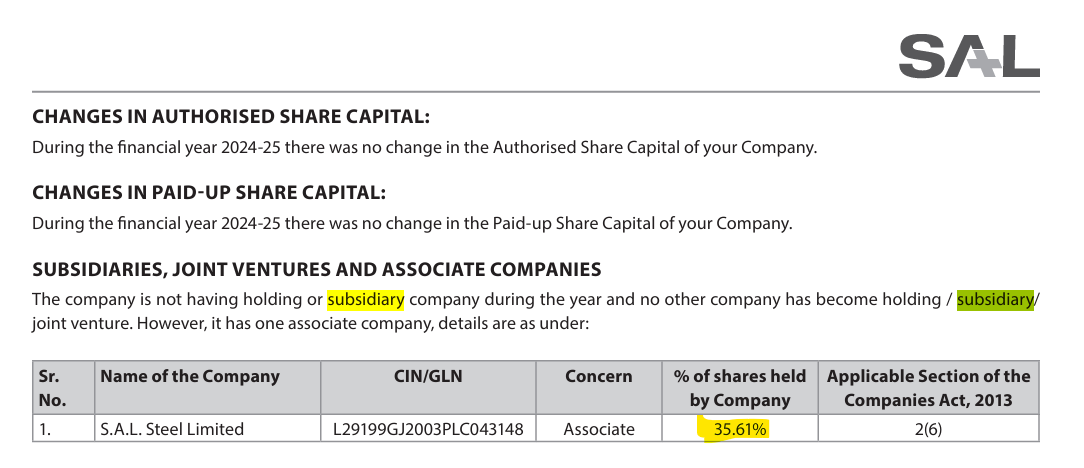
Thanks but still trying to understand the logic or the market wisdom here, for pure play holdcos how come their market value is any different or worst even less than the market value of its stake in subsidiaries. There are several examples – SHAHALLOYS for one, has ₹58cr mcap with stake in subsidiary worth ₹124cr.
I tried to make a point trying to explain the same.
Its not always mathematical, majority of the times it is sentiment driven - just like the stock market.
Market doesn’t like uncertainty.
With holding cos the main issue is uncertainty.
You are valuing the company by underlying asset & trying to correlate that into the price.
But we often forget that the value gets only realised if they are to sale their stake & than distribute it to Preference shareholders & ordinary shareholders.
The uncertainty part is , no one knows when the value unlock would happen and therefore the holding cos discount.
There are other factors which can be added, but the above one is the major for such discounts.
Consider this, if you own a million dollar house that you live in, you are a millionaire on paper but do you really feel like a millionaire?
Similarly, Holding companies mostly hold their in house assets which they are unlikely to sell and if they don’t get strategic buyer, the price will fall if they decide to sell (just like any other promoter selling their stake in open market). Hence the discount will remain mostly, but sometimes you do get opportunity, case in point Tata investments (I played this and was lucky to get 2x return) but its not always the case, most of the time discount persists unless there is an outlier in underlying holding
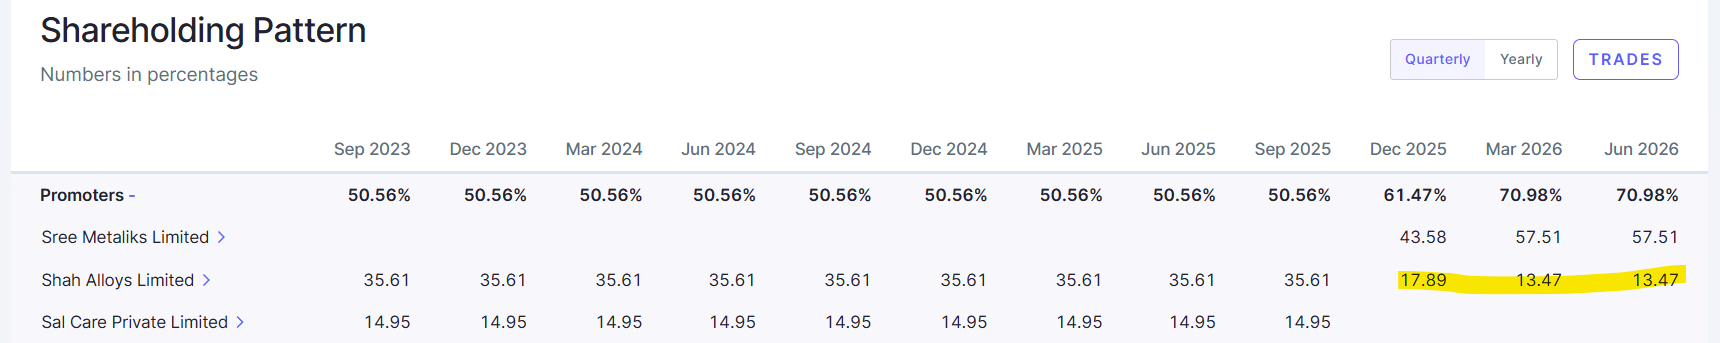
As of today, SHAHALLOYS has 35.6% stake in SAL Steel. SAL steel MCAP is 899cr (Rs.62/share). This translates to 320 Cr value for the 35.6% stake. SHAHALLOYS MCAP today is 132Cr (Rs.66/share). This is ~60% discount.
Questions to ASK - When will SHAHALLOY give me this 320Cr into my account? Does this possibility exist? What is the possibility that this value will go up or will go down in the future? Will SHAHALLOYS shareholders have a say in how this associate company (not subsidiary) executes its operations in the future? And many more questions.
100 people are going to answer these few questions differently. Based on their answers they will bring a discount or a premium.