You have captured the short-term emerging pressures very well. I would like to add a complementary perspective considering the current market valuation P/B ~0.8-0.9x) and the medium-term setup:
Net yield compression and rising GNPA/NNPA are real. Profitability metrics like ROA (2.4%) and ROE (8.7%) have dropped sequentially. Emerging market portfolio stress (expected GNPA of ~4%) is indeed a red flag to monitor carefully.
At 0.8-0.9x Price to Book, the stock is now trading close to historic trough valuations seen for growing NBFCs in early-cycle phases. Even lower-quality NBFCs with inferior underwriting standards often trade near 1x Book during stable growth phases. UGRO’s core MSME segment and secured lending expansion (especially Micro Enterprise secured portfolio) could stabilize yields and support future profitability, although with a 2–3 quarter lag.
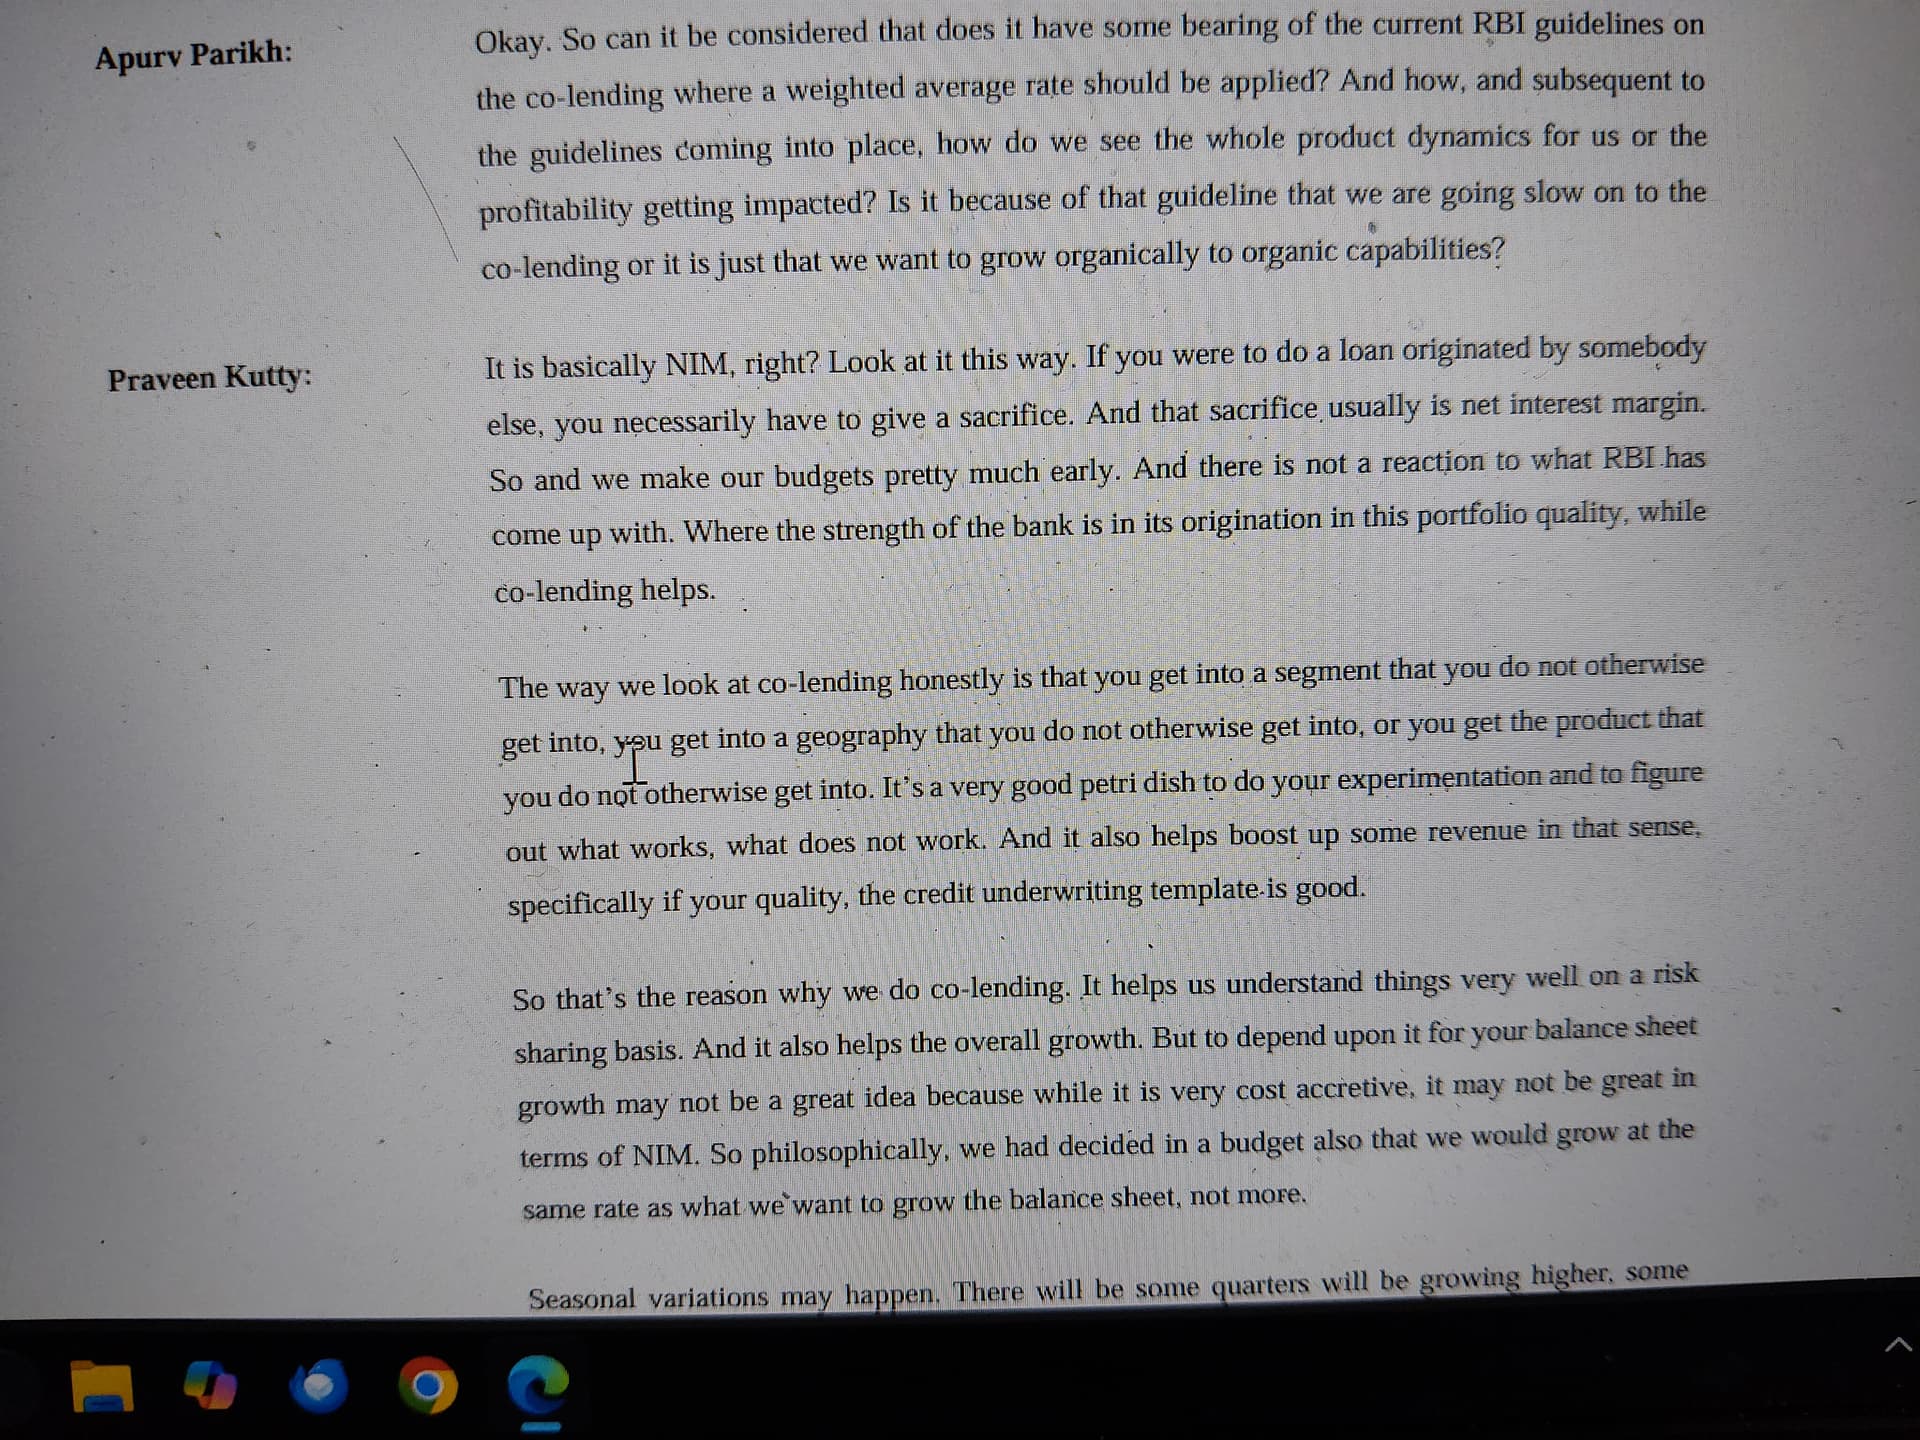
Operating leverage will likely kick in once recent branch additions (100+ branches in FY24) start breaking even (guided breakeven within 8–9 months). Embedded finance and co-lending model, although riskier, gives UGRO flexibility to improve ROA with low incremental equity requirement. Capital adequacy remains strong (>23%), so no immediate dilution risk exists. Management still guides for 16–20% ROE and 3.5–4% ROA targets by FY26–FY27, albeit with execution risks.
Key risks to monitor are: GNPA trending above 4% and credit cost >3% would structurally depress return ratios; rising competition in MSME secured lending could lead to further margin pressures; and if Emerging Market portfolio slippages aren’t contained, growth alone won’t rescue valuations.
At current P/B, much of the stress in profitability and asset quality appears factored in, unless asset quality worsens materially beyond management’s guided ranges. UGRO Capital today represents a classic high-risk, high-reward setup: if execution improves (credit costs normalize, branch productivity improves, ROA scales towards 3%+), re-rating to 1.5–2x P/B over 2–3 years is quite achievable. If execution falters (sustained GNPA spike, poor cost control, further ROE deterioration), valuations could stagnate or worsen.
While caution is warranted looking at short-term deterioration, the risk-reward at current book value is skewed positively for patient investors who can track quarterly metrics and adapt if asset quality signals deteriorate further.
 ) in the small NBFCs.