Trishakti Industries (TIL) first caught my attention by happenstance. I was looking at the infrastructure picks-and-shovels plays in Eastern India and chanced upon it.
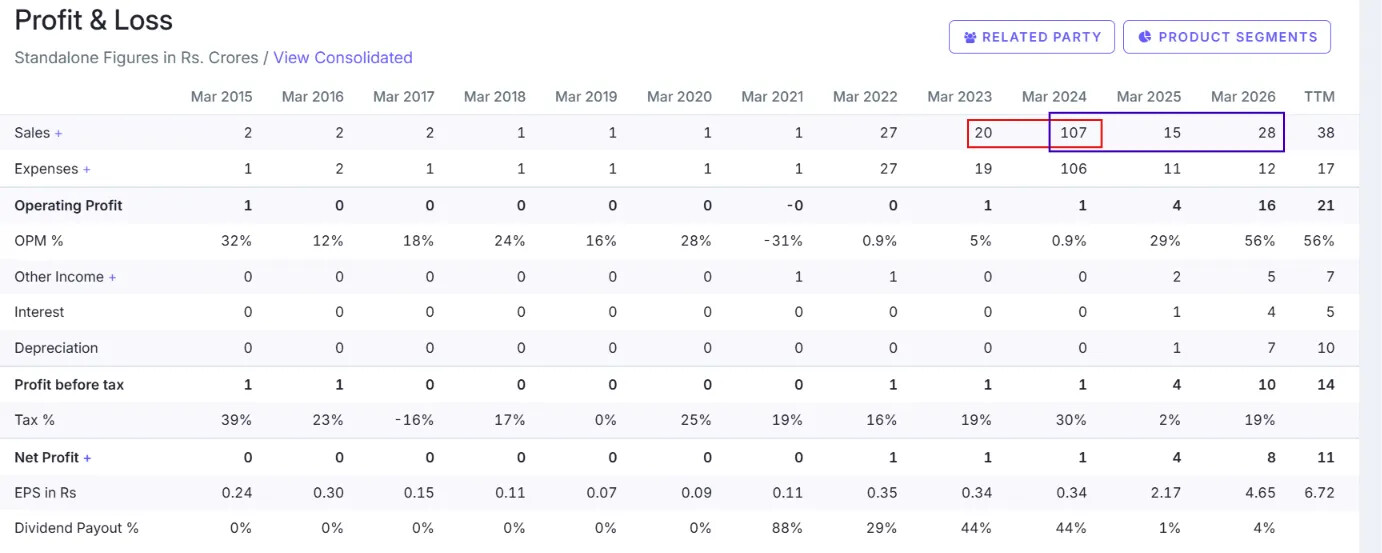
At first glance, the company looked like it was transitioning from one business model to another. The P&L was a testament to the transition where 2024 was the year when the legacy business was sold off and the new business started in earnest from 2025.
Business Overview — What Does Trishakti Do
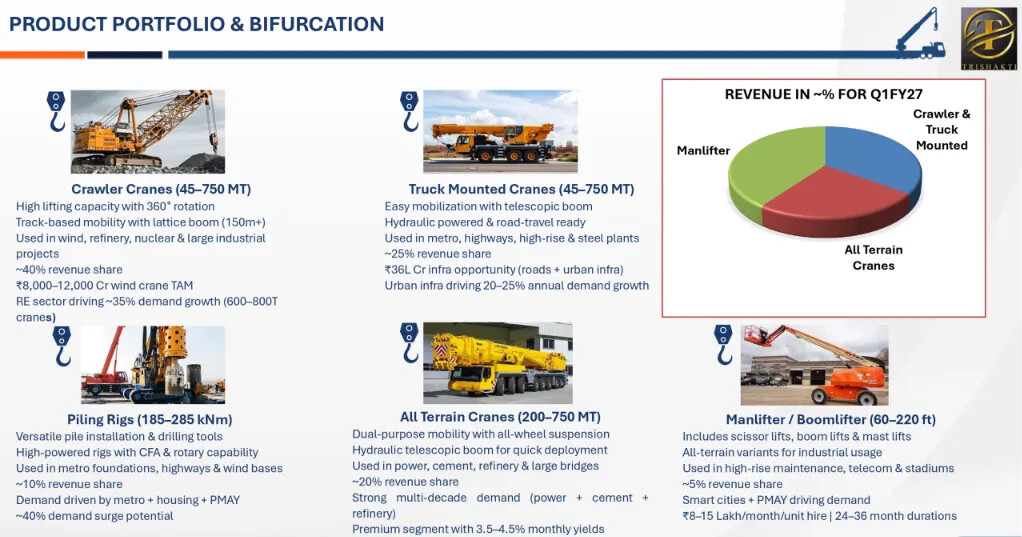
Trishakti is essentially a simple business. It buys heavy equipment like cranes, piling rigs, manlifters (upto 750MT) and then rents it to large infra players. In that sense, TIL is a smaller version of Sanghvi Movers. Their customers are typically bluechip construction and industrial companies like L&T, Reliance, RVNL, ONGC, Cemindia Projects (ITD Cementation), Adani Group, KEC Industries, Jindal Group, Tata Steel and NCC.
The business has a few important considerations:
-
How good and efficient are the assets (cranes, lifters etc)?
-
How productively can they be employed (capacity utilisation)?
It is a function of how old the machines are and how frequently it needs maintenance and how efficiently you can find clients who need the services of the machines)
The entire operations and maintenance of the equipment lies with TIL. This is what helps create a high operating margin business (OPM - 56%, NPM - 27.5%). The other big advantage for TIL is that all their equipment is new since they started in 2025. This means their downtime is low, leading to a Fleet Utilisation of 100%.
With renewables at the forefront in India, TIL supplies 48% of its fleet to wind and solar projects mainly for installation purposes.
What makes this business slightly difficult to enter for others is:
-
Capital-heavy business with a heavy crane costing between ₹5-50 crs
-
OEMs (equipment manufacturers) make very few machines and there is always a wait time (3-6 months) for the availability of machines.
-
Large bluechip clients have a strict vendor approval process. Once approved, typically repeat orders do not need fresh bidding.
-
Operating heavy cranes (100-750MT) takes a skilled workforce that is not readily available.
-
Most large clients look for younger machines. This is an advantage for a new company like TIL over Sanghvi which has a more ageing fleet.
A Brief History — From Electronics to Cranes
Trishakti Electronics and Industries Limited was incorporated way back in September 1985, listed on the BSE and the Calcutta Stock Exchange, and for over three decades did a bit of everything — electronics, general trading, and supplying drilling equipment to ONGC. No one really knows why this company was listed on the CSE in the first place.
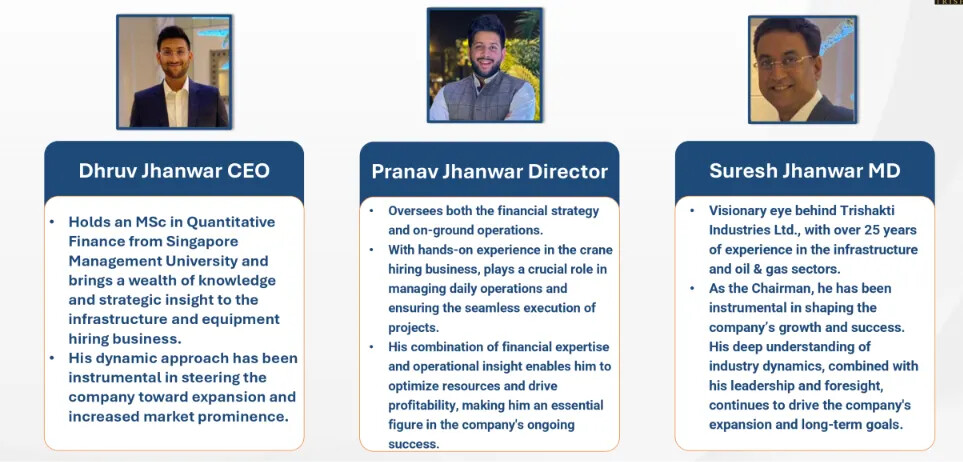
In 2025, a family settlement brought the current management to the forefront. They decided to focus all their attention on the asset-and-capital intensive heavy equipment rental business. Suresh Jhanwar, the Chairman, was supported by his two young sons - Dhruv and Pranav - in building this company.
Growth Prospects and Drivers
The management team led by Dhruv Jhanwar is very bullish on the prospects of the overall sector and is planning accordingly. They had a target of 150 machines by 2027, which they have now upped to 200+. Similarly, in 2026, instead of a planned capex of ₹100 crs, they have deployed ₹210 crs. TIL has also signed an MoU with XCMG for wind-energy equipment worth ₹125 crs.
In FY26, TIL had revenues of ₹28 crs. Management has projected revenues of ₹60–65 crs in FY27 and ₹90–100 crs in FY28. The operating margins are expected to remain stable or improve with better operational efficiencies kicking in.
The company has also decided to enter Saudi Arabia and the UAE. Management points to a Saudi infrastructure pipeline worth over $1 trillion and a crane rental market there already north of $1 billion, growing 10-12% a year. This is currently still in the planning stages and no firm orders are in place.
Risks Worth Considering
The company is highly levered. It has a debt-equity ratio of 1.9, though part of it is loans from the promoter. Remember that high debt exacerbates all problems. Going back in history, cyclical, capex-heavy businesses get into trouble when they have excessive debt and demand collapses for some reason.
The overseas foray could be a double-edged sword. It will test the management bandwidth when it is already growing within India at a scorching pace.
The utilisation is maxed out. Any reduction in the efficiency of asset deployment will impact results.
Infra buildout is primarily happening as part of a large government push. With the central purse already stretched due to oil & gas subsidies and welfare schemes, continued infra spending should not be considered a given.
TIL’s orders are currently skewed towards the renewables sector - 48% come from this. Any change in policy can impact results disproportionately.
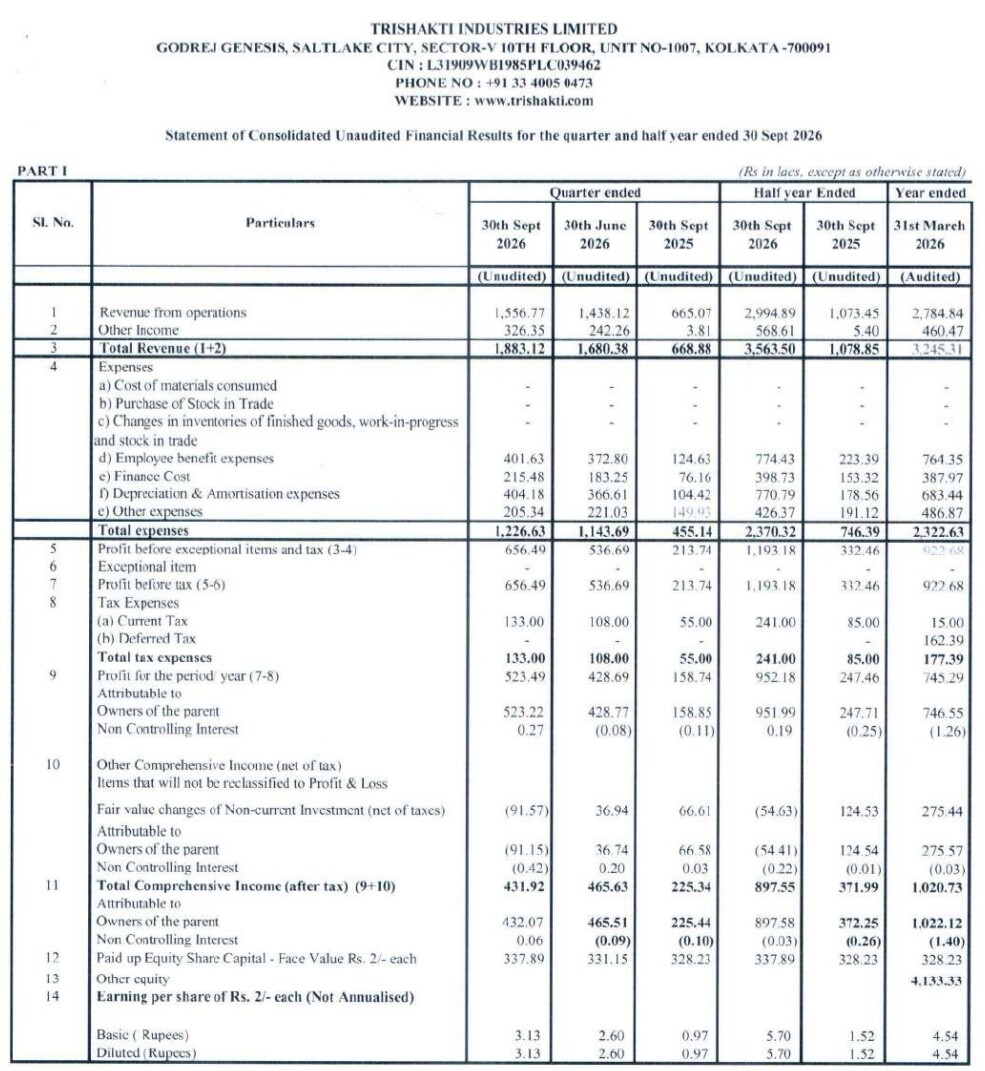
A deep dive into the Cash Flow Statement shows an increase of ₹147.47 crore in Other Current Liabilities, specifically ₹146.10 crore of Expenses Payable on account of Capital Goods. This implies that the company acquired its equipment without paying the suppliers upfront. These unpaid supplier liabilities are distorting operating cash flow.
The Debt-Equity ratio reached 1.9. When supplier credit for equipment is considered, total external liabilities (about ₹231 crore) exceed the company’s net worth (~₹44–45 crore) by more than 5x.
Debtor days are ~200 days. This needs close monitoring, as management claims it works only with Tier-1 clients. For reference, Sanghvi Movers has debtor days of 92.
Three company secretaries have been appointed in the last 2 years (due to resignations of the previous two CS’s).
Bottom Line
Trishakti Industries is a small, niche and nimble player trying to make its mark in a difficult capex-heavy cyclical business. It is being led by young and passionate next-gen leadership from the promoter family. Growth has been stupendous. Risks continue to be prominent. In the end, if the company is able to execute well and the focus on infrastructure buildout continues, it can reap rich rewards.
SEBI MANDATED DISCLAIMER:
Intelsense.in is owned by Cupressus Enterprises Pvt Ltd (SEBI Registered Research Analyst) with Registration No. INH000013828
Research Analyst or his associates or his dependent family members may hold a financial interest or actual/ beneficial ownership in the financial products/ securities advised herein.
Investment in the securities market is subject to market risks. Read all the related documents carefully before investing.
Shree Rama Managers LLP is a SEBI-Registered Portfolio Management Services Company (SEBI Reg. Number: INP300007341).
Stocks discussed, if any, are for EDUCATIONAL purposes only and should NOT be construed as investment advice.
Please consult your financial advisor and do your own due diligence before investing.