
About-
-
The co. is a precision engineering manufacturing co.that makes crushering, screening, washing equipment which are used in all kinds of infra projects, for the mining sector, waste recycling, waste water management.
-
Products- [image]
-
The co. was incorporated in 2010 with the name Rashi Resources Pvt Ltd and changed to Taurian MPS in 2022 via a special resolution.
IPO details-
-
The co. got listed in SME Emerge platform in September 2025, 100% Fresh Issue for ~42 cr at a price of ₹171. The co. got listed at ₹210 at ~187 cr.
-
The management diluted its stake from ~89% to ~64% (no selling).
-
The proceeds were used for machinery acquisition, R&D, working capital requirements.
Promoters-
-
The co. is run by the mother-son Bajla duo: Yashvardhan Sumit Bajla (Managing Director, aged 24) and Puja Sumit Bajla (Non-Executive Director, 49), together with three family-owned private entities.
-
Links related to promoters- Yashvardhan- LinkedIn
[Vinod Modi, CFO- LinkedIn](https://www.linkedin.com/in/vinod-modi-7294051/) -
The co. appointed Dushyant Baniya Chief Manufacturing Officer (CMO) in July, 2026.
-
The co. did a preferential issue (~24 cr), issued convertible warrant (~35 cr) in August 2026 at ₹419 for capex & working capital needs.
-
There are some related party issues like purchase of fixed assets, loans from & to KMP/ group entities but that was before the IPO and no new annual report after the IPO.
-
The auditor resigned in April 2026, 7 months of listing citing low fees.
-
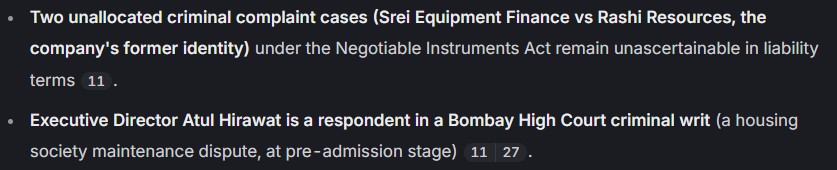
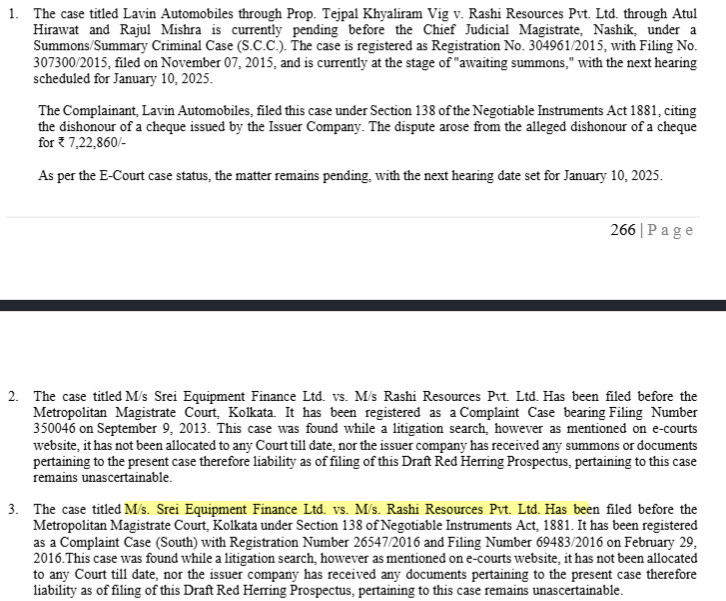
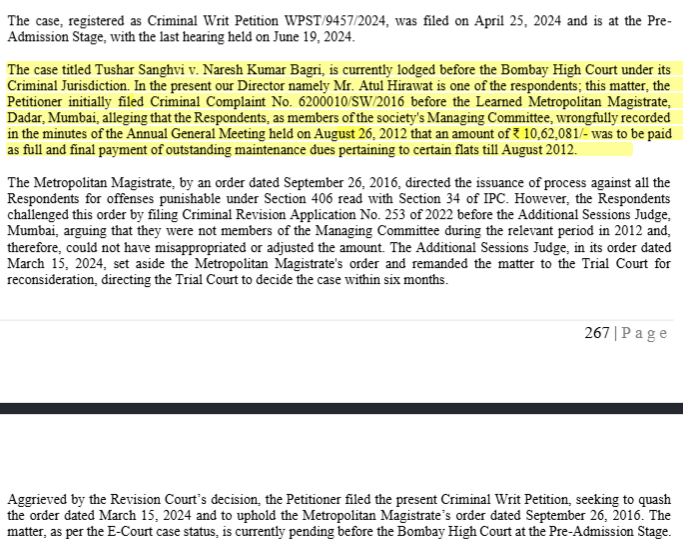
No criminal proceedings found against the promoters upon primary enquiry.
-
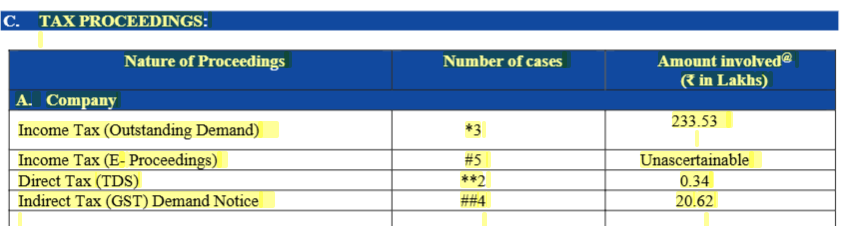
But minor tax proceedings found against the co.
-
Also minor civil litigations.
Some additional information-
-
The plant of the co. is at Roorkee, Uttarakhand.
-
The co. has 25+ dealers present in 20+countries. New dealers were added in Kenya, Ghana, Thailand, Nepal.
-
The co. supply its machineries to big MNCs like L&T, Jindal Stainless, Tata, Global Atomic, and companies within the ArcelorMittal group.
-
15-09-2026 would be the 1st anniversary of the IPO and hence lock-in opens on the date.
-
Order books are generally 2-3 months long.
Peers/ Competition-
-
The company mentioned Metso, Sandvik, Terex to be its international competition & Propel, Puzzolana, Hailstone to be its local competitors. (I will try gathering some sales figure of the competition)
-
Propel is doing almost 1000 cr sales.
SWOT analysis-
-
S- The co. has various products for various use cases.
100% in-house manufacturing. 10% revenue comes from spare parts/ after sales service. Slowly on-boarding Industry professionals -
W- Cashflow issues
High working capital needs- 2 dilutions within a year. Manufacturing on a single site. -
O- Presence in 20 countries
No big listed competitor in India. -
T- Some grey/red flags in management quality.
Latest result/ conference call-
-
The co. did 99 cr of sales, 16 cr of profit in FY26.
-
Big inventory jumped from 26cr to 47cr & receivables from 30cr to 49cr.
-
The co. utilised all of its IPO proceeds as on 31st March 2026.
-
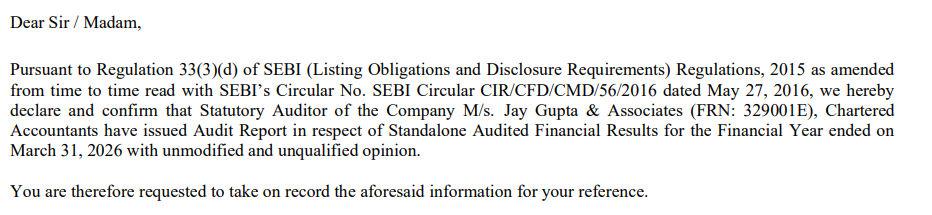
Unmodified, unqualified auditor report.
Sept 2025 conference call-
-
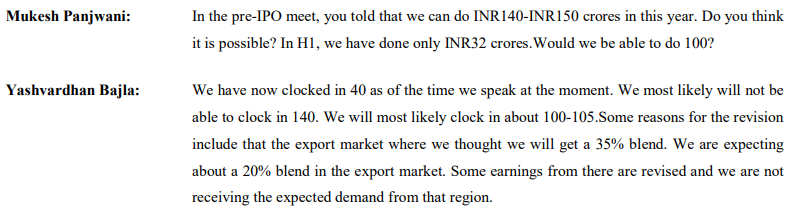
Guidance reduced from 140cr for FY26 to 100-105 cr.
-
Margin expectation of 16-18% (PAT margin).
-
Current capacity can clock upto 250 cr of revenue.
-
Industry is growing at a healthy 30-35%.
-
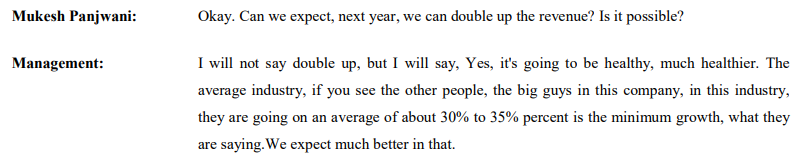
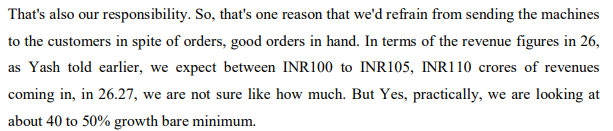
Will grow by minimum 40-50% in FY27.
-
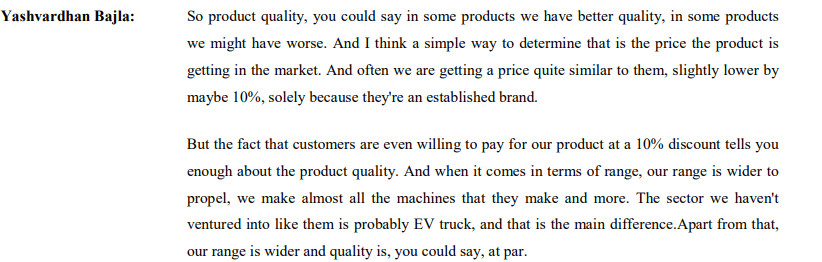
Difference from Propel-
-
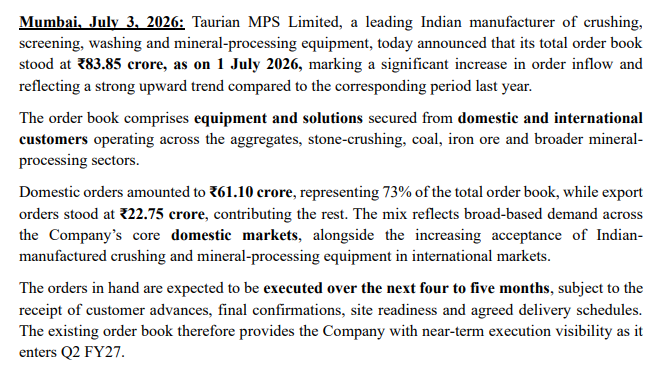
On 03.07.2026 media release, the co/ informed that they had ~84 cr orderbook to be executed in 4-5 months.
Valuations-
-
Tough to do valuation for a co. that doesn’t do regular conference calls or comes out with Investor presentation even after an annual result.
-
They also faluted from their Pre-IPO guidance.
-
So, if they do 40-50% growth at 16-18% PAT margin, forward P/E will come out to be at a range of 15-18 on FY27 forward at ~400 cr MCap.
So,the bottomline would be, Taurian MPS is an interesting engineering manufacturing co. with no listed peers with a lot of headroom to grow with issues like capital requirement for growth, no cashflow like any other small company.
There are some grey flags that were listed in DRHP which seems minor, but not ignorable nevertheless.
The current valuations are not that high but not doing regular conference calls is creating some smoke about the outlook.
Let’s hope the doubts get cleared on the EGM (scheduled on 20-09-26) & from the annual report.
** I am not a registered analyst and these are just my notes, not any recommendation, DYOR.
** I have no position in the co. as on publishing the report, but still consider me more/less biased but more importantly dumb.