

Enterprise and Data Center Vertical:
Sterlite Technologies focuses its enterprise vertical on providing specialized networking and connectivity solutions tailored for large businesses, like corporations and data centers, rather than just regular consumers or telecom carriers.
This vertical delivers high-speed optical fiber cables, structured cabling, and digital tools to help companies build reliable internal networks. It targets needs like fast data transfer in offices, factories, or massive server farms. Unlike telecom services for homes, enterprise solutions emphasize scalability for heavy daily use, such as handling huge data loads from AI or cloud computing.
To clarify, management has guided that 20% of revenues come from the Enterprise and Data Center vertical. Currently, Data Center revenues currently are almost negligible, with the majority stemming from Enterprise customers. The company is now undergoing customer validations and qualifications in the Data Center segment. They are in talks with all the 5 top global hyperscalers for their Data Center needs.
Hyperscalers have incredibly rigorous qualification cycles. They don’t just buy cable; they test for reliability, thermal performance, and ease of installation over 12–18 months.
Once a company like STL passes these customer validations, they become a preferred vendor. In the DC world, orders aren’t just for miles of cable; they are for entire pre-integrated optical solutions. This requires specialized products like high-density ribbon cables, which STL has been developing.
I think if STL successfully converts even two of the five hyperscalers they are talking to, that negligible revenue line could become the primary driver of their 20% vertical share within a few fiscal quarters. It shifts them from being a commodity cable provider to a strategic infrastructure partner for the AI era.
Currently the raw material prices fiber has gone 3x in china going towards 85% capacity utilisation for fiber.
STL Tech being the integrated player can enjoy the massive margin expansion over next year FY27.
One more optionality here can playout is ~
STLTECH being acquired by any other major Optical Player. (Gaining more market share, they have the capacities to cater to DATA Center demand )
All in all, It can be clean acquisition candidate as well !! 


Read This:
Optical fibre demand rising with global data centre & AI expansion.
~20% revenue from data centers → potential to reach ~30% in 12 months. Steady telecom demand adds visibility.
EBITDA margins may improve to ~19–20% (US tariff easing).
Weak base → potential strong PAT growth
Rising global optical fiber prices Export demand is also improving peers like HFCL are expanding capacity.
Main Risk: Rising germanium prices are impacting costs along with helium prices.
Positive on Strong play on global AI & data center cycle
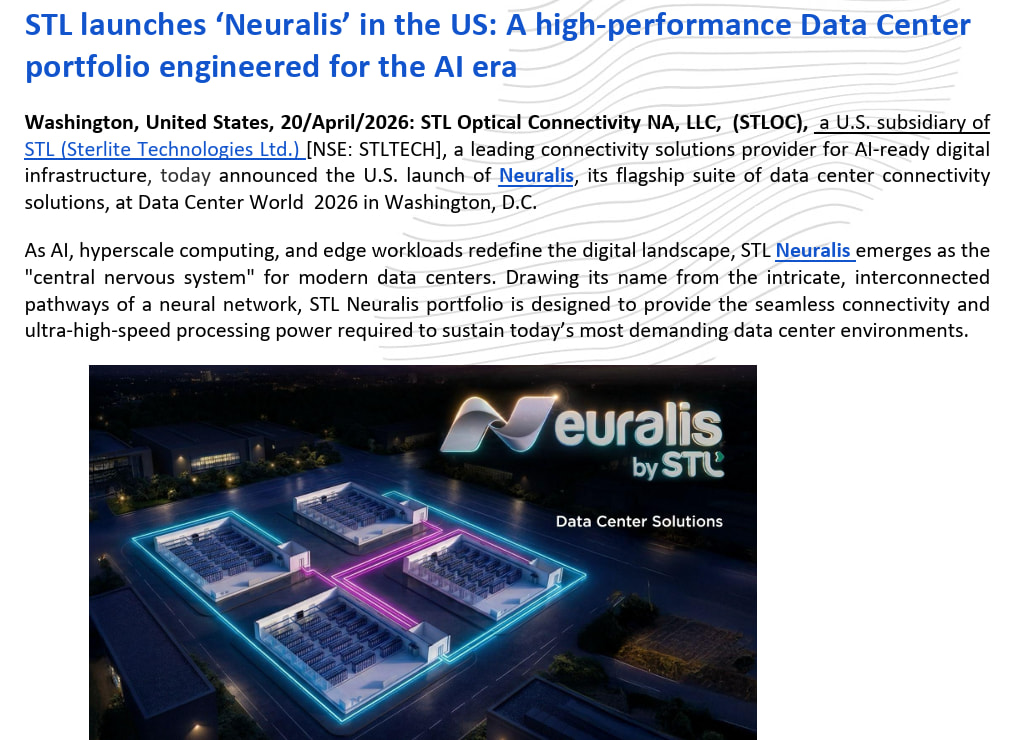
Source: Press Release
AI data centers require 36x more fiber than traditional ones due to GPU-heavy workloads, and STL is positioning itself as a vertically integrated partner in this niche.
Global optical cable demand is projected to grow ~76% YoY specifically from the data center segment, in 2026.
do you think the valuations have gone over the roof or it’s just a start?
its playing the AI wave so valuations wont matter till something drastic happens
Yes valuations won’t matter but it is in red hot zone, party and dance till the song is going on.
It almost gave me 107% returns, so i have booked out half personally because i didn’t expect such a parabolic move. This is looking like market frenzy; the stock may retrace back or Consolidate for earnings to catch up.
Don’t look at its P/E. Because STL’s earnings in the previous years were suppressed by high debt and industry headwinds, the current trailing P/E ratio looks astronomically high because the earnings are just beginning to recover from negative levels since last quarter.
Also in Q3, it saw a 40% YoY jump in order intake in North American Data Center Interconnect (DCI) wins.
So if you believe the AI infrastructure build-out is a multi-year cycle, this could be the start of a multi-year re-rating. Not at these fomo levels, of course. Wait for the cool-off.
Yes that’s what I am thinking
Looking at PE ratio is absurd way of judging but there is no margin of safety at current levels for short term as majority of short term business updates are priced in.
HFCL looks much better at CMP given it’s rally which was fraction of STLTECH and profitability has emerged for the company so it gives you more margin of safety.
How does finolex cables fits in current scenario ?.Available at cmp of 947 PE of ~ 21 and EVEBITDA of ~ 15.
yes it also doing backward integration as HFCL is doing but it is a small segment of their overall business.
and the family dispute problems are going on or not, we have to check that too because it can affect operations going forward.
Just because Sterlite and HFCL both make optical fibers, they are not in the same category at all!!
Optical fiber prices are through the roof mainly because of the critical component - Preform
Globally, only very few companies make Preform, Sterlite being the only one in India
Finolex is doing a small capex for preform, but it is miniscule compared to sterlite and also they don’t have anywhere close to the capabilities needed for higher speed optical fibers needed for AI data centers.
So, in short, Sterlite does not have any direct peers in India.
The global peers like - Yangtze, Furukawa, Fujikura, COrning (much bigger, not comparable) all have similar run in their stock prices.
Check the optical fiber prices and correlation with preform below.
Prices are up almost 3X in last 3-4 months and no signs of slowing down.
Optical fiber Companies which don’t make their own preform will not benefit much
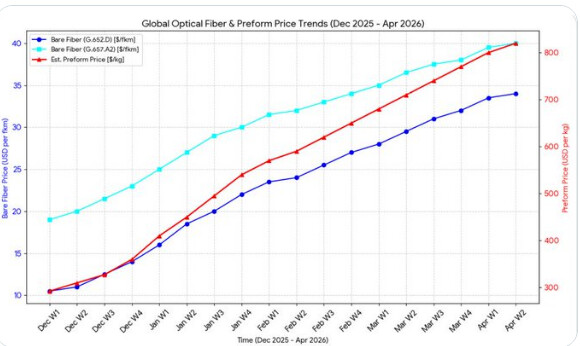
Hope it helps.
this is due to helium shortage and it would take some time to normalize.
and HFCL is backward integrating into preform but that will take 2 years so until that STLTECH has an advantage but they have to show this hype into numbers in few quarters to validate this rally as it is front loaded and they haven’t won any order yet like HFCL which has won Rs10,000 crs order last month.
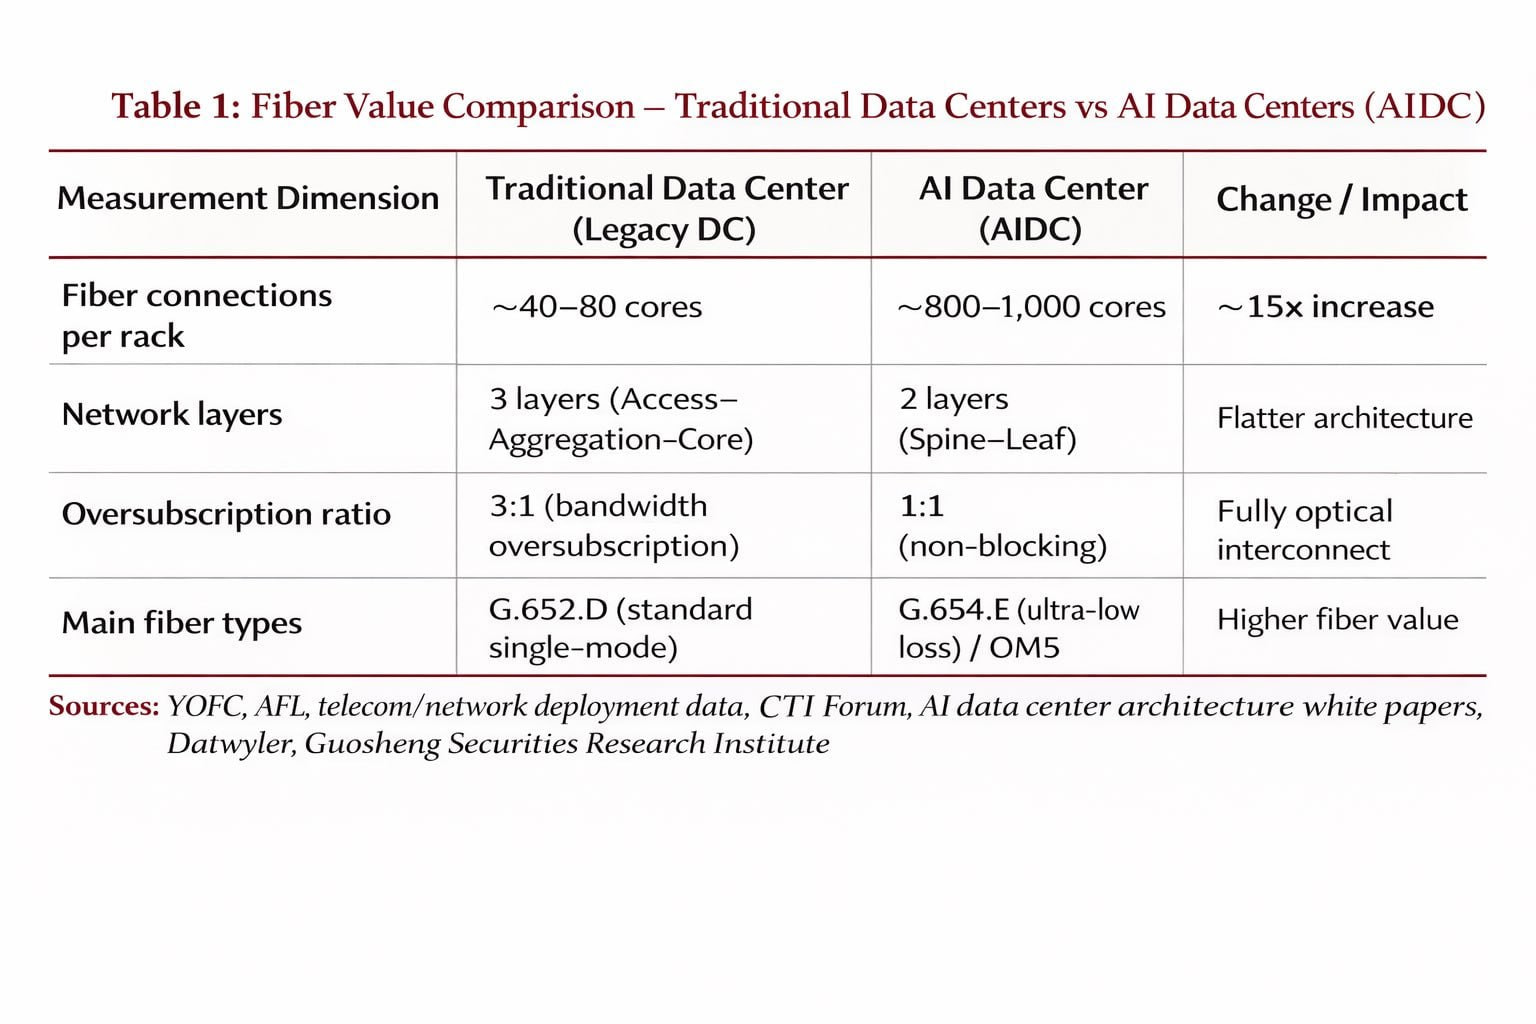
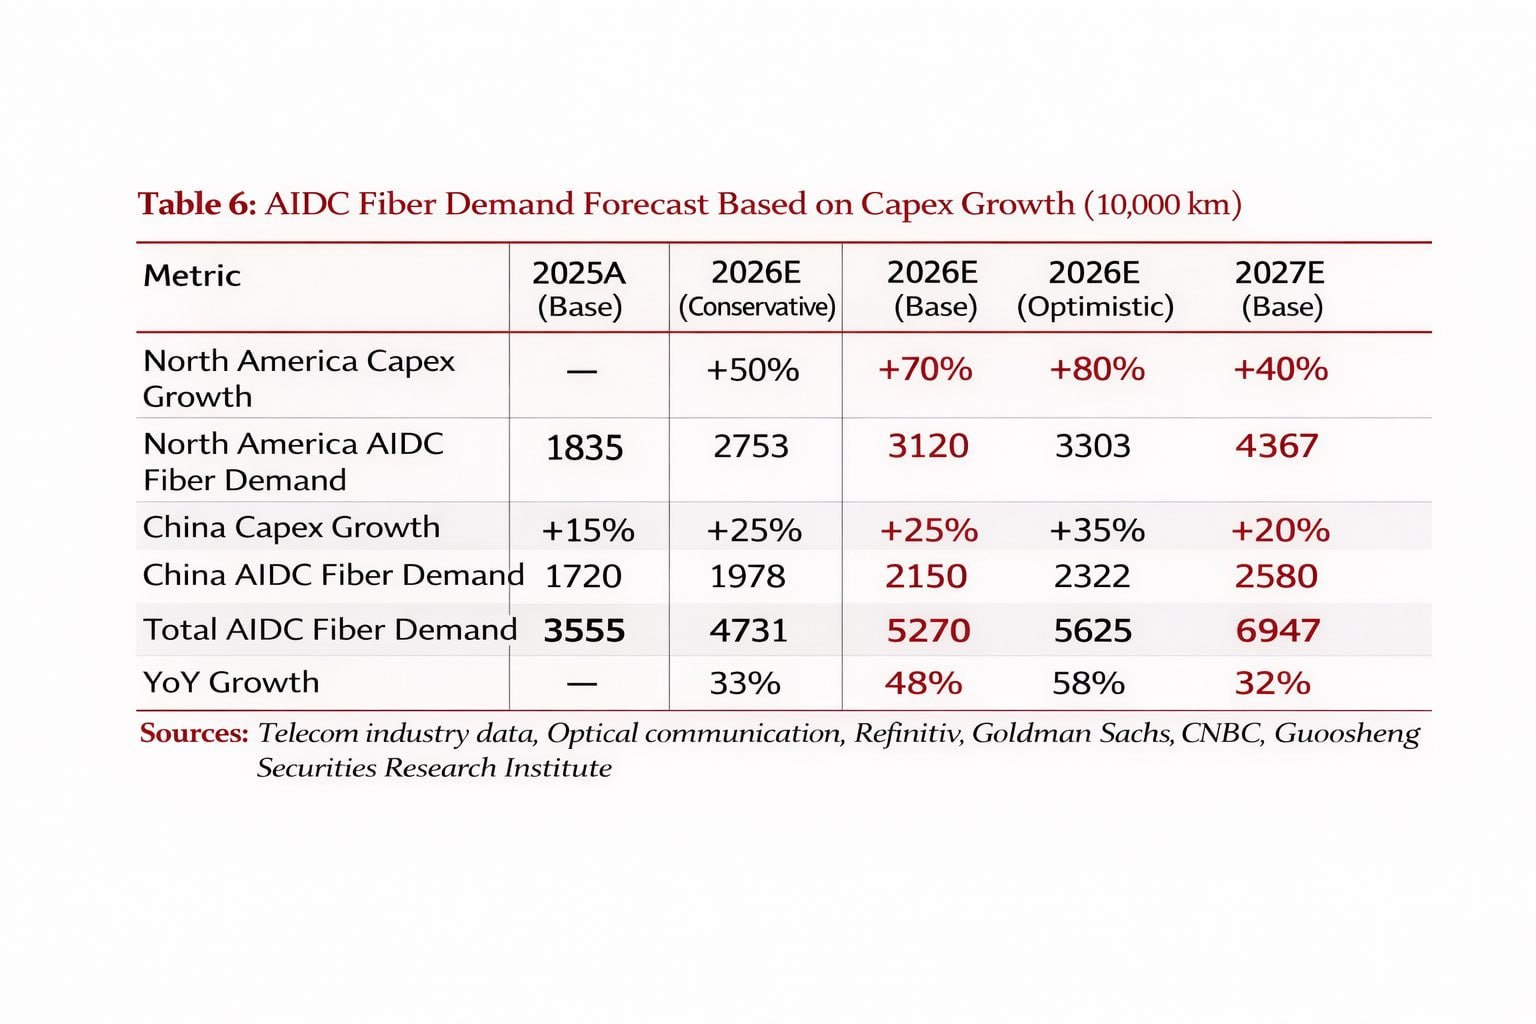
Fiber demand is scaling faster than compute growth, which is positive for optical fiber, cable, and DC infrastructure ecosystems. India can become key global AI infra backbone player
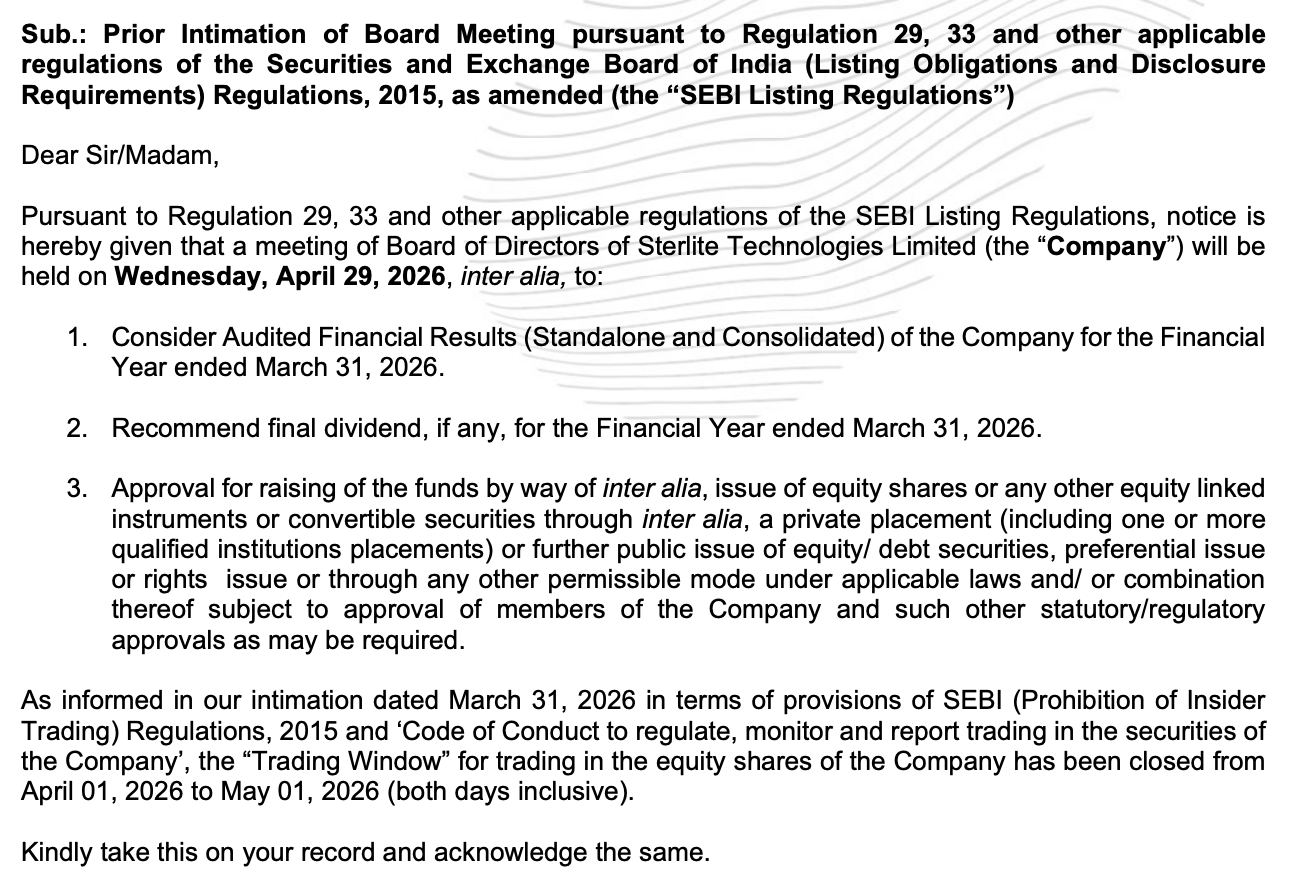
Another fund raise, which is just after a recent one directly from the promoters. Says a lot about the demand.
Getting 10000 crores order is fine but HFCL won’t get margins.. The margins will be captured by preform players like sterlite. That’s why sterlite tech share price is running.
This is a fact. Rest it’s upto everyone to decide where to invest.
And yes as usual price runs before the earnings particularly before turnaround cases like this.