Shera Energy Ltd – Fundamental Analysis (October 2026)
Company: Shera Energy Limited
Sector: Non-Ferrous Metals – Copper, Aluminium, Brass and Zinc-related Products
Exchange: NSE Emerge (NSE: SHERA)
Industry: Metal – Copper / Copper Alloy Products
1. Basic Details
- Market Cap: Approximately ₹412 crore
- Current Price: ₹168.60 (closing price on 30 October 2026)
- Listing Date: 17 February 2023
- 52-Week High: ₹207.45
- 52-Week Low: ₹94.95
- Face Value: ₹10
- Promoter Holding: 62.35% (September 2026)
2. Financial Highlights
Latest audited financial year: FY2025–26
Consolidated financial performance:
- Revenue from Operations: ₹1,640.05 crore
- Total Income: ₹1,646.73 crore
- Net Profit: Approximately ₹36.98 crore
- EPS: ₹12.03
- ROE: Approximately 21.30%
- Debt-to-Equity: 1.35
- ROCE: Approximately 27.23%
- Revenue Growth (FY2025–26): Approximately 28.4% YoY
Standalone financial performance:
- Revenue from Operations: ₹1,042.07 crore
- Net Profit: Approximately ₹14.85 crore
- ROE: Approximately 11.03%
- Debt-to-Equity: 0.92
Note: Consolidated and standalone numbers should not be mixed when comparing financial ratios. Consolidated numbers are more appropriate for assessing the overall group.
3. Business Overview
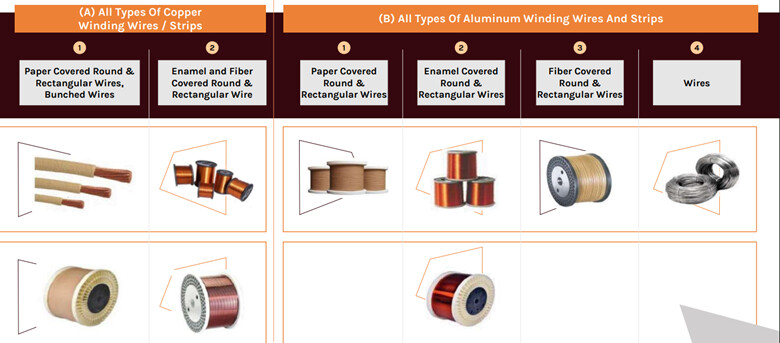
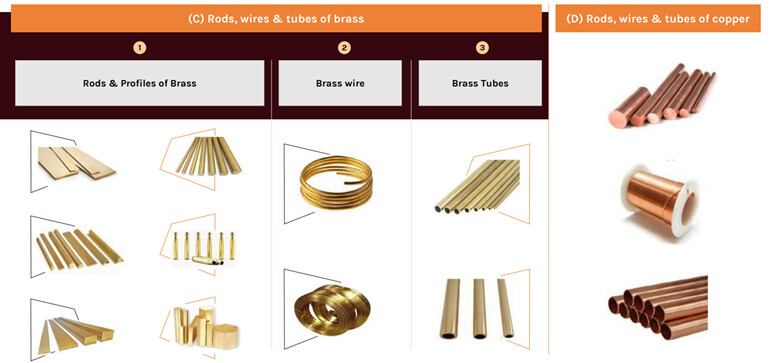
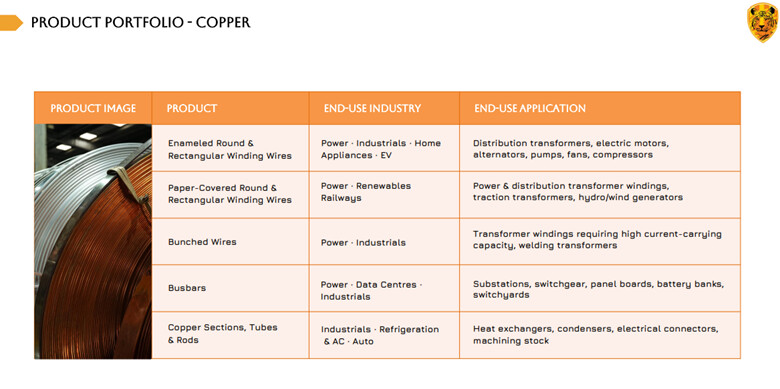
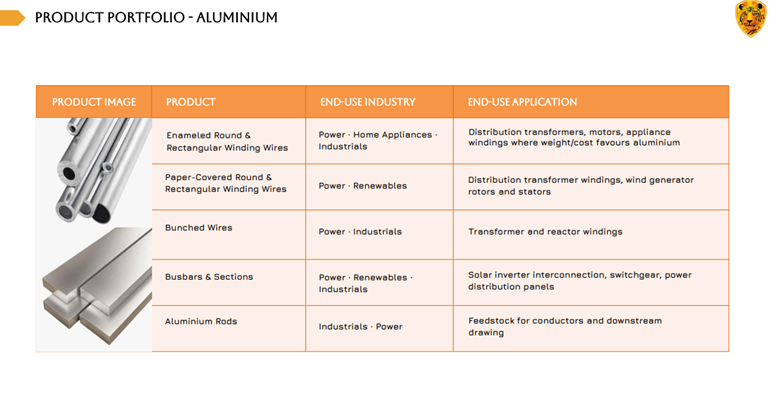
Shera Energy is a manufacturer of non-ferrous metal products, primarily catering to the electrical, power transmission, infrastructure, engineering and industrial sectors.
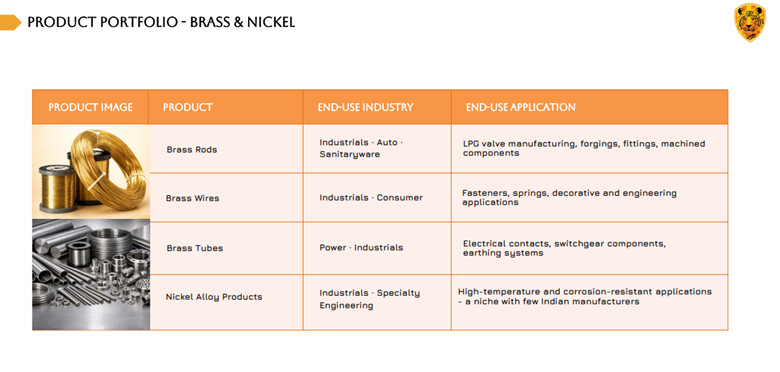
The company processes copper, aluminium, brass and other non-ferrous metals into specialised products used in electrical equipment, transformers, power distribution and industrial applications.
Market Position:
Shera operates in a specialized manufacturing segment where product quality, technical approvals, manufacturing capability and customer relationships are important.
The company has vendor approvals from Power Grid Corporation of India and Gujarat State Electricity Corporation Limited for certain products.
It competes with established players in the copper and aluminium processing industry. However, it should not be considered a dominant industry leader merely on the basis of its growing revenue.
Key Customers:
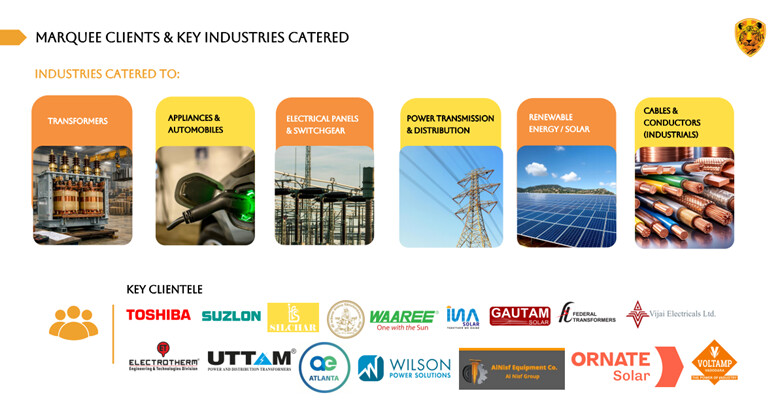
The company serves customers in the power, electrical, transformer, infrastructure and industrial segments.
Power Grid, GSECL, Hitachi Energy vendor approvals are noteworthy.
4. Management Quality
Promoter Background:
- Mr. Sheikh Naseem – Chairman and Managing Director.
- Mrs. Shivani Sheikh – Whole-Time Director.
The Shera Group traces its operating history to 2003, with experience in copper and aluminium winding wires, strips and related products.
Sheikh Naseem has been instrumental in developing the manufacturing business and expanding its product portfolio.
Shivani Sheikh is associated with the company’s finance and corporate management functions.
Promoter Holding:
- Promoter and promoter group holding: 62.35% as of September 2026.
- Promoter pledge: 0% according to the reported September 2026 shareholding data.
The promoter holding is reasonably substantial. However, investors should also monitor any dilution arising from outstanding convertible securities.
5. Investment Thesis
Positives
- Strong revenue growth and improving profitability.
- ROE and ROCE indicate improving capital efficiency.
- Established manufacturing experience dating back to 2003.
- Diversified product portfolio across copper, aluminium and brass.
- Vendor approvals from Power Grid and GSECL provide credibility in the power sector.
- Promoter holding of approximately 62.35%, with no reported promoter pledge.
Growth Drivers
- Increasing demand for copper and aluminium products due to electrification, power transmission and infrastructure development.
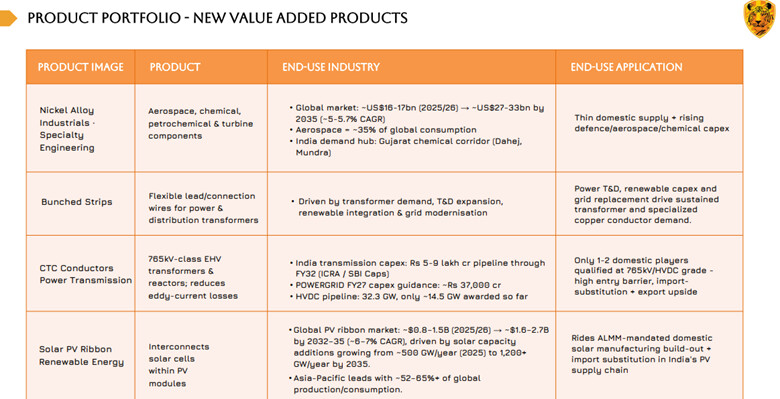
- Growing demand from renewable energy, transformer and electrical equipment manufacturers.
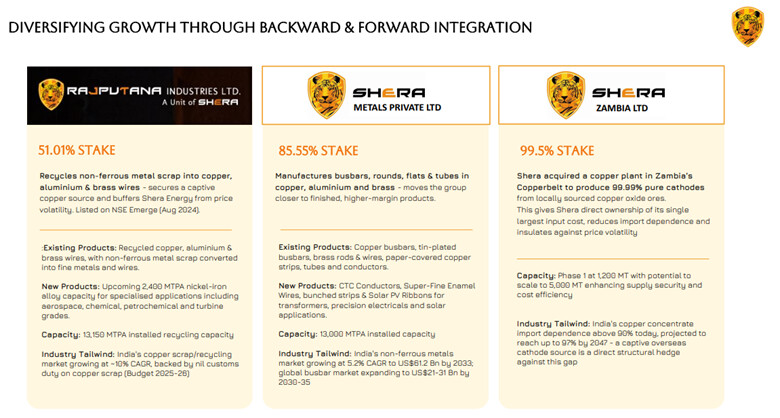
- Expansion into higher-value specialised products, including brass and nickel-alloy applications.
- International expansion through Shera Zambia Limited.
- Potential backward integration through the planned copper cathode manufacturing facility in Zambia.


Concerns and Red Flags
- Rising consolidated debt: Debt-to-equity is approximately 1.35, requiring monitoring of interest costs and cash flows.
- Zambia investment exposure: The annual report highlights loans and investments associated with the Zambia business and its associate. Their repayment, recoverability and commercial returns need close monitoring.
- Working capital: The business requires substantial investment in raw materials, inventory and receivables.
- Thin margins: A large revenue figure does not necessarily translate into equally strong cash generation.
- Execution risk: The copper cathode facility and overseas expansion must translate into actual earnings and cash flows.
- Statutory dues: The FY2025–26 Annual Report discloses a disputed GST interest liability of ₹8.91 lakh pending before the First Appellate Authority. This is relatively small but should be monitored.
- Related-party and subsidiary transactions: Investors should continue reviewing loans, advances, investments and receivables involving group entities.
- The FY2025–26 consolidated auditor’s report also identifies the impairment assessment of loans extended by Shera Zambia Limited and its investment in an associate as a key audit matter. This is an area that deserves particular attention.
6. Valuation
Based on the 30 October 2026 share price and FY2025–26 consolidated financial statements:
- P/E Ratio: Approximately 14 times (₹168.60 / FY26 EPS of ₹12.03).
- P/B Ratio: Approximately 1.8–2.1 times, depending on the book-value methodology and data provider.
- EV/EBITDA: Approximately 7 times on an indicative calculation; this should be verified against the latest market enterprise value and consistently defined EBITDA.
Compared to peers:
Shera appears reasonably valued on its FY26 earnings compared with several established listed players in the non-ferrous metals space.
However, a direct comparison needs to account for differences in business mix, scale, leverage, margins and return ratios.
The stock should not be considered automatically undervalued simply because its P/E is relatively moderate.
The sustainability of its earnings growth and the return generated on new capital will be crucial.
7. My assessment
Copper, Aluminium and Brass recycling will be huge in India as 90% plus import dependent and this company is fully integrated with Coper value chain
Valuation gap compared to peers (as per the management ) R R Kabel, Vidya Wires, Precision Wires visible
Zambia Copper cathode plant is about to commission ( Major margin expansion trigger)
Entry into CTC (continuously transposed conductor) for EHV/765kV transformers - import substitute (only handful of companies make it in India)
Nickel Iron Alloy - will be very interesting if they able to make aerospace level grade alloy I can see lot of triggers for re-rating.
Shera started its journey as a transformer company and now they are supplying transformer companies and Shera is also an approved supplier for Hitachi Energy and Upcoming BIS approval removes regulatory barrier that allows to access new addressable market
Most important: Company is very much focused on cash generation from business. And they are eligible for main board migration, also they applied to bring all the subsidiary companies under one roof..this will give a huge boost to the visibity to investor like HNI, MF etc
Recent announcement of more than 1000cr revenue in Q2 before Q2 end is a good sign
Where i am bit cautious: Debt to equity ratio is high and companies will increase the ratio to expand the copper cathode plant once the first phase is successful. Keeping an eye if margins are increasing to accommodate interest and depreciation cost.
Even though copper is commodity, but the due to upstream value chain this risk can be optimized/ mitigate to certain extends
Industry tailwind like Data Centre and Electrification or power demand will be additional advantage
Shera Energy merits continued fundamental tracking, particularly to see whether revenue growth translates into sustainable free cash flow, improved consolidated returns and lower financial leverage.
The next few quarterly results should provide useful evidence regarding the success of its expansion strategy.
8. Disclosures
invested and have recent transactions.
I am not associated with the company’s management unless otherwise disclosed.
Disclaimer
SME stocks carry higher risks due to their smaller size, limited liquidity, concentration risks and potentially greater price volatility.
Please consider this with pinch of salt, as I might be very biased here