
About-
-
The company is a newly listed B2B jewellery manufacturer which got listed on 01 Aug 2025.
-
The company IPOed at Rs. 199 Issue size of 360 crore and the total amount was fresh issue, which is a good sign.
-
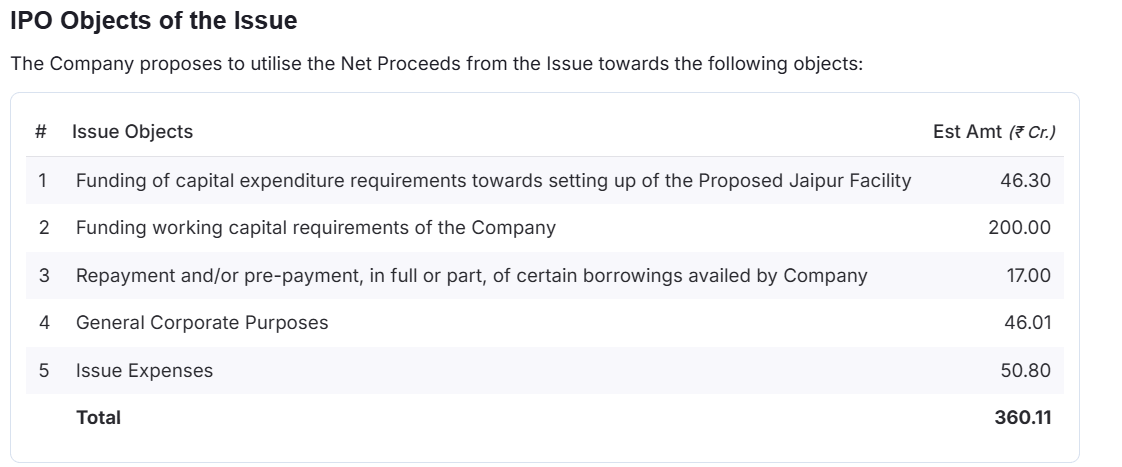
IPO objectives-
-
Website of the company (A bit weird, the website is not secured)
Background & Promoters-
-
The co. started in 2003 as a partnership firm.
-
The co. is is promoted by two founders, Pankajkumar Hastimal Jagawat (Chairman & Managing Director) and Manojkumar N Jain (Whole-time Director), who each hold 37.43% of the company, plus a third promoter, Shashank Bhawarlal Jagawat (0.01%). The promoter group holds 74.89% with zero pledged shares.
Manoj Jain Social Media- https://www.instagram.com/mj7776_/
Linked In- https://www.linkedin.com/in/manoj-jain-825317158/
-
ould not find social media of the other 2 promoters.
-
Both promoters’ remuneration was raised from ₹1.08 crore to ₹1.80 crore per annum, effective February 01, 2026.
-
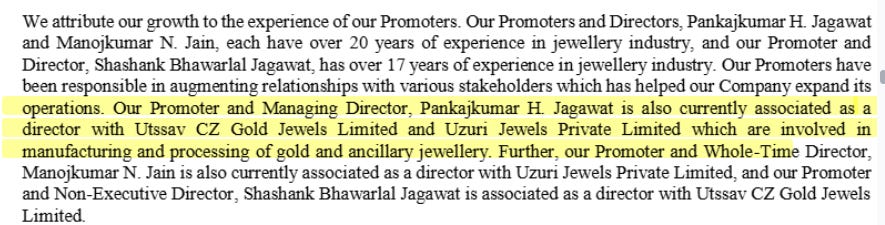
Related Entities- Utssav CZ Gold Jewels Limited and Uzuri Jewels Private Limited are involved in manufacturing and processing of gold and ancillary jewellery; Pankajkumar Jagawat is a director in both, Manojkumar Jain in Uzuri, and Shashank Jagawat in Utssav.
- Found no criminal cases against the promoters.
SWOT analysis-
S- The designs they make are unique like their peers. Also they are adding 400+ new designs every month.
   The clients are generalistic in nature once they find good designs.

   They have 400+ customers, and the top customer contributes to only 7-8% of the                           revenue.
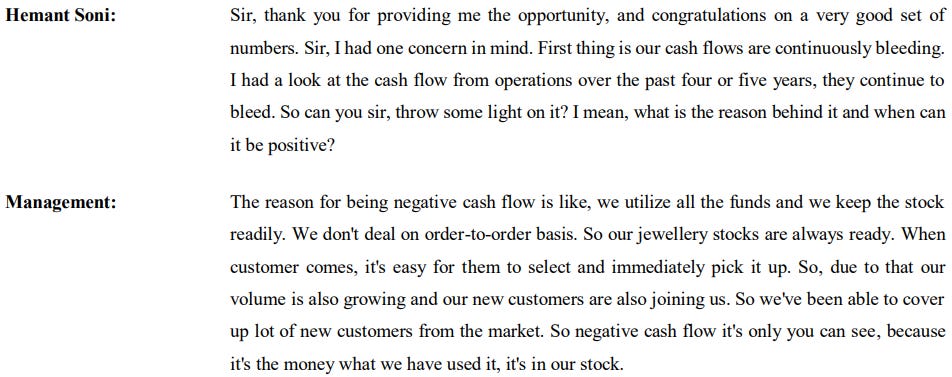
W- The business model is working capital-heavy, and it’s tough to generate cash flow in this kind of company.
It’s tough to get pricing power because of competition & not having a brand.
O- Organized jewellery retailing as well as outsourcing of manufacturing has been a structural tailwind.
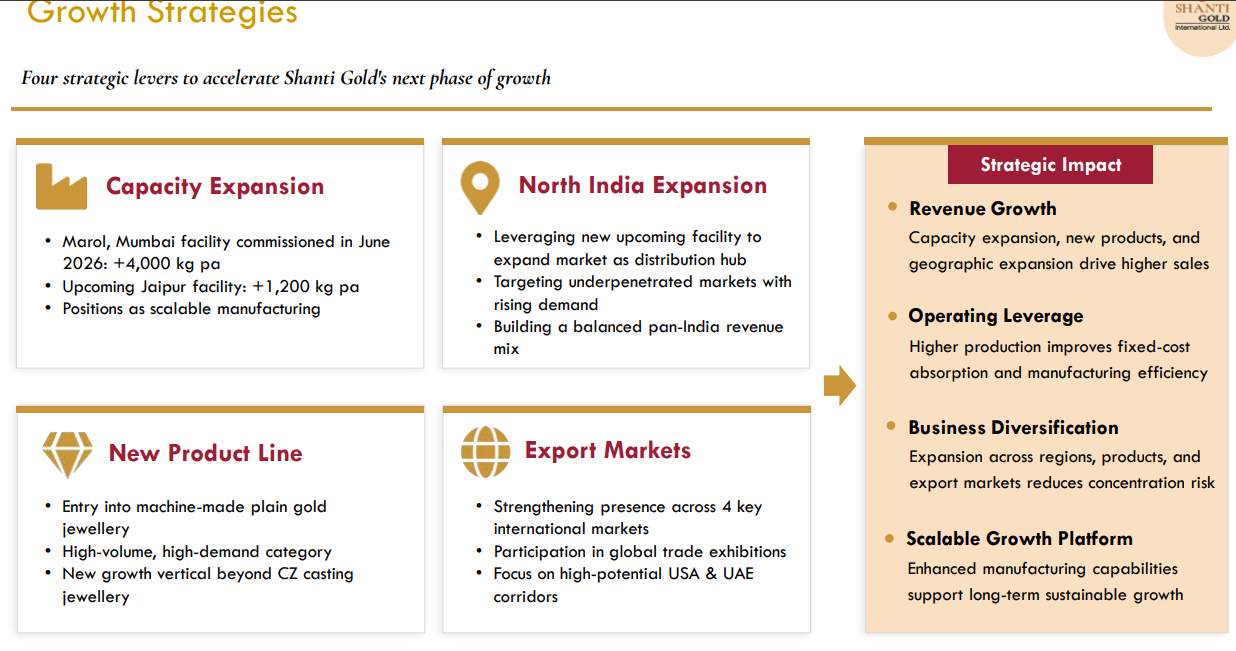
   They have enough capacity, with 4,000 kg recently going live in June and another                         1200 kg coming live in December.

   Export contributes to 4% of the total revenue, which can inch further with the newly                       incorporated Dubai subsidiary.
T- Gold price volatility.
High degree of concentration in southern states of India.
** I don’t know how same promoter(s) working in similar kind of companies impacts the business and how the market treats it.
P2P analysis-
-
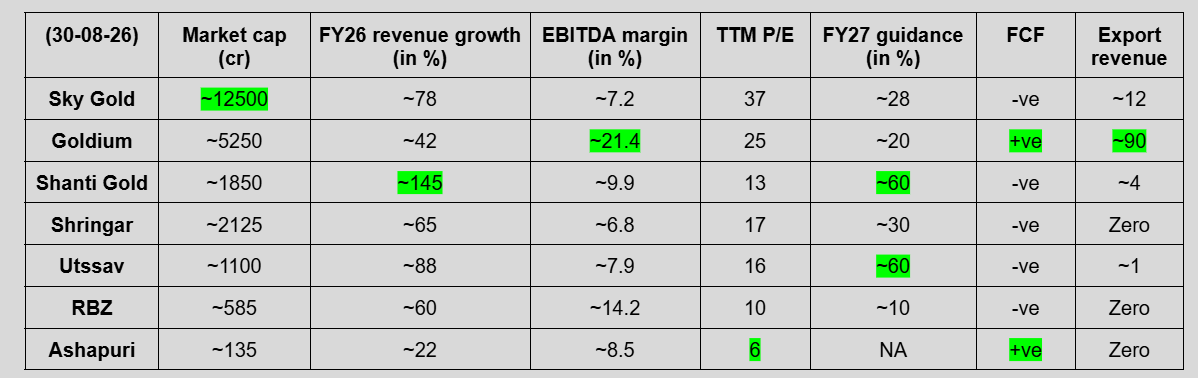
The higher EBITDA margin of GoLiam International is because they sell diamonds. Started in July with a higher share in export revenue.
-
Asapuri trades at the cheapest valuation because, despite being the smallest company, the growth is also the slowest.
-
Cash flow issues are common among all the players because the cash flow generated is being used As working capital.
Q1FY27 result & conference call-
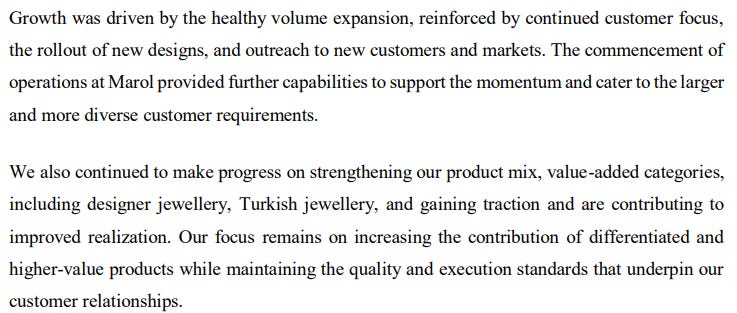
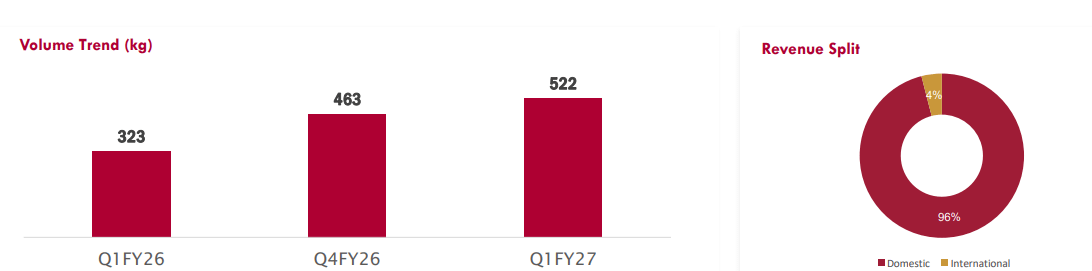
- Revenue growth of 144%, volume grew by 61.6% but EBITDA, PAT took a hit because of higher inventory and depreciation which are not bad things at all.
-
Added 4000 kg capacity in Marol, Mumbai in June 2026 to the capacity of 2700 kg previously which was 75% utilized.
-
The co. has a current capacity of 6700 kg p.a., with 1200 kg to be added soon in Jaipur (at 47 cr capex).
-
The capacity will go live in November end, December.
-
Growth strategy of the co-
-
Domestic sales contribute to 4% of the total sales.
-
Volume utilization in Q1 is 522 kg.
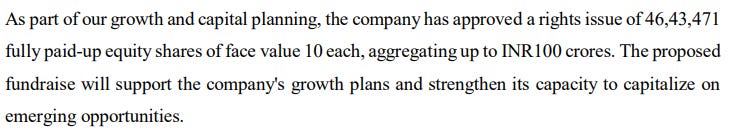
- 100 cr rights issued to fund the capex & growth (@ 215) to fund the working capital.
-
Targeting 7.5-8% EBITDA margin, 4% PAT margin for the future, FY26 was higher because of unrealised gains.
-
Studded jewellery contributes to 75% of the sales and will stay constant.
-
50-60% revenue growth guided for the FY, out of which 30-40% will be volume growth.
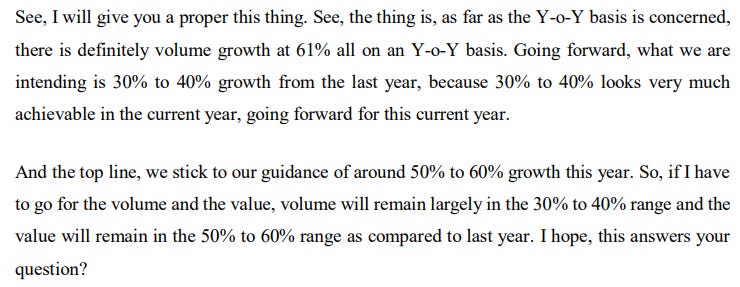
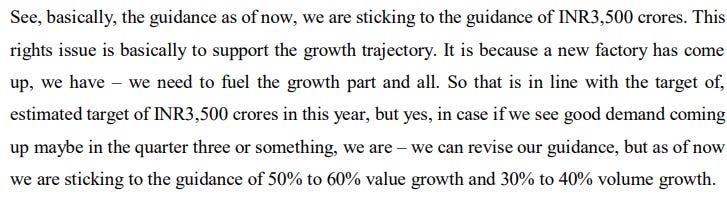
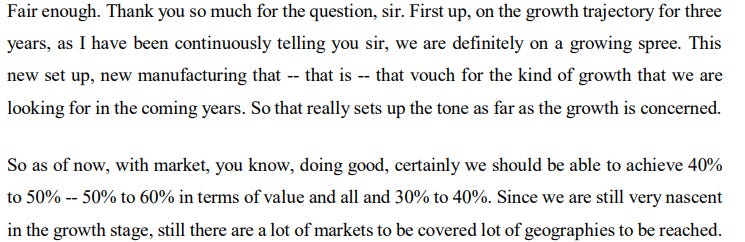
- 50-60% growth trajectory for next 3 years.
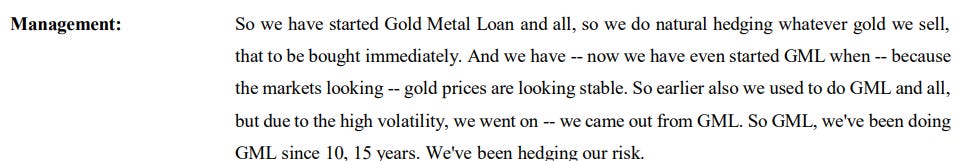
- Raw material sourcing/ hedging-
- Reason for -ve cashflow (the same explanation was given by SKY Gold when they had -ve cashflow)
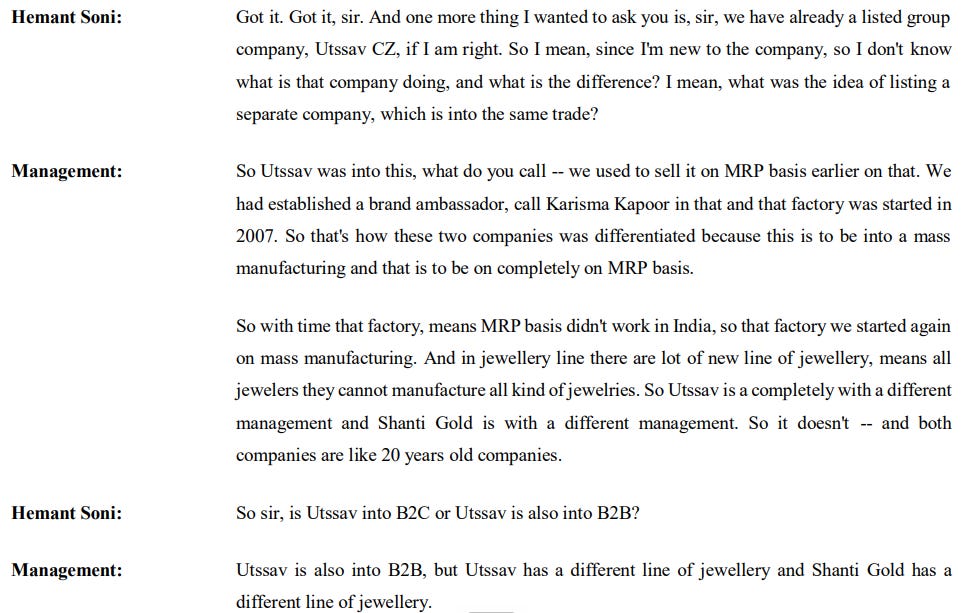
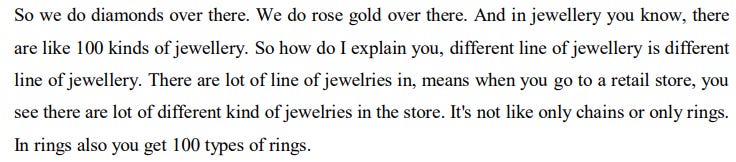
- Utssav CZ comes from the same group & the management tried explaining the difference between both the groups.
Key monitorable-
-
As for any company, but more importantly, for new or small company, the execution risk stays.
-
Whether the company can sustain current margin.
-
Capital requirement and how it is funded.
-
Concentration Risk (Top 10 Customers contribute to 44.8% revenue in FY26)
-
Volume guidance and execution, which has been going here and there more often.
-
Capacity utilization of newly commissioned Marol plant.
Valuation-
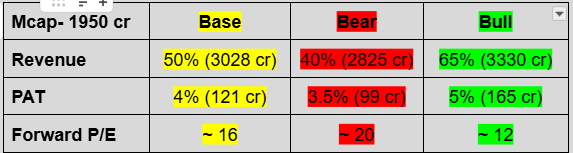
Considering 1950 cr market cap, a rough FY27 forward valuations would be
** I hold an initial tracking position in the company, <1% of my total PF, consider me biased.
** This is not a buy/sell recommendation, DYOR.