Updates on JayKay:
- Receives AS9100D certification for its Bengaluru facility, JKE can bid directly to HAL, Safran, Collins, Boeing/Airbus tiers and be on approved-vendor lists in its own name
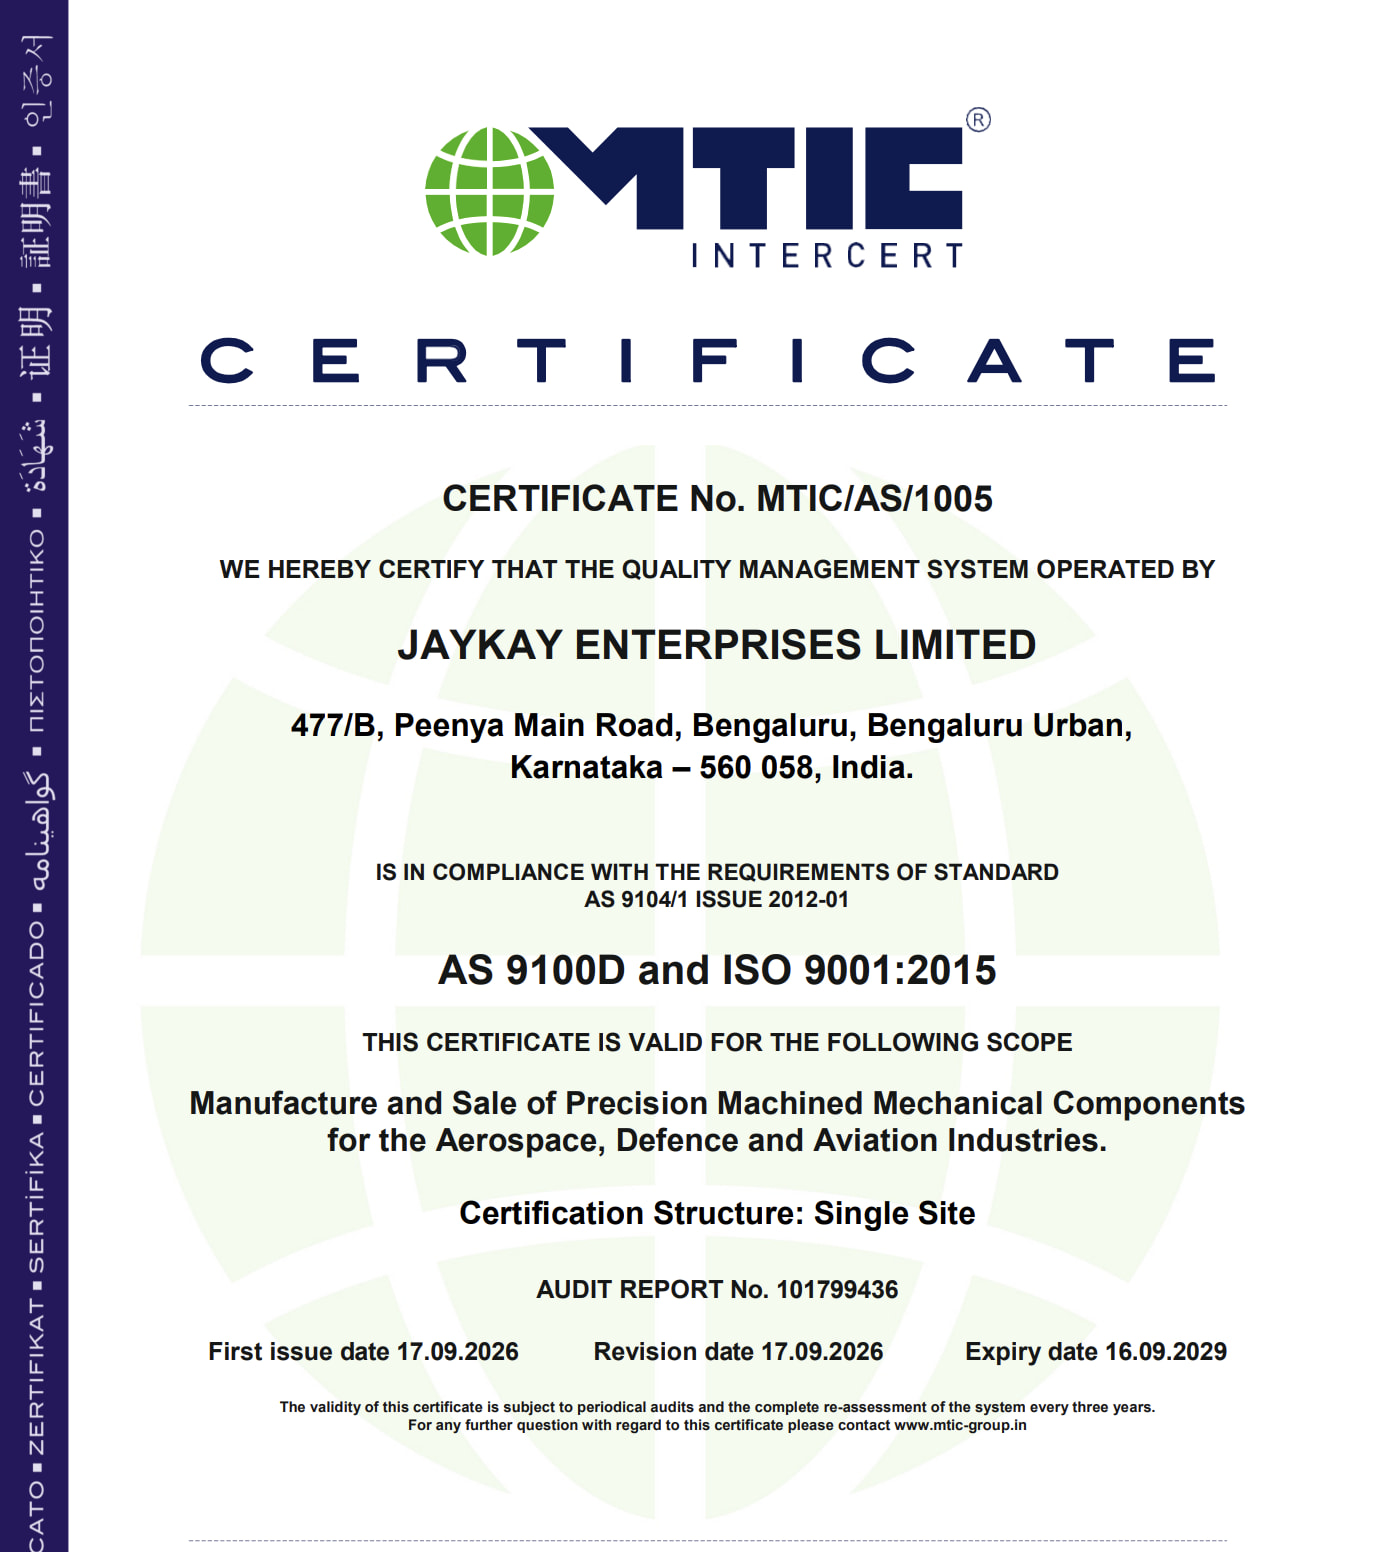
Their Step down subsidiary already had this certification but this new cert is still needed for the new facility and also it has different scope.
| Earlier (FY25-26) | Today (17 Sep 2026) | |||
|---|---|---|---|---|
| Entity | Allen Reinforced Plastics Ltd (step-down subsidiary) | Jaykay Enterprises Ltd (the listed parent itself) | ||
| Facility | IDA Bollaram, Telangana | 477/B Peenya Main Road, Bengaluru | ||
| Certifier | Intertek Testing Services NA | MTIC InterCert India (NABCB-accredited, AQMS/ICOP scheme) | ||
| Scope | Design, development, manufacturing, assembly and testing of FRP and allied products |
Manufacture and sale of precision machined mechanical components for aerospace, defence and aviation |
-
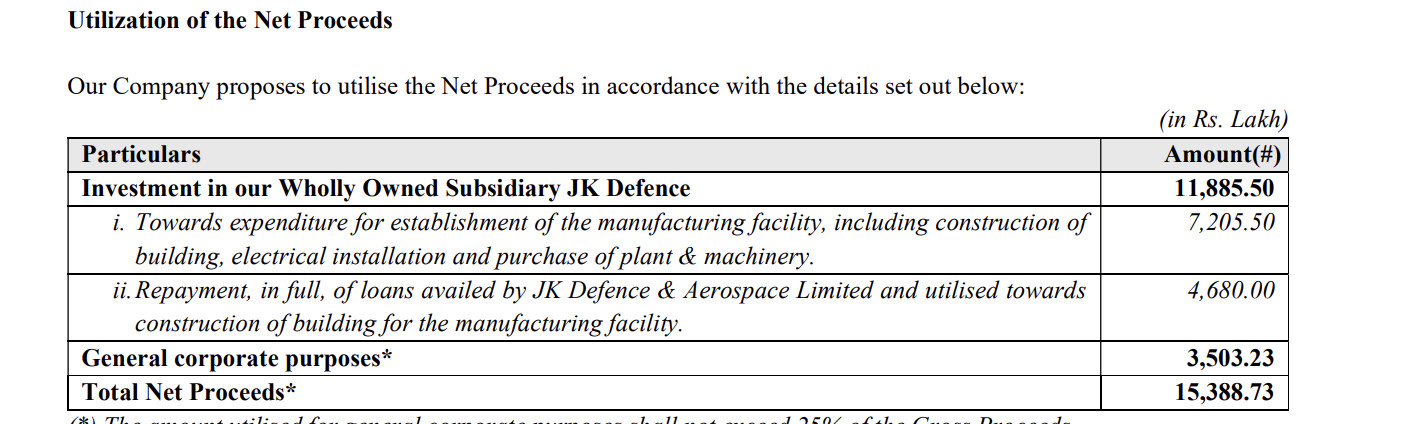
Did a Rights issue and raised 154 cr , details of the same below
The integrated QMS cert of ISO 9001:2015 with that of AD received on 16 Sept 2026 coincides with that of the release of the modern version - 9001:2026 released om 16th Sept only.
It is credible to get the cert as a market requirement. But the latest certificate is much more respectful than the one lapsing in importance.
Hey Satish, thought you’d want to check out this Creative Graphics ValuePickr thread looking at their recent supply headwinds and capacity scaling.
Satish's SME Corner : Notes and Con-call Updates - #202 by Satishwe @Ashok_R I do track this one mentioned here few months back. Need to monitor for now.
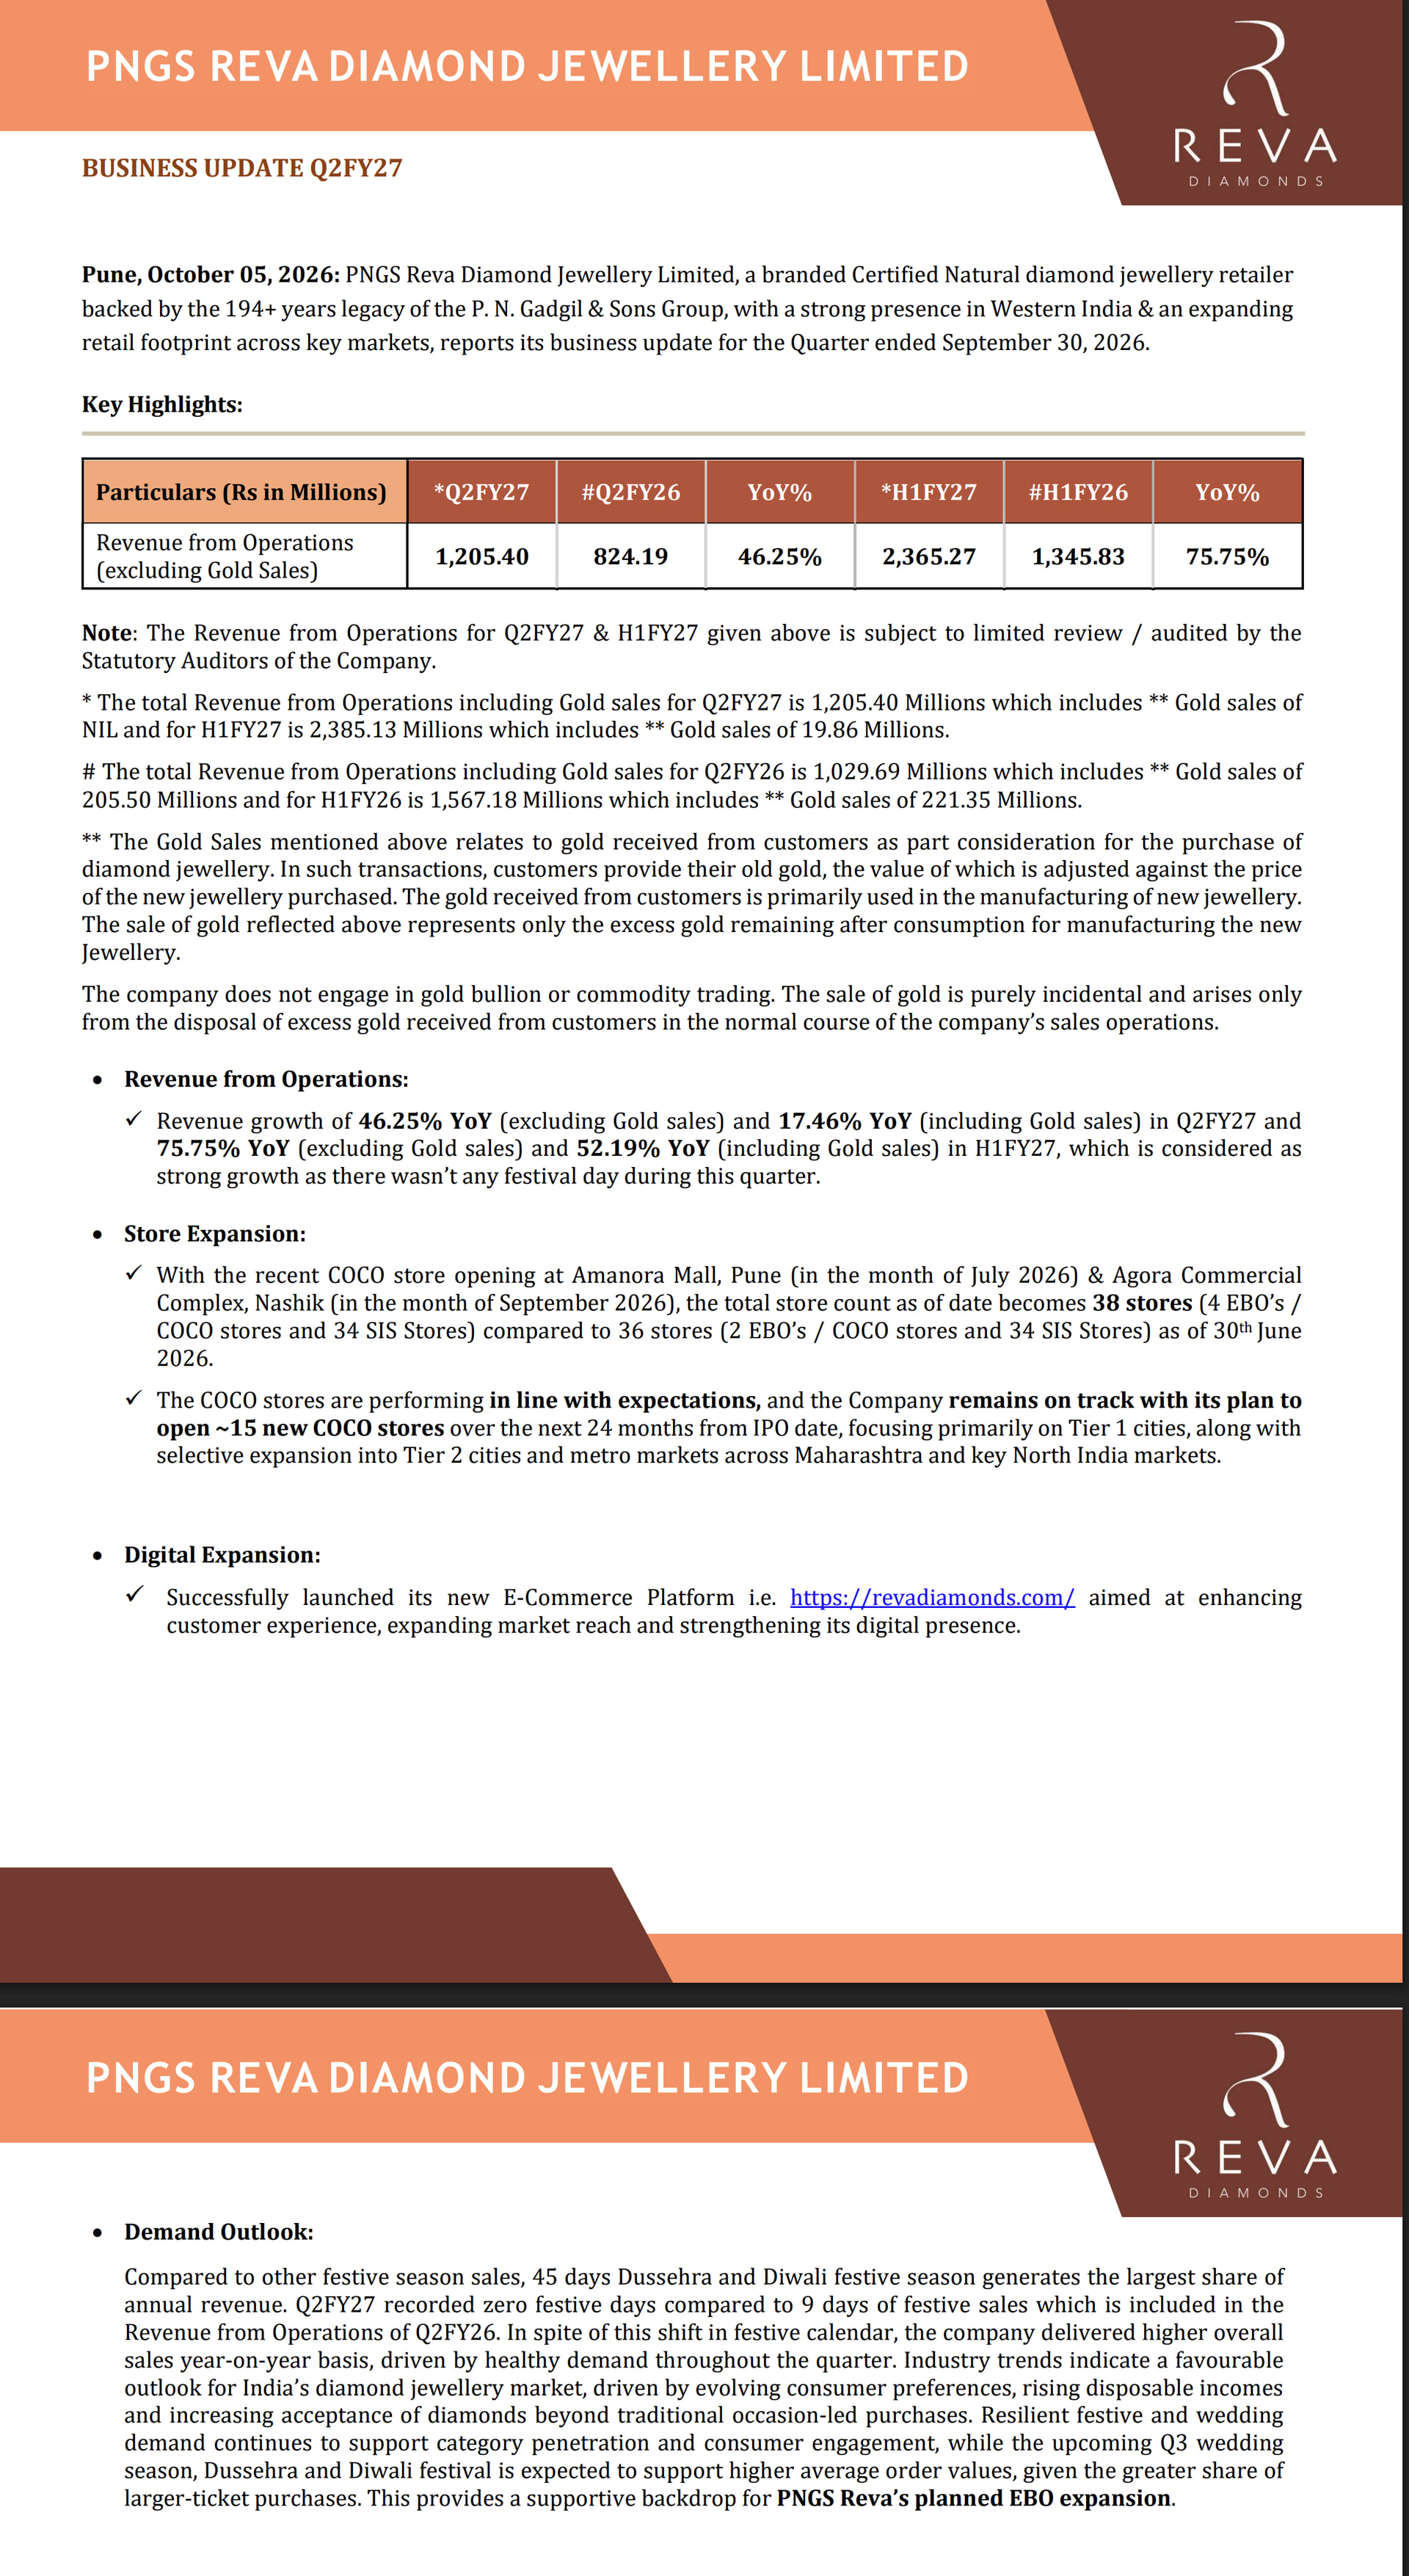
REVA : Q2 updates from Reva. Expansion still on track as per IPO plan.
JNK India : India might increase the capex for Domestic refineries which will add to TAM of JNK India.
WORKMATES :
In Recent SME event WM announced they are Partnering with AI companies to increase their presence in AI Ecosystem for MSMEs via Amazon Bedrock. This( claude via bedrock) should be Positive news in that context.
@Satishwe & Folks
A. Jaykay Enterprises — thoda paisa rights issue se aaya, ab dekhte hain paisa jaa kahan raha hai
Stock moved up sharply post rights issue (fully paid ~250, partly paid catching up).
Putting together what I could gather from public disclosures. Please correct me if I’ve missed anything.
Rights money: 25 Cr into JK Defence (preference shares, Devanahalli) + 2 Cr into JK Digital (5 Oct 2026 filings). Paisa operating businesses mein jaa raha hai.
B. Ab dekhna hai paisa kitna kamaata hai
Visible defence orders: BrahMos/Allen – 94 Cr + 60 Cr; BDL/Allen – 16 Cr; BrahMos/Group – 4.5 Cr; Ircon/JK Phillips JV – large CNC/turnkey order.
So visible higher-quality orders appear to be in the low-to-mid hundreds of Cr, though exact order book isn’t disclosed.
Devanahalli: 5 acres, ~4 lakh sq ft; 2 lakh CNC + 1 lakh Additive + R&D, with 80–100 metal printers. Civil target Dec-26, full commissioning Q4 FY27. Products include precision components, missile/aerospace sub-systems, warheads, shells etc.
4 lakh sq ft to bana denge… ab andar se maal kitna niklega?
C. Revenue thought:
Current quarterly run-rate ~75 Cr. FY27: 350–450 Cr | FY28: 550–750 Cr. No company guidance — pure extrapolation. **Excel kuch bhi bol raha ho sakta hai **
Concerns: Neumesh issue/fraud unresolved, no provision + audit qualification, defence working-capital intensity and limited disclosures.
Questions:
- Any latest update on Devanahalli progress beyond Q1?
- Any material orders/execution updates I’ve missed?
- Do the FY27/28 numbers look reasonable, or Excel optimism gone too far?
I have a position. Trying to understand whether this is becoming a genuine capacity + order book + execution story, rather than a defence-theme narrative.
On Workmates Core2cloud Solution Ltd:
If I have understood correctly, the company is an AWS reseller. The largest cost item on its P&L is “AWS Consumption Charges”. The revenues under different heads are all clubbed together as a single line item “Consultancy and services, development, reselling cloud management, information technology, content creation, facilitation charges, web photo-grammetry imaging and display etc” and not disclosed separately.
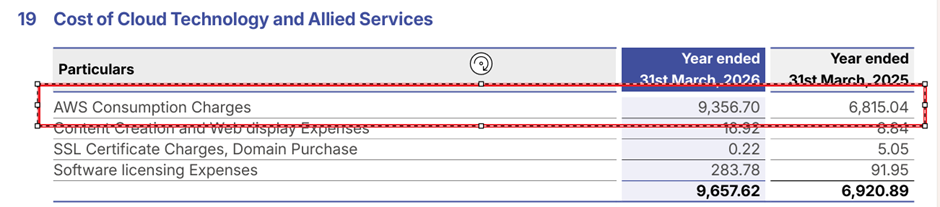
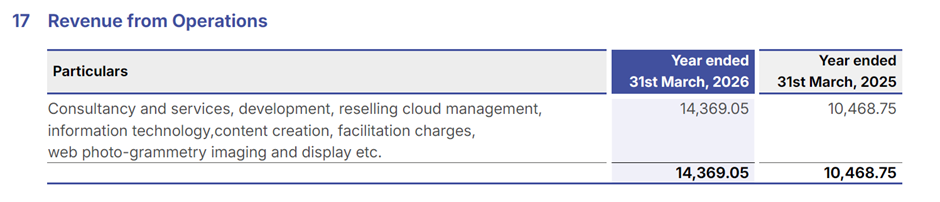
Though the break-up for each of these is not given, “reselling cloud management” is likely to be the largest line item in this. It is just a pass-through of the “AWS Consumption Charges” (with or without a markup margin).
Currently the company maintains is books as per Indian GAAP, but if it migrates to Ind (AS), what impact will be there on its revenue recognition is not clear. Ind (AS) 115 which governs revenue recognition uses multiple criteria to test the nature of relationship between the company & its customers. We don’t know enough about the specifics of the contracts Workmates has with its customers. I couldn’t find anybody raising this question with the management either. But SoftwareOne – a Microsoft / AWS cloud reseller reports its numbers on a net basis i.e. netting off the consumption charges with the gross revenues earned by the company from its own customers.
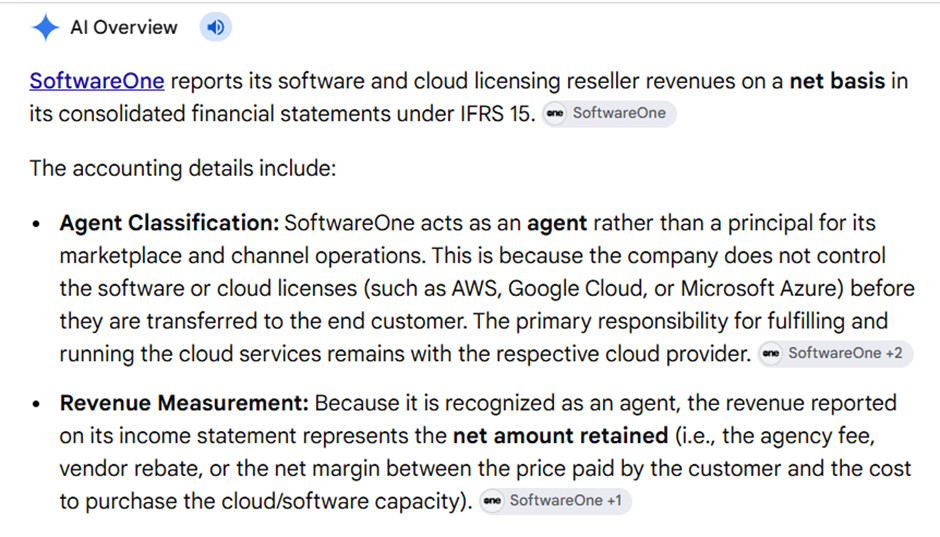
A similar debate has cropped up more recently in the context of the impending Anthropic & Open AI IPOs. Anthropic reports its revenues on a gross basis when customers buy Claude through third-party cloud marketplace partners (such as AWS and Google Cloud). But OpenAI records revenue on a net basis.
This is an accounting grey area that one needs to be careful about. If Workmates is required to follow the conservative method of SoftwareOne / Open AI, its reported revenue will fall by 2/3rd. Of course, this will only be a presentation change since the associated costs will also disappear. But the company’s claim of “80% annuity / recurring” revenues need to be seen in that context.
If anybody has more clarity on this, please share.
You can check glassdoor reviews and get a feel of work it is doing. Such a low rating of 3.1 and avg salary of 11 lakhs indicate pretty low end work.
JayKay Enterprises: received a Licence to Manufacture for Sale or for Distribution of Class C or Class D Medical Devices
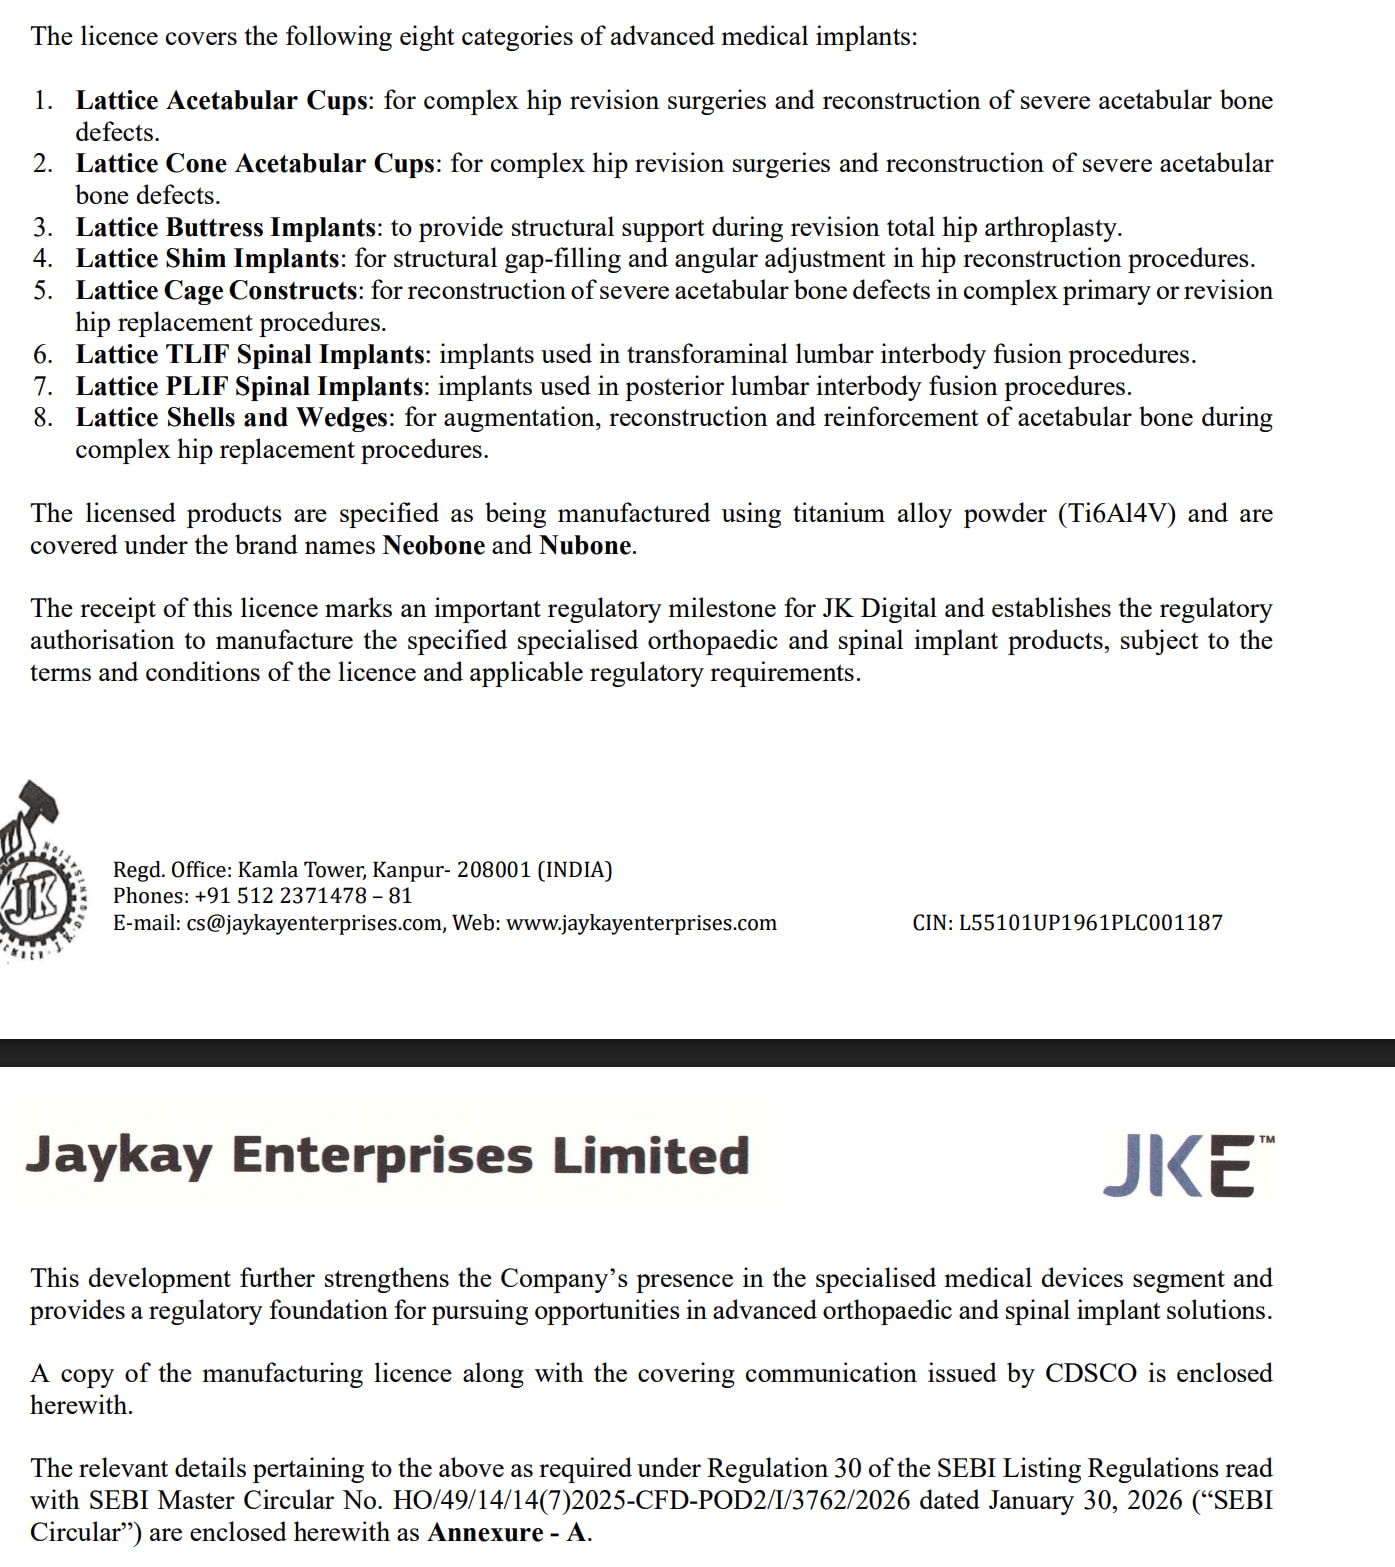
The company has recently declared some hefty orders and with below 10 PE , it looks like a very decent bet .However , there is almost no market response( read price rise) to any good news at all. Is it only the current market situation or is there something else ??
If you are talking about afcom please refer this thread.