Summary :
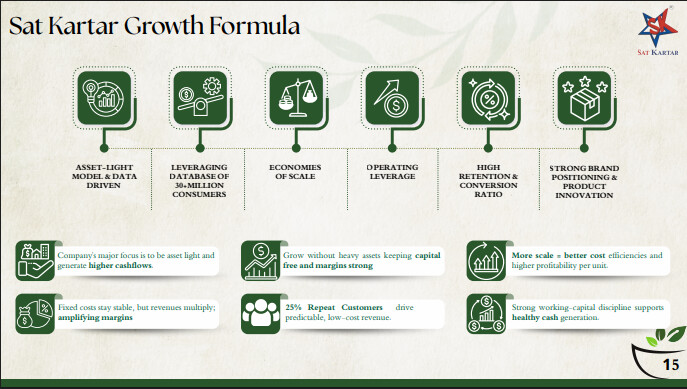
Satkartar Life is undergoing a strategic transition from a direct-to-consumer (D2C) Ayurvedic wellness brand into an institutional, asset-light healthcare provider. While the core business scaled rapidly on digital channels, management is leveraging this patient funnel and data to build a specialized offline hospital network. The company’s standout differentiator is its concentration on Ayurvedic infertility treatments a high-margin than existing business, under-addressed niche in alternative medicine. Financially, revenue has scaled from INR 51.92 Cr in FY22 to ~INR 200 Cr in FY26, with long-term internal projections targeting INR 1,034 Cr by FY30 under a base-case scenario.
Business Model & Strategic Positioning
-
Brand Architecture & Pricing Tiering: The company sells high-ticket wellness products under the flagship Satkartar brand (INR 3,000–4,000 ticket size). Its subsidiary, Ajooni Lifesciences, targets mass-market nutraceutical demand with lower price points (INR 900–1,200).
-
Backward Integration: The company has in-house powder manufacturing capabilities and recently acquired Phantomed Nutraceuticals, bringing 50% of its capsule manufacturing in-house while already having powder manufacturing in-house to protect product margins and improve supply chain control.
-
Differentiated Clinical Focus: Unlike major Ayurvedic hospital peers (such as Jeena Sikho) that primarily treat chronic kidney, liver, stone, and respiratory conditions, Satkartar has carved out a clear moat in infertility. Infertility treatments currently generate approximately 80% of total revenue at its existing 30-bed Delhi hospital . The key point to be noted here is Ayurvedic treatment of Infertility has better % chances of success than IVF. (PS:- I dont have any data backing this)
-
Post-Conversion Call Center Infrastructure: The company’s centralized call centers do not conduct cold outreach. Instead, they focus purely on patient retention, consultation scheduling, dosage adherence, and repeat orders once a lead is converted. The same workforce which is now well-trained and experienced will now be used to boost the newer hospitals. Clear Operating leverage.
Hospital Scaling Strategy & Strategic Alliances
-
Asset-Light Capex Model: Setting up hospital beds in this model is capital-efficient, costing approximately INR 7–8 Lakhs per bed (split roughly 50% for setup infrastructure and 50% for working capital).
-
Capacity Expansion Pipeline: The company operates a 30-bed facility in Delhi and is expected to announce a 10–15 bed hospital in Noida or some other northern cities. Two additional facilities are also being structured under revenue/profit-sharing agreements to minimize upfront balance-sheet stress (Not clear on sharing part). Management has outlined a target to scale from 30 beds to 300 beds by FY27 and 1,000 beds by FY28.
-
Jeena Sikho Partnership (Non-Exclusive MoU): Under a cooperative framework, Satkartar cross-diverts patients to Jeena Sikho facilities for a ~15% commission fee. This partnership allows Satkartar to leverage an established institutional playbook and expand while monetizing excess demand through partner infrastructure.
Financial Profile & Unit Economics
-
Order & Volume Dynamics: Average Order Value (AOV) currently stands at INR 3,250 and is projected to expand to INR 3,499 by FY30. Total order volume is modeled to grow from ~6.15 lakh orders in FY26 to ~18.95 lakh orders by FY30.
-
Hospital Unit Economics: Offline facilities reach operational break-even at 20–30% bed occupancy. Inpatient monetization is driven by cross-selling proprietary medicines, which is expected to lift average revenue per bed per day to ~ INR 8,000 - 10,000.
-
Capital Structure: The company completed a Qualified Institutional Placement (QIP) in May at INR 172 per share, bringing institutional backing and funding the near-term hospital rollout.
Key Risks & Critical Variables
-
Heavy Customer Acquisition Costs (CAC): Digital marketing and advertising consume 40–42% of total revenue. The business is heavily reliant on Meta (Facebook/Instagram) ad algorithms and ad-pricing dynamics; any regulatory clampdowns or digital policy shifts represent an immediate top-line risk.
NOTE: This being substantial cost is not expected to reduce as the advertisement cost on meta itself gets higher . -
Hospital Execution Risk: Scaling from a single 30-bed center to 1,000 beds across multiple states by FY28 requires managing clinical staffing, licensing, regional variations, and facility partnerships.
-
Mitigating Factors: Leadership (Promoter Mr. Chadha) demonstrates clear visibility over unit economics and conversion metrics. Additionally, the company is implementing AI-driven customer profiling tools designed to lift advertising ROI by 4–5% .
-
-
-

Promoter Background & Management Assessment
- Promoter Leadership: The business is led by Mr. Chadha, who oversees strategy, product formulation, and capital allocation. Management exhibits a strong grasp of performance marketing unit economics, conversion funnels, and customer retention dynamics.
- Management Execution & Outlook: Recent investor interactions reflect high management confidence in executing the planned hospital rollout and scaling bed counts without taking on balance-sheet-heavy debt. Operational strategy is focused on leveraging proprietary digital funnels to maintain steady occupancy rates across newly commissioned facilities.
Competitive Landscape & Peer Comparison
While the broader Ayurvedic sector is validating the hospital and clinical inpatient model, players diverge significantly across therapeutic niches, manufacturing integration, and expansion routes:
-
Jeena Sikho (Market Leader – Institutional Inpatient Model):
- Scale & Network: Operates an extensive network with over 330 Ayurvedic clinics/centers and a 3,000+ bed hospital chain (450 additional beds in the pipeline).
- Therapeutic Focus & Moat: Concentrates primarily on chronic lifestyle, kidney, and liver ailments, supported by government and institutional tie-ups (CGHS, Central Armed Forces) and private insurers (HDFC ERGO, Star Health). Also operates a pet care division and conducts community wellness camps.
- Operating Model: 100% outsourced manufacturing across all SKUs. Operates a defined patient acquisition chain: Medicine $\rightarrow$ Outpatient Clinic $\rightarrow$ Inpatient Hospital.
- Contrast with Satkartar: Satkartar maintains a non-exclusive MoU with Jeena Sikho to cross-divert patients for a ~15% commission, leveraging their established institutional footprint rather than competing head-on in chronic care.
-
KRM Ayurveda (Integrated Multi-Speciality & B2B Panels):
- Scale & Occupancy: Multi-speciality hospital network of 246 beds across 7 hospitals. Blended occupancy stands at 69% (mature units operate above 90%, while newly added units ramp at 35–40%).
- Institutional Tie-Ups: Strong corporate and public panel penetration, including auto majors (Maruti, Honda, Hero Motors) and a multi-year pilot with the Ministry of Defence.
- Product Portfolio: Regulatory clearance for 300 SKUs (capsules, tablets, syrups, oils) with 80 commercially active products backed by 100% in-house manufacturing. Expanding into daily preventative wellness with 15 FSSAI-approved food-supplement products.
-
Vaidya Sane Ayurvedic Lab / Madhavbaug (Cardiac & Metabolic Reversal):
- Clinical Specialization: Focused strictly on non-invasive reversal of chronic cardiac and lifestyle metabolic disorders.
- Hybrid Inpatient & Outpatient Model: Operates 320 clinics (250 franchise-owned, 70 company-owned) alongside 6 residential hospitals (4 owned, 2 franchised, comprising 134 owned beds).
- Playbook: Uses an asset-light franchise model where the company supplies clinical protocols, proprietary medicines, diet kits, and tech stacks, while local franchise doctors manage direct patient relationships.
-
Kerala Ayurveda (Global Footprint & Classical Formulations):
- International Differentiation: Unlike regional domestic players, Kerala Ayurveda has established an international presence across the US, Singapore, Indonesia, and Europe.
- Tri-Segment Model: Operates across three divisions—a portfolio of 400+ classical and proprietary in-house herbal formulations, wellness clinics/resorts, and an accredited US wellness academy.
Strategic Contrast for Satkartar Life:
- Therapeutic Whitespace: While peers focus heavily on general chronic ailments (Jeena Sikho), corporate multi-speciality panels (KRM), or cardiac reversal (Vaidya Sane), Satkartar targets infertility, which delivers ~80% of revenue at its flagship Delhi center.
- Acquisition Efficiency: Rather than relying entirely on physical camps or ground-level doctor networks, Satkartar leverages a digital-first D2C funnel, converting high-intent online traffic into offline hospital admissions.
Sharing my model for reference :


Disclosure : Not holding any shares in Satkartar Life.