Sambhv Steel Tubes - Emerging Backbone of India’s Infrastructure Boom

Thanks for inputs. A few points here:

  • ERW Pipes and Tubes realization obviously is directly a part of Steel price fluctuations which vary almost each month. Steel prices have struggled in Q2, a bit of drag should be visible on the realization and on the EBITDA/Tonne front.
  • GI/GP Pipes realization again a bit stretched. It should be close to 70-72000 odd per tonne. Also feeling the heat of stressed Steel prices.
  • SS Coils and Sheet- Avg realization rather here have ranged between 120,000 to 125,000 per tonne which should grow as they start catering to 304 and higher variants. So a good respite here.

Stainless Steel again is a very specialized play with limited entrants, Deep technical and operational efficiency needs and benefits such as higher EBITDA per tonne and better acceptance in the markets. The EBITDA per tonne in the segment could do 13k-16k depending upon the SS market which has come a bit alive in FY26 after a very poor FY25 (Jindal Stainless calls are a beast to understand things better). Although the industry is still demanding restrictions on Chinese imports for time being but it can take anywhere between 8-12 months for something concrete to come around.

Sambhv has a lot of leeway to grow their SS segment mind you Jindal at such large volumes is able to grow almost double digits each year (Fy26- 9-10% and FY27 for now is expected at 9-10% as well). The transition from ERW and GP to SS and GP(in terms of percentage split) will help the company maintain higher margins and lower coorelation to steel prices (SS Scrap prices impact will inch higher).

Regarding the new capex, the internal accruals rightly will form good enough chunk it seems and they always can take debt to cater the expansion. Going by the history they’ve done pretty solid ramp up with the last debt they undertook and have been able to bring about excellent operational and financial strength to the balance sheet. The bet in largely any steel company always is on the balance sheet strength and timely execution of the capex followed by successful acceptance of the products which leads to a profitable utilization at plant level hence making it a cash cow.

Having followed the promoters during their interviews and plant visits- They seem to have everything in place, been able to do a commendable job in maintaining all KPIs till now. Reaching scale in such short time with such balance sheet is not as easy as it appears for a traditional manufacturing business. I am fairly bullish on the prospects and believe that the company is an innovation driven business and going by the trends it seems but obvious that they’ll keep catering to newer segments in future as well.

Invested and Biased.
12 Likes

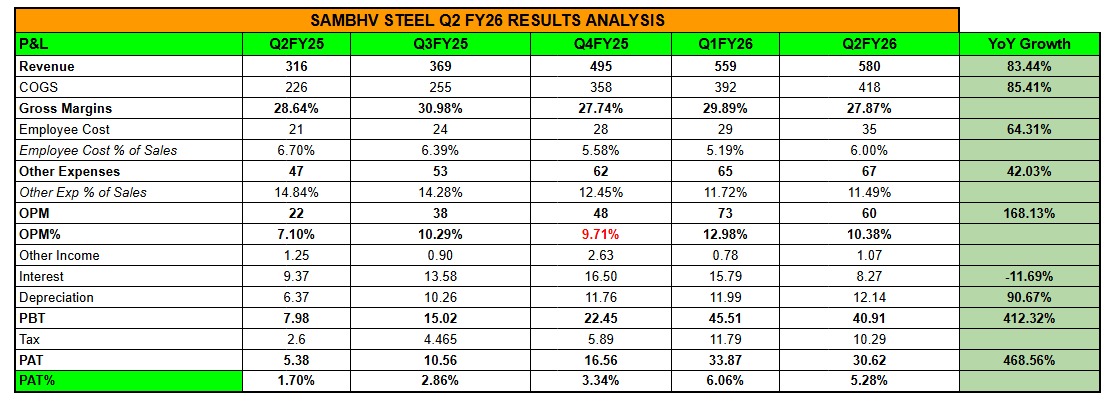
Sambhv Steel Q2 Nos are out:-

3 Likes

Q2 Earnings Call Highlights:

  1. Over the next 4-5 years, a fully integrated facility with a total finished product capacity of 1.2 million tons per annum will be developed in phases, with Phase-1 targeted to be commissioned by Q4’27.
  2. Phase I- 3,60,000 tons per annum of stainless-steel coil with backward integration for which around Rs. 810 crores will be invested, around Rs. 125 crores will be invested for additional 25 MW power plant for cost efficiency. (Debt + Internal funded) - Revenue potential 2400-2800 Crores.
  3. Out of 935 Crores total capex, 200 Crores incurred, 600 Crores odd debt and rest internal accruals.
  4. Given soft prices, EBITDA per tonne guidance at 7000 Rs for whole year.
  5. On why SS capex vs MS?- Stainless demand is growing fast, there is not much production in the market in India and operational efficiency will grow for the company with scale.
  6. Realization in SS 300 series vs 200 series - 1.25 Lakh per ton in 202 series and 1.85 Lakh per ton in 304 series.
  7. ERW series- 6000-7000 EBITDA per ton, GP- 1500+ ERW margins, SS broadly 14-15000 per ton.
  8. On EBITDA margins- 12-13% sustainable, SS margins on Absolute are higher but on percentage almost at par with Pipes.
  9. EBITDA per ton in the quarter was down due to moisture effect in Iron ore and
  10. Guidance: 4500 Crores revenues in FY28 with 10-13% EBITDA margins.
  11. Post capex revenue split:- 60-65% from SS division and 30-40% from ERW and GP pipes.

Overall with this new capex announcement with complete focus on stainless steel- the company will transition to become a large stainless steel player in the country and the current HR Coil led cyclicality to a large extent will be shifted to SS market dynamics. Seems like a good pivot to focus on higher EBITDA per tonne segment and grow operational efficiency with scale.

Disc: Invested

9 Likes

Go India Small Cap Day - Sambhv Steel & Tubes Ltd.
A very insightful webinar for deeper understanding of the company — a must-watch.
Disclaimer - Not Invested, but interested in investing.

2 Likes

Company announces expansion plan for Cold Rolling Mill (CRM) with Bright Annealing (BA) Line and Continuous Galvanizing Line (CGL), Situated At Village Kuthrel, Tehsil Raipur, District Raipur, Chhattisgarh– (“Kuthrel Unit”).

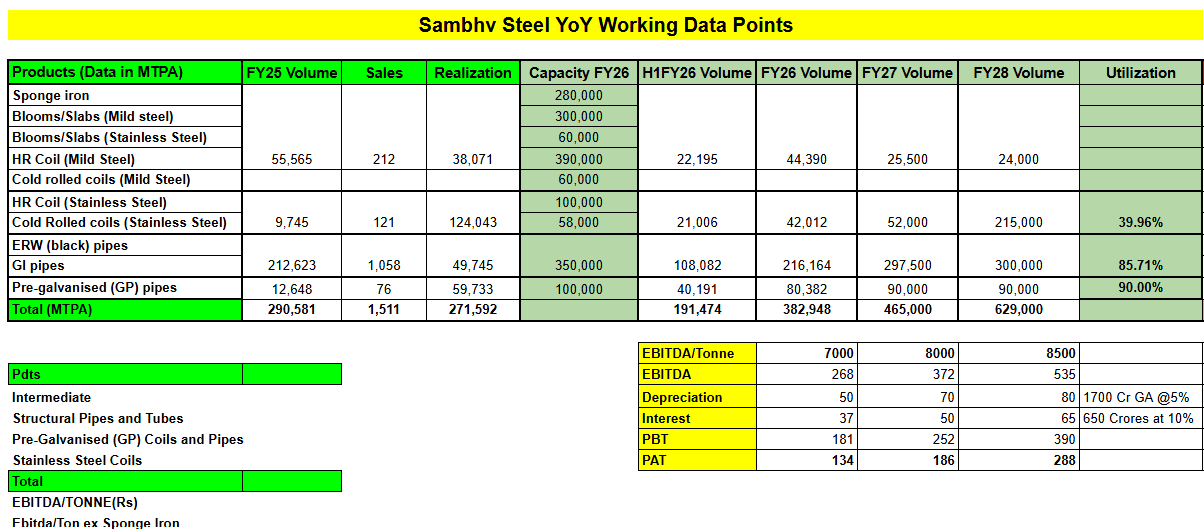
Have been able to work a bit on the numbers front ex latest announcement:-

The company has pivoted completely to focus on the Stainless Steel segment for next 2-3 years atleast as per their capex plans. EBITDA per tonne profile should better itself each year courtesy the SS segment gaining significant share in revenues. Being an integrated player has significant advantages in a time when the steel prices are hovering at around 5 year lows (Steel prices hit 5-year low! Value drops sharply; top factors for steep fall - The Times of India).

Interesting to see how the current dynamics play out for Non- integrated ERW manufacturers vs the Integrated players like Sambhv Steel. In any case, increase in Steel Prices eventually will help absolute numbers both on realization and EBITDA per tonne front. What we’re seeing is the numbers during a very tough market environment wherein the prices of Iron Ore (the key RM) haven’t fallen as much as the HRC prices which guides the pricing of the end products.

Nonetheless, considering a 40% utlization in FY28 on the new capex- the EBITDA per tonne on blended basis can be 8500-9000 to be on conservative side- EBITDA number can range between 550-600 Crores depending upon market scenario. FY29 later will be the peak capacity utilization year for which one can expect maybe 70%+ utilization.

Overall a possibility of EBITDA 3.5x-4x (FY25 base) and 4-5x PAT (FY25 base) seems like very much doable if everything falls in place in the next 3 years.

Disc: Invested

7 Likes

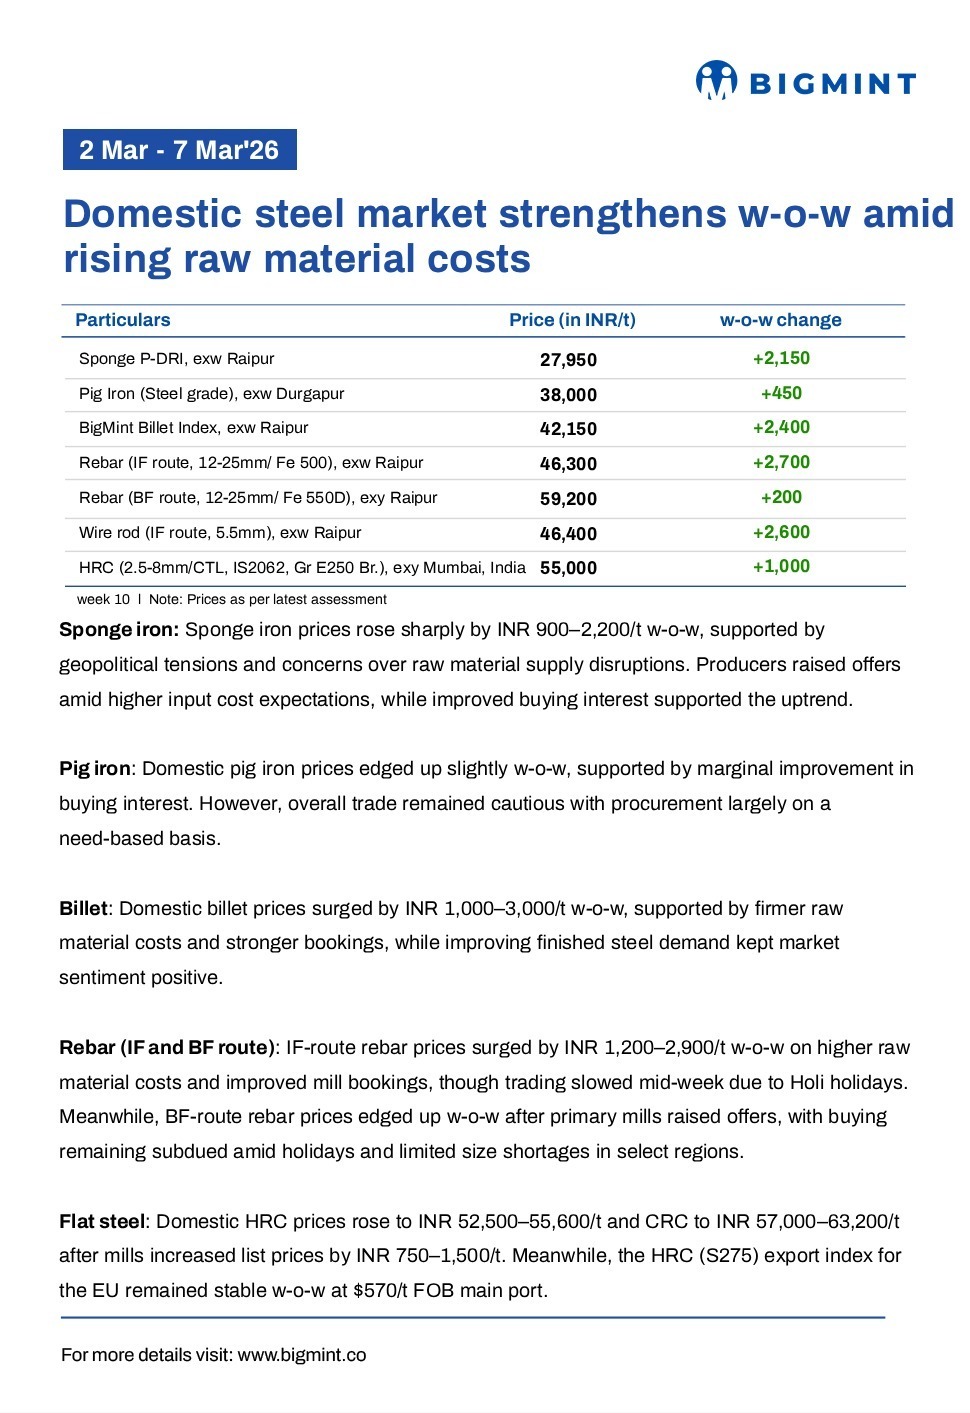
Some positive move in the steel prices finally.

Mills raise flats prices: Leading mills raised list prices of hot-rolled coil (HRC) and cold-rolled coil (CRC) by INR 750-1,000/tonnes (t) in the week ended 19 December, after keeping them stable for sales in the beginning of December compared levels prevailing during end-November.

https://www.bigmint.co/insights/detail/bigmints-india-steel-index-rebounds-before-year-end-positive-momentum-may-continue-707809

4 Likes

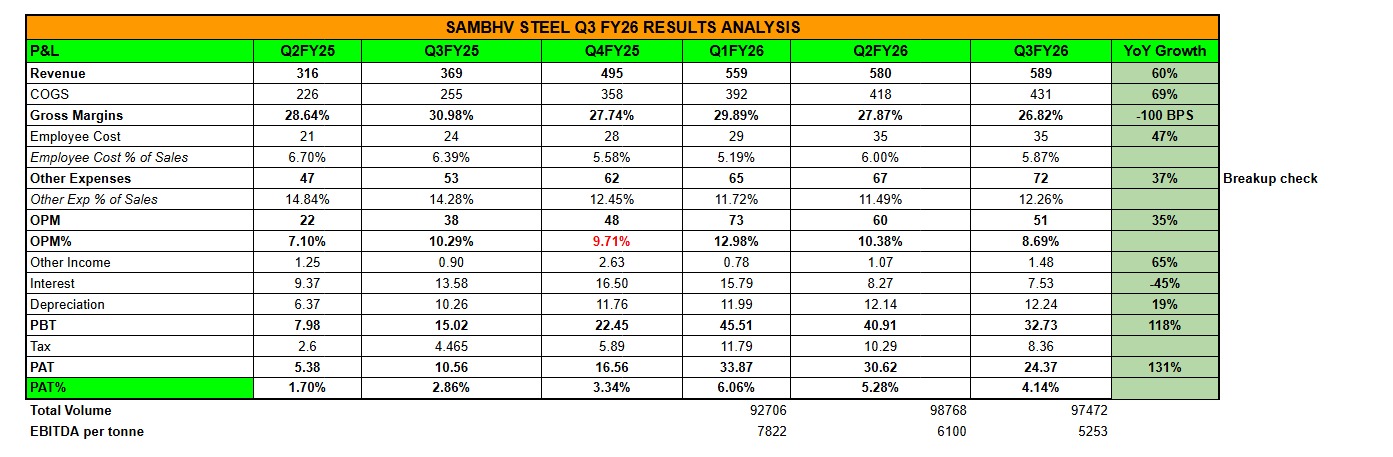
Q3 sales update reported by company. Good jump YoY. However QoQ flat - 15% higher volume of SS which is having higher EBIDTA & minor dip in pipes, tubes category. QoQ good ramp up seen in SS which is going sign particularly when they are targeting huge capacity addition in this segment.

Off late good recovery in steel prices, also government policy to impose 12 to 11% import duty will be supportive for the industry. However no decision of same for SS product. However concall highlighted about compulsory ISI certification is helping local players. However as steel prices started rising in late december, Q3 result might be similar to Q2 in terms of realization.

My take - FY27 will be consolidation phase for Sambhv bcoz not much new capacity addition is coming. So YoY growth will be tapid 10-15% by achieving maximum utilization level. Game changer will be FY28 onwards. If import duty comes in SS category along with new capacity addition that will be bonanza.

Valuation is now reasonable at 25 pe on TTM EPS which is inline with Jindal stainless steel (After FY28 it will be more ss company than steel company so comparing with JSS). Also recent uptick is steel prices supporting all steel company stock price (e.g. APL apollo at ATH). However FY27, we might see higher interest, depreciation & staff cost before actual sales comes in FY28. If stock remains rangebound till that time, it will be great buying opportunity.

Yesterday, stock locked-in ended for almost 1385 cr. (Almost 50% market cap) - may be that’s why stock fell.

Disclosure: I entered yesterday for tracking position. I will wait for better price/time to buy more.

With increase in ERW prices along with HRC prices uptick- I believe Sambhv should be able to post a good Q4 set. Hopefully, steel prices to sustain at these levels breaking upwards from the downward trajectory.

Q4 Guidance at Rs 7500 Ebitda per tonne.

Disc: Invested

6 Likes

Steel prices continue to trend higher.

4 Likes

Can some one comment on my thesis/anti thesis -

I think market is assuming ~600-700cr of debt for next capex plan and by looking at my base case scenario for mid FY29, they will do intotal of 550cr of EBIDTA(took margin at 9.5%). Is this already priced in by market as I can see a clear de rating of valuation for this?

Got the debt figure from management from call - https://www.youtube.com/watch?v=HplvU5EKDyA

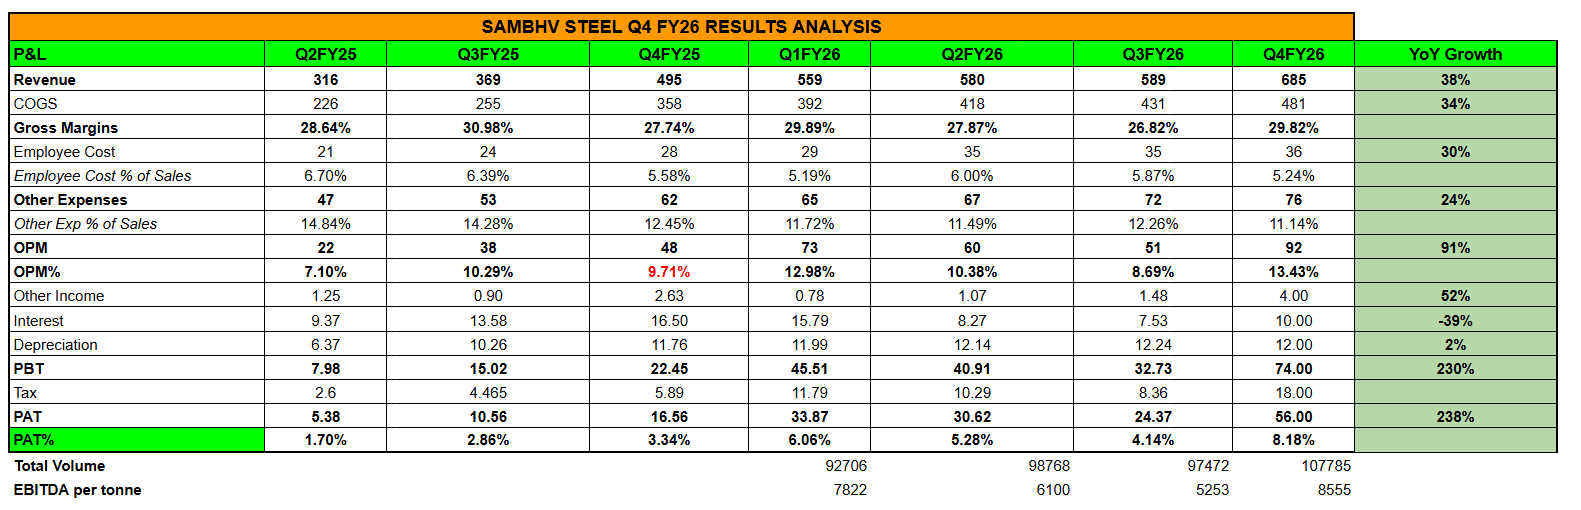
The numbers came in- Highest ever quarterly numbers. Felt like the concall was also the best they’ve done till date. Major capex going live in Q4FY27 and a utilization north of 40% for FY28 is all one need to understand next year’s trajectory. Some hints to the longer term journey provided in the call.

Concall Highlights (AI structured):
Capex remains on track for Q4FY26. Brownfield SS CR coil and ERW pipes expansion progressing well, with SS CR debottlenecking completed to 1.18 lakh tonnes and ERW pipe capacity moving from 3.5 lakh tonnes to 5 lakh tonnes.

Out of the announced ₹930 Cr capex, around ₹630 Cr is still pending deployment. Company has tied up ₹675 Cr term loan for Kesda.

An additional ₹200 Cr capex has been announced this quarter. Management expects ₹60-70 Cr annual power cost savings and overall ₹100-120 Cr cost benefits post completion. Around ₹150 Cr of this additional capex will be debt funded.

Sarora is expected to become 100% self-sufficient post this capex, while Kesda was already expected to achieve self-sufficiency after existing projects.

Management remains comfortable with leverage near 1.5x forward EBITDA. Peak debt expected at ₹800-900 Cr.

FY30 vision includes 10 lakh tonnes MS, 3 lakh tonnes coated products and 7 lakh tonnes SS coil capacity, taking finished products capacity to ~2 million tonnes. Targeting 10-12% market share in both MS coil/pipes and SS capacity.

Management also intends to add 2-3 new products over time. Phase-2 capex is not yet quantified. Additional ₹300-400 Cr capex may be announced by FY28 depending upon execution of current projects.

Company signed MoU with Ministry of Steel for higher value-added products. PLI benefit of ~₹200 Cr expected by Q4FY27 and can be availed over 3-4 years.

Six additional co-branding MoUs signed, taking total to 10. Current contribution is 1200-1500 tonnes/month, with target to exit FY27 at 2500 tonnes/month.

Product mix continues to improve towards value-added products.

Cash conversion cycle remains strong at ~17 days. Management expects working capital cycle of 17-25 days in FY27, increasing to 25-30 days in FY28 due to higher SS contribution.

Management indicated 50-60% of price hikes flow directly to EBITDA, while the rest is absorbed through higher RM cost and dealer discounts.

Company does not expect HR coil prices to revisit ₹45-46k/tonne levels.

No impact seen from LNG/PNG disruption.

Company currently holds ~₹100 Cr liquid investments in mutual funds. Post MS capex, management expects 20-25k tonnes/month to be met through in-house HR coil production, while another 5-10k tonnes/month may still need to be procured externally.

PLI approval for seamless segment has been received and project is currently in planning stage.

Company currently operates in narrow-width SS, whereas larger players like JSL operate in widths up to 2-2.5 metres, limiting overlap in use cases.

Q4 EBITDA/tonne was elevated due to lower inventory costs and stronger end-product realizations.

Q1 FY27 EBITDA/tonne guidance is ₹7500-8000. FY27 guidance maintained at ₹7000-8000 EBITDA/tonne with 10-15% volume growth over FY26.

Q4 realizations were: SS200 at ₹120-135/kg, SS300 at ₹180-190/kg, Black pipes at ₹55-60/kg and GP pipes at ₹65-75/kg.

Current realizations are: Black pipes at ₹57-60/kg, GP pipes at ~₹75/kg, SS200 at ~₹135/kg and SS300 at ₹200-210/kg.

FY27 utilization guidance stands at 60-65% for SS, 65-70% for MS and 80-90% for GP.

FY30 targets include ~60% utilization with EBITDA/tonne of ₹8-9k and EBITDA margins around 12% (+/-2%).

Kesda capacity utilization is expected to ramp up gradually, with FY28 likely ending at ~40% utilization on a full-year basis by Q3/Q4 FY28.

MS expansion utilization in FY28 is expected at 60-70%.

11 Likes

I spent some time analyzing the Q1 FY27 performance and management commentary for Sambhv Steel Tubes Ltd. While the structural steel tube sector faced localized headwinds (e.g., labor shortages, channel destocking due to steel price movements), Sambhv delivered a strong quarter driven primarily by higher realization in value-added products (VAP) and backward integration benefits.

Here is my detailed synthesis of the numbers, segment execution, management guidance, and key monitorables.

1. Key Financial Highlights (Q1 FY27)

Revenue from Operations: ₹7,322 Mn (+31% YoY, +7% QoQ)

Operating EBITDA: ₹952 Mn (+31% YoY) with Operating EBITDA margins holding steady at 13.00%

Operating EBITDA/Ton (Ex-Sponge Iron): ₹10,002 / Ton

PAT (Excl. Exceptional): ₹566 Mn (+69% YoY)

PBT Margin: Expanded significantly to 10.50% (up from 8.06% YoY), aided by higher other income contribution.

Cash Flow Conversion: Cash Flow from Operations came in at ₹922 Mn, reflecting a strong 97% conversion of Operating EBITDA.

2. Segment Performance & Operational Trends

Total sales volume for finished goods reached 107,771 MT for the quarter.

Structural Pipes & Tubes (ERW Black / GI / CRFH):

Sales volume stood at 56,617 MT (highest-ever recorded quarterly volume for this segment).

Demand continues to be backed by infrastructure, building/construction, and OEM activity.

Stainless Steel (Slabs / HR / CR Coils):

Sales volume came in at 14,760 MT.

Production of HRAP/CR coils reached 42,424 MT.

The company has successfully signed 18 new MoUs under the “Sambhv” co-branding model (taking total partners to 28), which acts as a key pull factor for converting pipe manufacturing demand.

Pre-Galvanized (GP) Coils & Pipes:

Sales volume stood at 29,814 MT.

GP Pipes utilization currently sits at 56.7%, leaving ample room for organic volume ramp-up without immediate heavy capex.

3. Management Guidance & Expansion Roadmap

Brownfield Structural DFT Expansion: Management is deploying ~₹500 Mn capex toward a 150,000 MTPA Direct-Forming Technology (DFT) structural pipe facility. This will allow them to cater to higher-margin customized rectangular/square sections.

Stainless Steel CR Coil Expansion: Consents to operate (CTO) have been granted, officially doubling Cold Rolled (CR) coil capacity to 116,000 MTPA.

Geographical Push: Strategic focus is on expanding market share in the southern/coastal belt (Kerala, Tamil Nadu, Andhra Pradesh, Goa, and Maharashtra) for GP products.

Working Capital & Balance Sheet: Working capital cycle extended slightly to 21 days (up from 17 days at FY26 end). Net Debt / EBITDA stood at 1.00x (up from 0.78x in FY26) due to active capex deployment, though annualized ROCE improved to 21.92%.

1 Like

Any forward financial calculations for FY27 and FY28

Q1 FY27 was strong, with revenue at ~₹732 Cr and EBITDA at ~₹95 Cr. The important point for me is that EBITDA/tonne has improved materially, while margins have remained around 13%.

I don’t want to simply annualise Q1 and assume ₹225 Cr+ PAT for FY27. I think a more reasonable base case is ₹170–180 Cr PAT in FY27.

The bigger story, in my view, is FY28.

The stainless-steel expansion at Kesda is expected to start contributing from FY28. If commissioning happens on schedule and utilisation ramps up reasonably, I think revenue can move towards ₹3,500–3,800 Cr, with PAT potentially reaching ₹250–280 Cr.

What I am watching

Parameter

What I want to see

Revenue growth

10–15%+

EBITDA/tonne

₹8,500–10,000+

EBITDA margin

12%+

FY27 PAT

₹170–180 Cr

FY28 PAT

₹250 Cr+

Net Debt/EBITDA

<2x

Kesda project

On-time commissioning

Stainless utilisation

Fast ramp-up

At around ₹131, I don’t see a huge margin of safety if I assume only FY27 earnings. The valuation becomes more interesting if we believe the FY28 earnings ramp.

So for me the thesis

Steel company growing fast.

It is:

Can Sambhv successfully move towards higher-value products + stainless steel, while maintaining ₹8,500–10,000+ EBITDA/tonne and controlling leverage

If yes, FY28 could look quite different from FY26.

Risks: capex execution, debt increase, working-capital requirements, steel-cycle downturn, lower-than-expected stainless utilisation and margin compression.

At ₹131, I would prefer to accumulate on corrections rather than chase. I would also wait for the next 2–3 quarters to validate the FY27 numbers before giving too much weight to the FY28 bull case.

Dis- invested

6 Likes

JTL – Powersol Metalcraft loan/advance clarification

Going through JTL FY26 AR, I noticed a discrepancy around Powersol Metalcraft:

  • FY25 opening balance: ₹18.13cr (Section 186(4) disclosure)
  • FY26 loan given: ₹24.15cr
  • Expected balance: ₹42.28cr
  • FY26 closing “loan & advances”: ₹98.20cr
  • Unexplained difference: ₹55.92cr

Note 40/42 doesn’t explain the movement sufficiently. The AR also shows Powersol interest income of ~₹65.5 lakh, with the balance apparently unsecured.

The cash-flow statement is also interesting: “Movement in Loans” is a ₹12.53cr net inflow, despite the loan/advance balance increasing substantially.

Does anyone familiar with JTL/accounting disclosures have a view on what could explain the ₹55.92cr difference and the ₹12.53cr loan movement?

Also, would the SEBI Regulation 23(9) RPT disclosure provide the missing nature/purpose/tenure/rate/security details?

No bro I’m tracking sambv steel tubes only for jtl may be you should new topic people who are tracking would see will comment