-
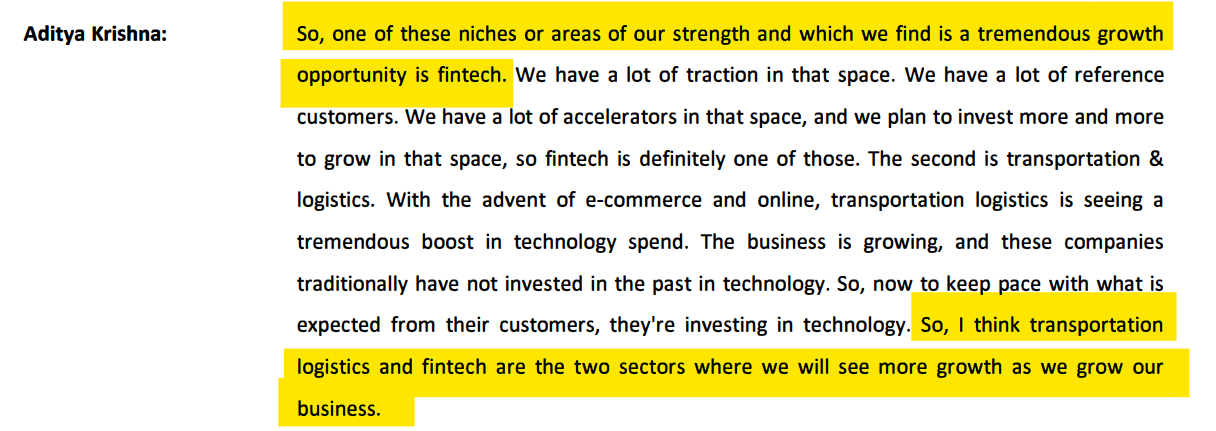
Transportation Logistics and Fintech two-sector where they will see more growth
-
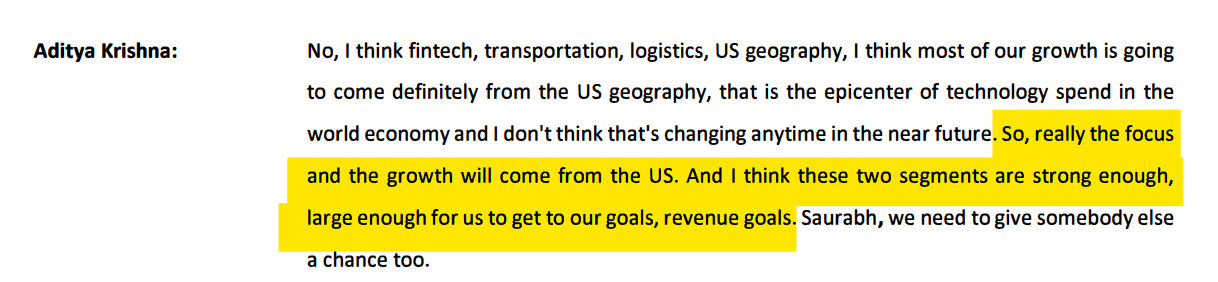
Focus and growth will come from the US
-
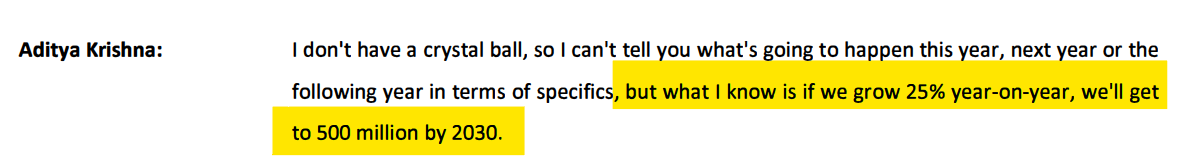
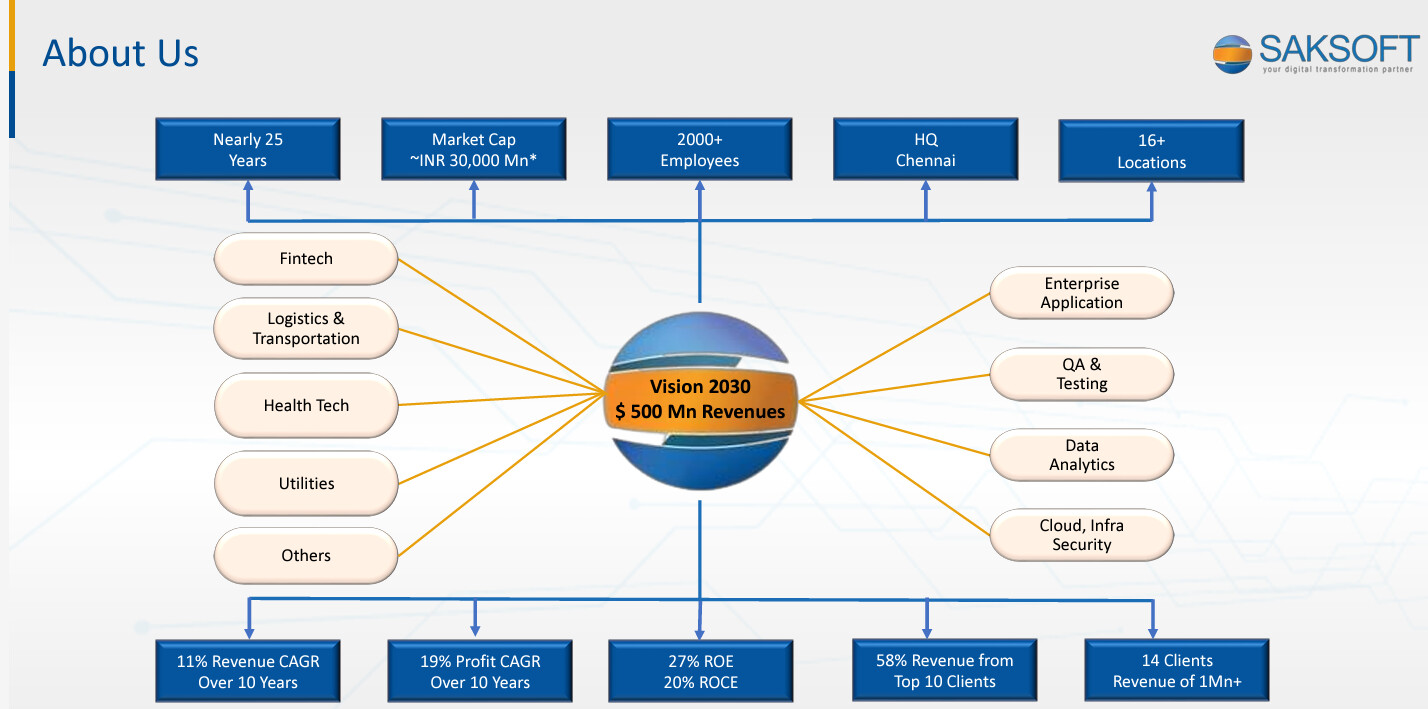
If they grow 25% YOY, They will get 500 million by 2030
-
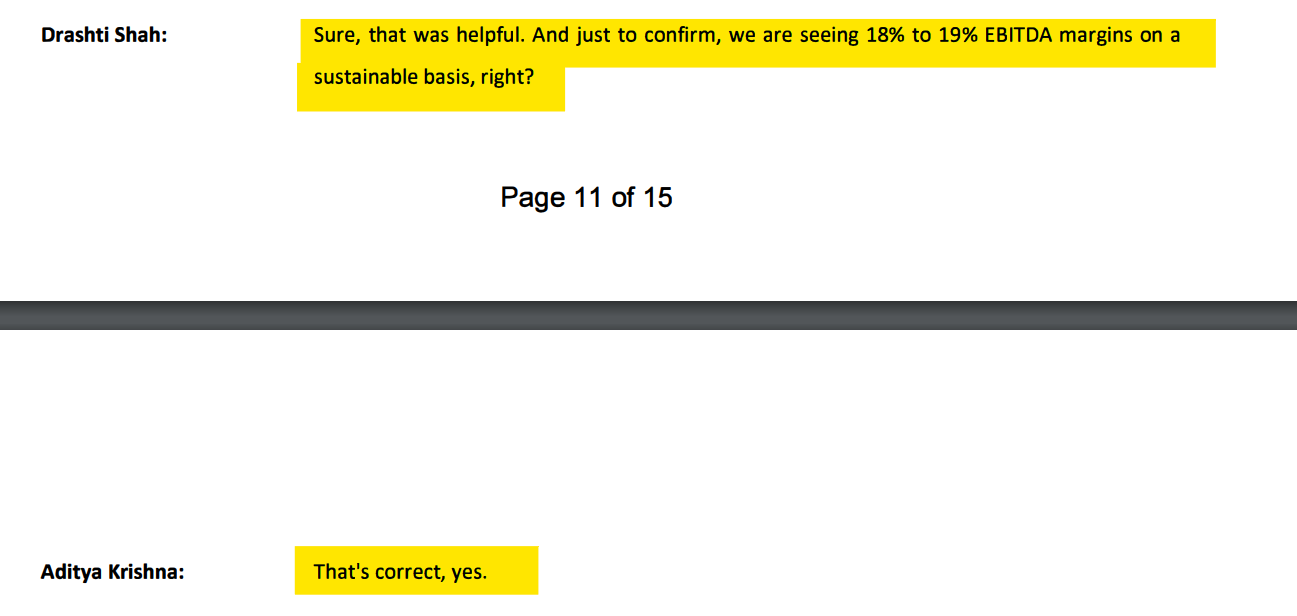
Seeing 18% to 19% EBITDA margins
-
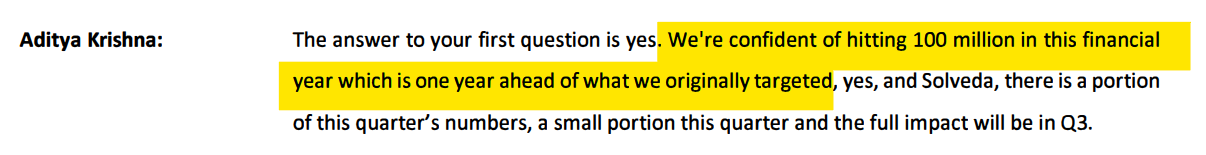
Confidence of hitting 100 million in this financial year
4 Likes
Promoter of happiest mind is very old , A trust founded will work as his successor.
1 Like
Q3 Concall Highlights:
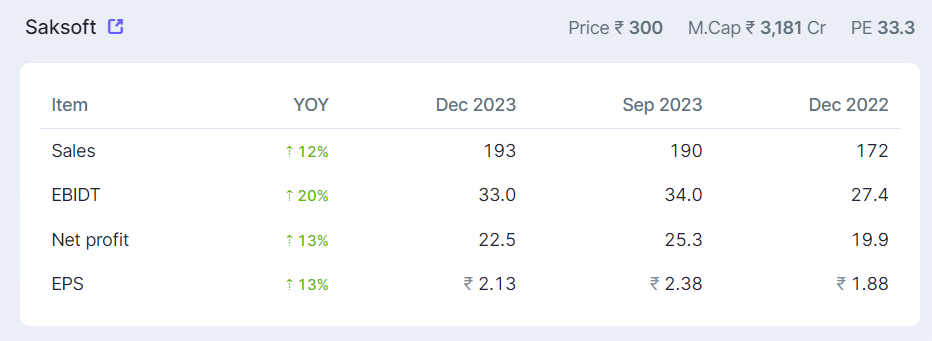
EBITDA margin reduced due to choose to invest in sales engine to achieve $500mn revenue vision by 2030.
Q3 was tough due to US market head wind, recruitment cost of new employees to achieve $500mn. Q4 will be good, but head winds are there. It is reality check, as wake up call to make company stronger.
All acquired company were profitable when acquired and are profitable now.
Anticipated interest cut in US helps to spur demand.
Q4 EBIDTA margin at 18% is aspirational.
In short, company aspire to grow 22 to 25% to achieve $500mn revenue by 2030.
Disclosure: Invested
4 Likes
Q2FY25 Highlights:
- Revenue grew 7.1% q-o-q from 201 to 215 crores, although majority of it came from the acquisition of Augmento
- EBITDA at 17.08%: Lower than 18% because they gave wage hikes in July. Management said that they should see the margin back at 18% next quarter.
Management is now guiding between 870-1000 crores for FY25. They have confirmed that they have enough order book to meet 870 crores, however 1000 crore mark might be a bit difficult. They would still be able to reach close to that mark if the sales team they have been working on for past few quarters start delivering result.
Wrote my detailed thoughts here:
3 Likes
Looking for the financial model of Saksoft. Can anyone help me out?
Sharing some notes based on my study of fundamentals and technicals of the company :
FY25 Consolidated Balance Sheet total of ~₹1000 crores is made up of :
- ₹490 crores of Goodwill (Intangible asset which is recorded when Purchase Price paid for an acquisition is greater than its Fair Value of Net Assets).
- ~₹200 crores of Cash & Cash Equivalents
- ~₹194 crores of Trade receivables.
- Remaining is in other assets
On the Liabilities side, ₹620 crores in Equity, ₹105 crores in Non Current Liabilities, remaining in Current Liabilities.
Market cap of ₹2600 crores is a little more than 4X Book Value.
Revenue guidance for FY26 is a ₹1000 crores which should translate to a PAT of ₹123 crores going by FY25 PAT margin of 12.3%.
Longer term revenue guidance of $500Mn which is ~5X from FY25. If this is achieved (looks ambitious given sales have grown ~2.5X in last 5 years) while maintaining the current valuations, Mcap of the company could be ₹12000 crores which makes this a potential 5 bagger.
Company guided for ₹870-1000 crores revenue for FY25 in Nov’24 and achieved the lower end of that guidance.
Company is advertising fancy product themes around AI, Cybersecurity, Data Analytics etc. on its website.
Operational Cash flow of ₹111 crores and ₹117 crores in last FYs gives confidence of healthy cash generation seen in context of PAT.
Fundamentally, low leverage, high margins, good growth promoter-driven business in the right product segment. Valuation of 24x PE is higher vs Median PE of 20x suggesting that market is buying the mgmt story so far.
Institutional ownership is low for my preference at <3%; 68% by promoter entities, 4% by employees and rest by public.
Technically, stock is at its 20ema on the monthly chart after testing previous swing low of ₹120 in April. Volumes are thinning although bullish May candle gives some hope. Double top at ₹280-300 levels is a big resistance suggesting stock has limited upside in the near term. Chart is likely to move in line with Nifty IT index which is currently at ~50% retracement level of its 35% decline since Dec’24.
Key risk is obviously the quality of acquisitions and the risk associated with Goodwill write offs/revenue loss if acquisitions lose their commercial ability due to tech disruptions, consolidations etc. Has someone dug deep into in already? (Trying to piggyback  )
Disclosure : Invested with a 1% pf allocation
4 Likes