Prevest Denpro Limited

May 2022 - FY22 Year End Call
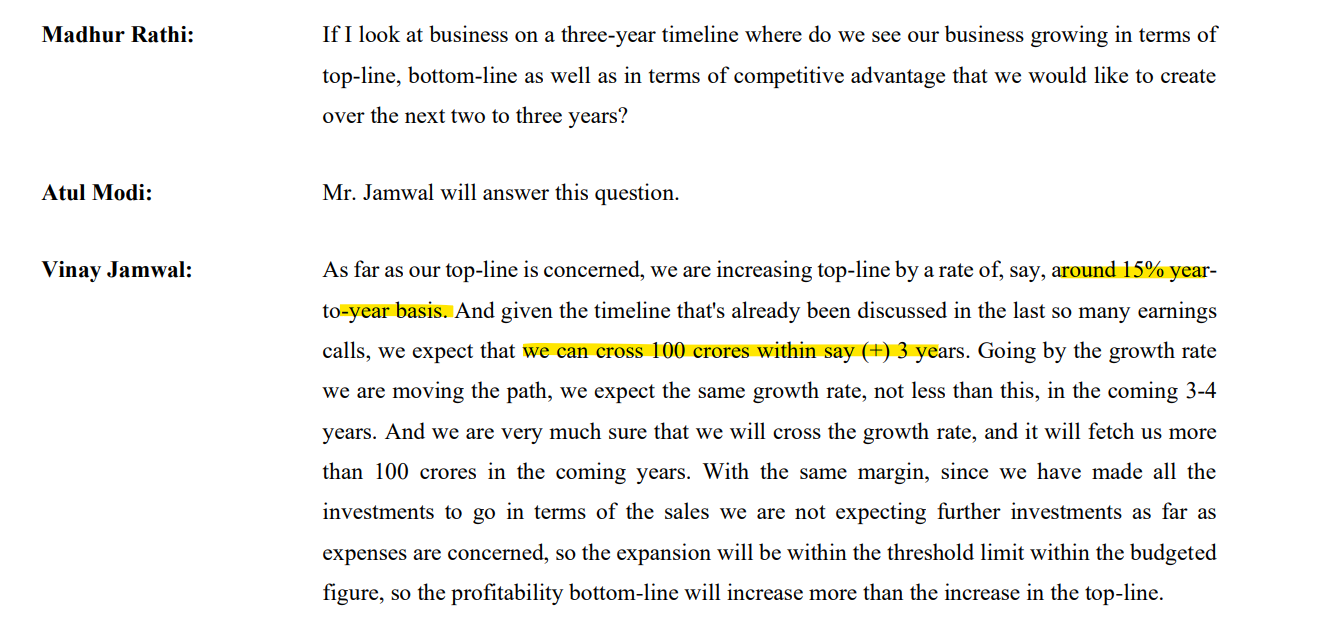
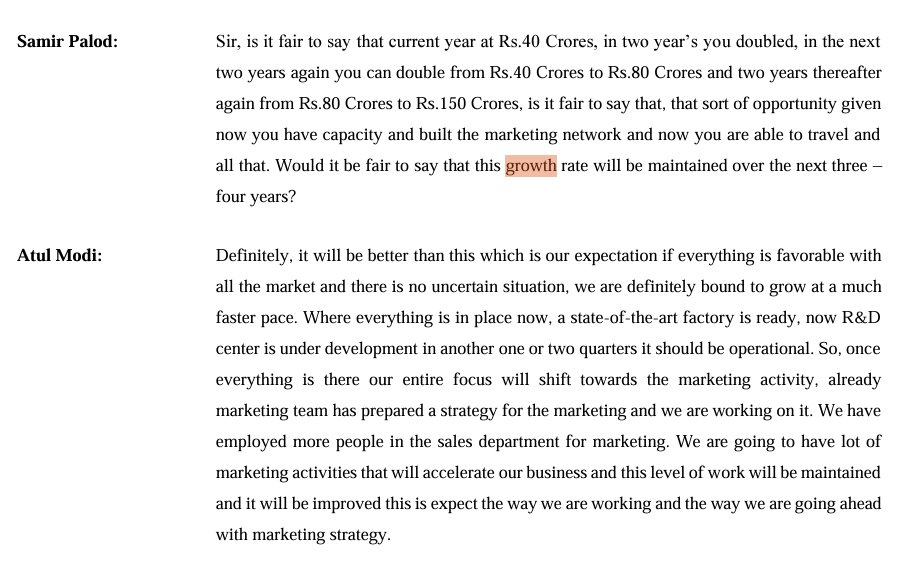
Atul Modi saying they can more than double FY22 revenue of Rs38 crores in 2 years and then double again to Rs150 crore. Two years later we are at Rs 56 crs

Company had mentioned they will maintain margins. Margins came down from 40% to 34% in 2 years

May 2023 - FY22 Year End Call
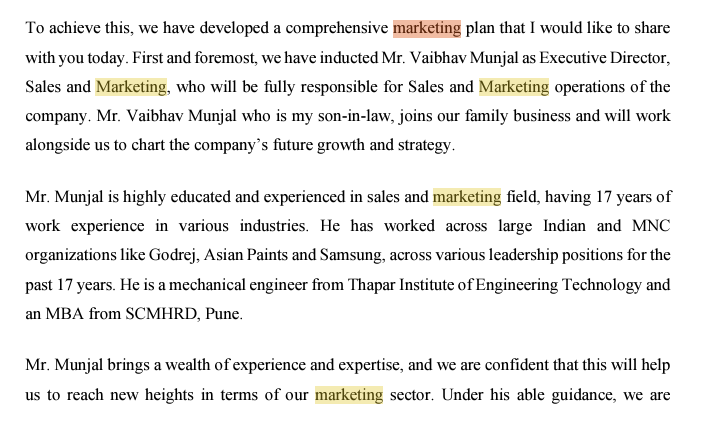
Heights of Nepotism. Making son in law ED, Sales and Marketing. What happens next? No sales growth in FY24.

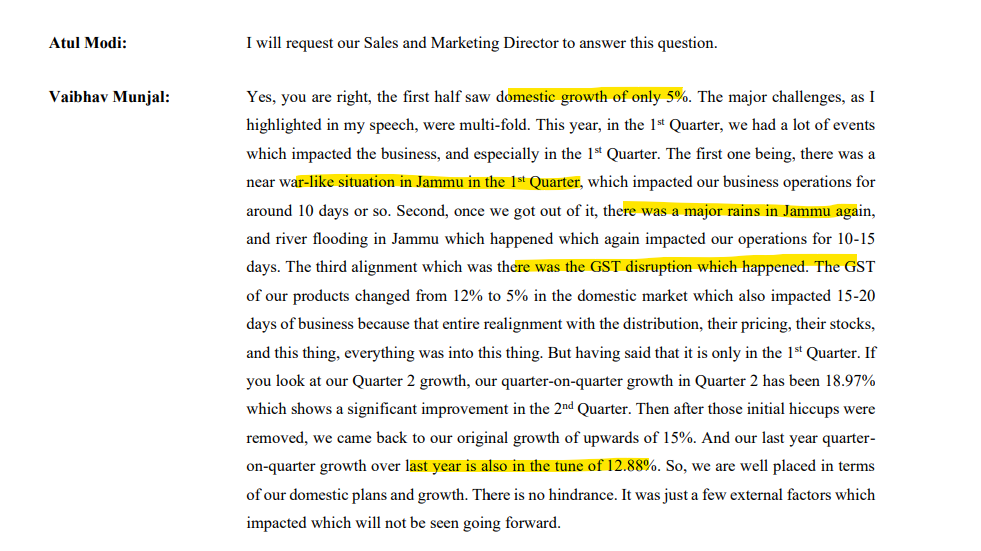
The lack of growth continues in 1QFY25. Why cant such a tiny revenue base not be grown?

9 Likes

I think the reason for no growth in revenues and decline in margins is same…dwindling exports. They used to make more margins in exports. Domestic sales have lower margins.

I was very interested in the company. But was uncomfortable with the high salary drawn by the promoter family, and then S-I-L was also onboarded at a high salary. Thank God I didnt invest.

The promoter has the tendency to say 30-40% Growth like its nothing. I doubt they even understand the challenges they would face if they were to grow at that rate. As per my understanding, their products are not high quality as they claim. They are good and dentists use some of them for certain procedures. But in technically high procedures they prefer brands like 3M, Sirona, etc. The promoter constantly ignores this feedback from various analyst. Good Sector, Good Opportunity, But Prevest is disappointing as of now.

4 Likes

Main point of revenue on a small base not growing - 100% I was wondering the same few quarters post IPO as well. Their market share is low single digits and so definitely a huge opportunity - domestically and internationally. 20 years in the industry and they have not grown that share significantly - either grabbing market share in dentistry is difficult or they have not cracked the business yet.

They seem to focus a lot more on the international business which requires more certifications and accreditations and is higher cost, higher margin business. And they work across so many countries with a small sales and marketing team so they would be spread thin.

A possible rethink on their go to market strategy for growth is essential I believe - the S-I-L has his task cut out!

2 Likes

No post results concall also this time. Has promoter thrown in the towel?

Pls have a look at the latest investor presentation.

Nothing in PPT suggests any reversal in fortunes over the next 3 quarters at the minimum.

The forex crisis company is talking about is not changing, neither is the Israel Hamas war.

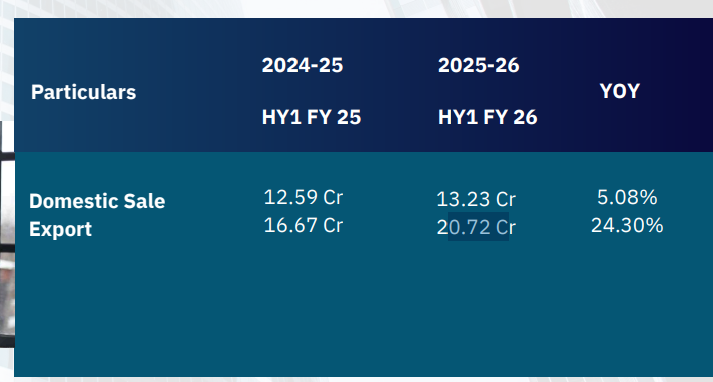
HY1 FY 26

You have done Exhaustive Coverage on the stock, What is your view on New Products introduced by company Like Disinfection and 3D Printing. The company is at very good valuation as they have good ROIC and Free cashdlow

2 Likes
  • Domestic business achieve 9% growth while Export business achieve 17% growth.

  • In H2 domestic grew by 12% while export grew by 11%. Export growth slowed down in H2.

  • Establishment of wholly owned subsidiary in UAE.

  • Commercialization of our disinfectant business. The initial response has been highly encouraging.Q4 FY 2026 was challenging due to destruction in global supply chain.

  • We remain optimistic about opportunity Ahed us. Continued leadership in digital density . Deepening Export market, continue invest in digital technologies.

  • Seeing good traction in Disinfects Portfolio.

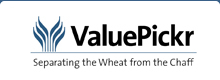
  • In USA : US -37% growth led by private label manufacturing and online sales

  • In Dubai will start online Business also .

  • Company is working at 67% capacity. Can do 125 crore of turnover from current capacity.

  • In domestic front we have increased our distribution network

  • Oradox -2% growth . They have invested IPO money to scale this Business but they were not able to do it because it is more of Direct to consumer product also which was not their strength . Now they are going in new products we need to do check whether they will be able to do same or not this products are directed to doctors only so probabilistic higher chance of succeeding here

  • Digital Dentistry - all the players are at same level and we are same compared to MNC.

  • 162% revenue increase in 3D printing sales and 3D Printing resins growth by 40%.

2 Likes

I too think on the similar lines when it comes to management pay. Nevertheless, I think the business is unique with opportunity/potential very much there domestically as well as in international markets.

Having a detailed, Multi-year Valuepicr thread on any company is probably one of the best resources an investor can have.

Because it allows us to see the complete business evolution over the years, along with so many different viewpoints (bullish or bearish) and many finer details and thoughts which one investor alone cannot have.

Also we can see Whether management delivered on what they promised years ago.

And it is this aspect that has allowed me to reject Prevest as an investment.

At the start of my research I was very excited by the company. 35%+ EBITDA Margins and that too consistent. High ROCE,ROE. Cash rich balance sheet. Strong cash flows and available at fair valuations. Long industry runway for compounding growth and unique products.

Then I did a little scuttlebutt with some of my dentist friends and was pleasently surprised to see almost all of them using prevest products and giving positive feedback. (This was especially positive given I’m from a small city. So, a small company having such distribution outreach, I thought wow)

Then came the annual report and the first huge RED FLAG. Directors remuneration being 23% of PAT!. (Inceasing from previous year and projected to increase further!).This is almost unheard of. I have not seen a single company in my analysis experience to have remuneration this high. (Okay I said, but company is still attractive, maybe a small-medium sized position)

Then i went through the entire thread above. And many things regarding the management became clear.

  1. They make big promises and don’t deliver on them. (100cr sales in 3-4 years, said in 2021. 150cr sales in 3-4 years, said in 2022. 1000cr sales by 2030, said in 2021. They are still at 70cr).
  2. Growth drivers which were supposed to be big, still haven’t had meaningful progess. (US was supposed to be big growth driver in 2023. It’s 2026 and it’s still 1% of their sales. Dental hygiene products were supposed to be big in 2024. It’s 2026 and they’re still scaling up. Margins of 40% in 2024 were supposed to stay and go up but fell to 35% in the subsequent 2 years)

And there’s probably more examples which i have left out.

So, that made me feel that I can’t trust this management (Especially if they’re taking 25% of PAT)

These lines from the above thread were the clinchers for me -

" Heights of Nepotism. Making son in law ED, Sales and Marketing. What happens next? No sales growth in FY24."

"Promoter is justifying son in law’s salary (marketing head) by saying his compensation is basis his last salary. But do these guys need such an expensive resource?

Prevest topline 50 cr, marketing head salary ~1.2 cr
Also 2% commission on incremental sales in domestic market. Commission to newly-appointed marketing head inspite of such high salary?

It looks like the family is having a good time at the expense of shareholders."

All of this is not to say that the business isn’t good. There’s still great potential in it. The margins and cash flows speak volumes and growth also has been decent.

But if I can’t trust a management, then I can’t get into a long term partnership with them which is required for a compounder.
8 Likes