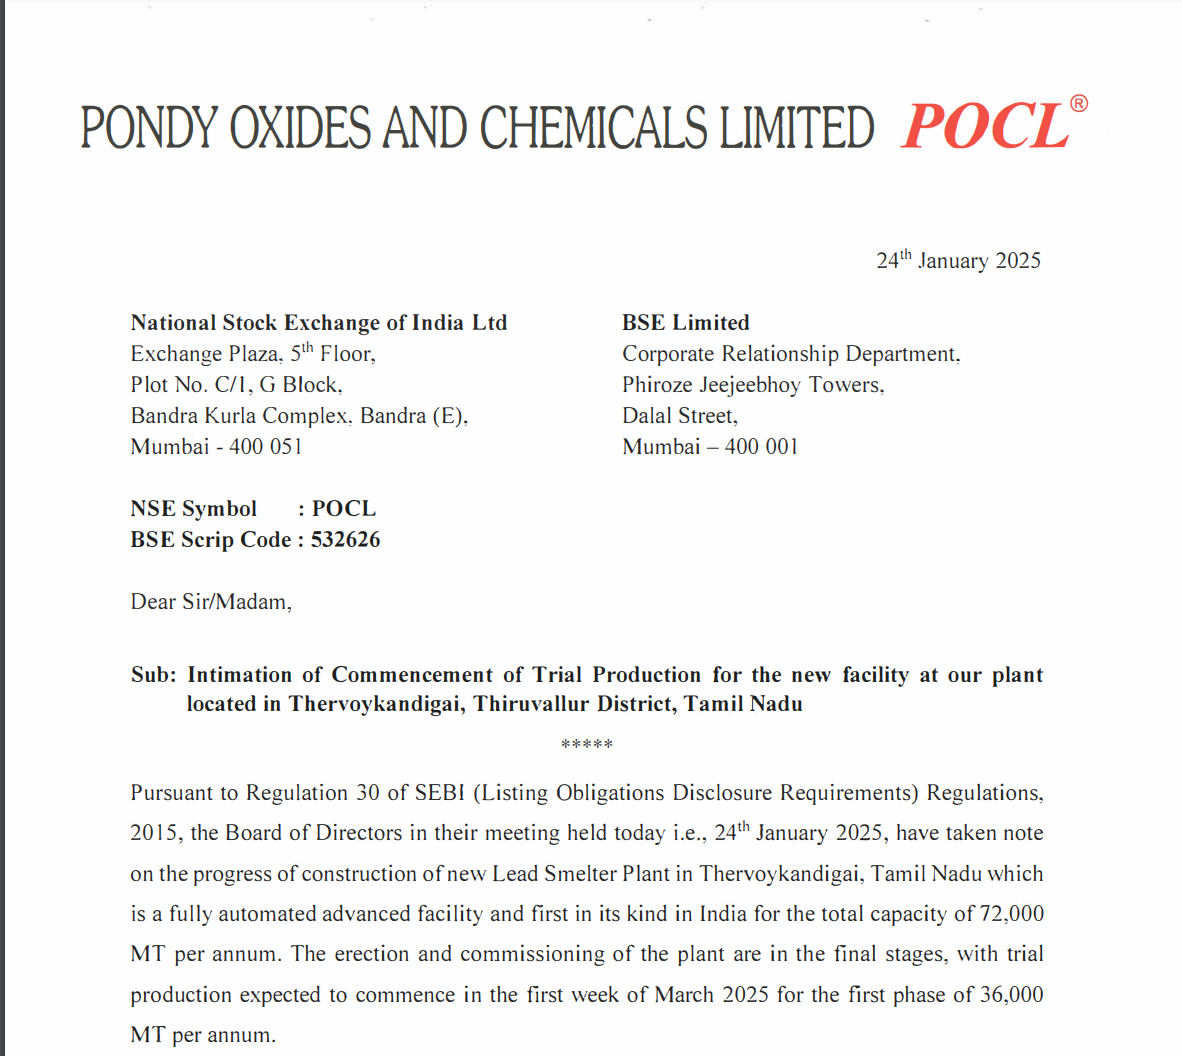
The Board reviewed progress on the new 72,000 MT/year automated Lead Smelter Plant in Thervoykandigai, Tamil Nadu.
Erection is nearly complete, with trial production for the first 36,000 MT/year phase set to begin in early March 2025.
The Board reviewed progress on the new 72,000 MT/year automated Lead Smelter Plant in Thervoykandigai, Tamil Nadu.
Erection is nearly complete, with trial production for the first 36,000 MT/year phase set to begin in early March 2025.
Outstanding Q1 results delivered by this company. The qtrly revenues have crossed Rs 600 Cr and NP has crossed Rs 20 Cr for the first time in company history. This has been possible as the Phase 1 of Lead capex has commenced commercial production and work is in progress for Phase 2 of capex . This phase 2 of capex will be over in second half of current FY.
The press release is attached .
Pondy Oxide.pdf (987.4 KB)
Q1FY26 concall was good for Pondy Oxides
A general query - there’s a separate POCL Enterprises. Any view on that business?
Pondy declared strong Q2 numbers - good revenue growth and margin expansion too.
POCL concall bullish

Any particular reason that the stock is correcting so much in the last one month, fallen by nearly 16%? Fundamentally I am not able to find anything wrong, except for the fact that the valuation is a bit stretched.
have a look please, may be helpful to understand
I think the issue is drop in MArgin - Q2 concall management said that they will maintain Q2 margins - and in Q3 there is a 1% dip. I dont see any other reason.
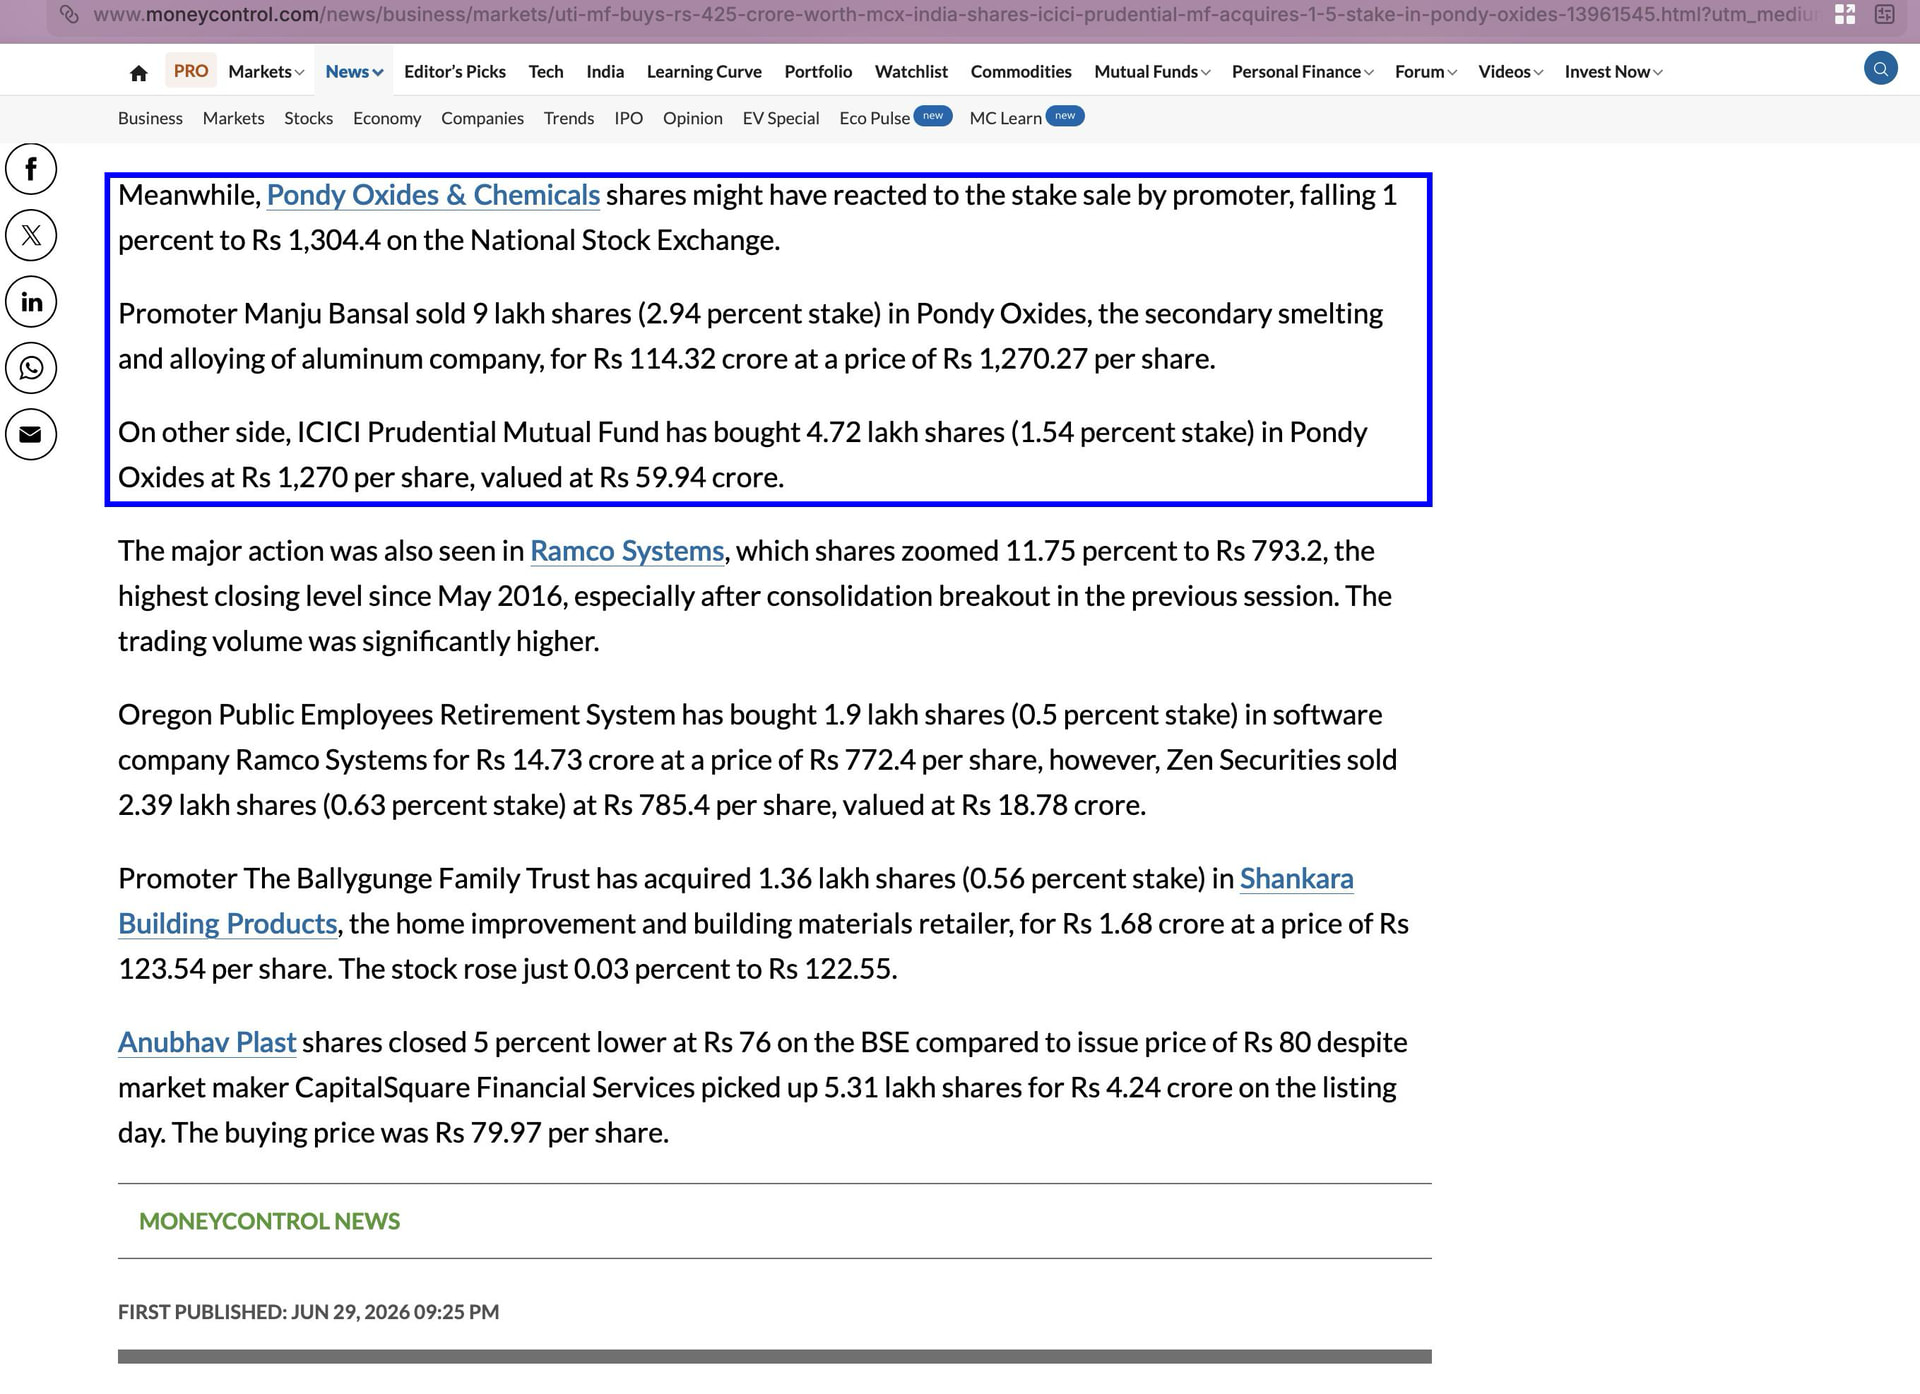
Today’s bulk deal involved promoter selling their 2.94% stake in the company and ICICI Prudential Mutual Fund buying 1.54% stake at the price of 1270 per share. (reference)
Delhi EV Policy 2026 rolls out allocation of over Rs 1500 crore for scrappage incentives. Scrapping an old ICE vehicle to buy an EV would allow the buyer to receive following amounts in different categories.
4 wheelers: Rs 1,00,000
2 wheelers: Rs 10,000
3 wheelers: Rs 25,000
N-1 Commercial trucks: Rs 50,000
Besides, the policy also incentivizes direct purchase of EVs with a good amount of subsidies:
Electric 2 wheelers: Up to Rs 30,000
Electric 3 wheelers: Up to Rs 50,000
N-1 Electric trucks (under 3.5 tonnes): Up to Rs 1,00,000
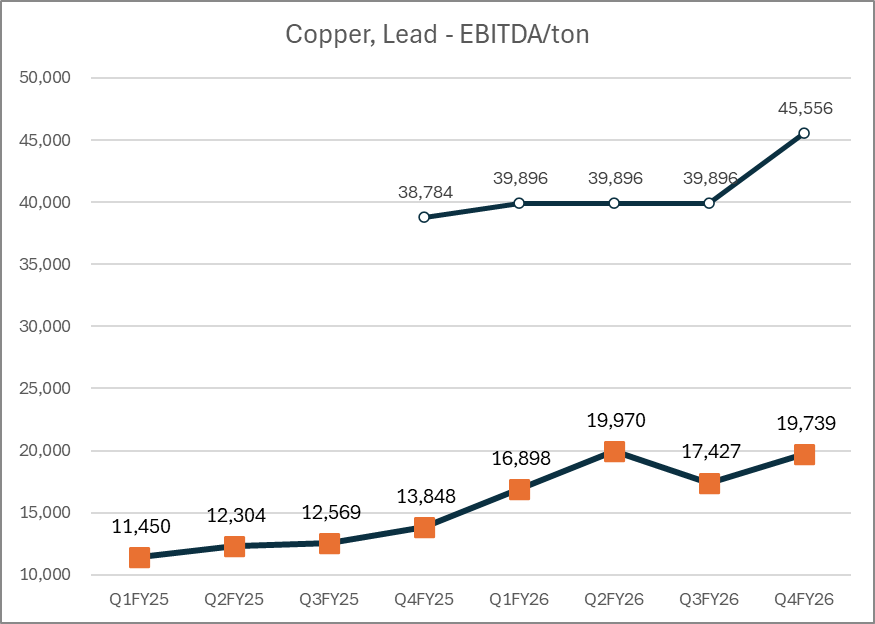
This is a conversion business operating on EBITDA/ton basis.
Looking at EBIDTA amargin as % of revenue can be misleading as it is a function of commodity price realisations.
Here is how the EBITDA/ton trend looks like for Copper and Lead respectively on a quarterly basis: