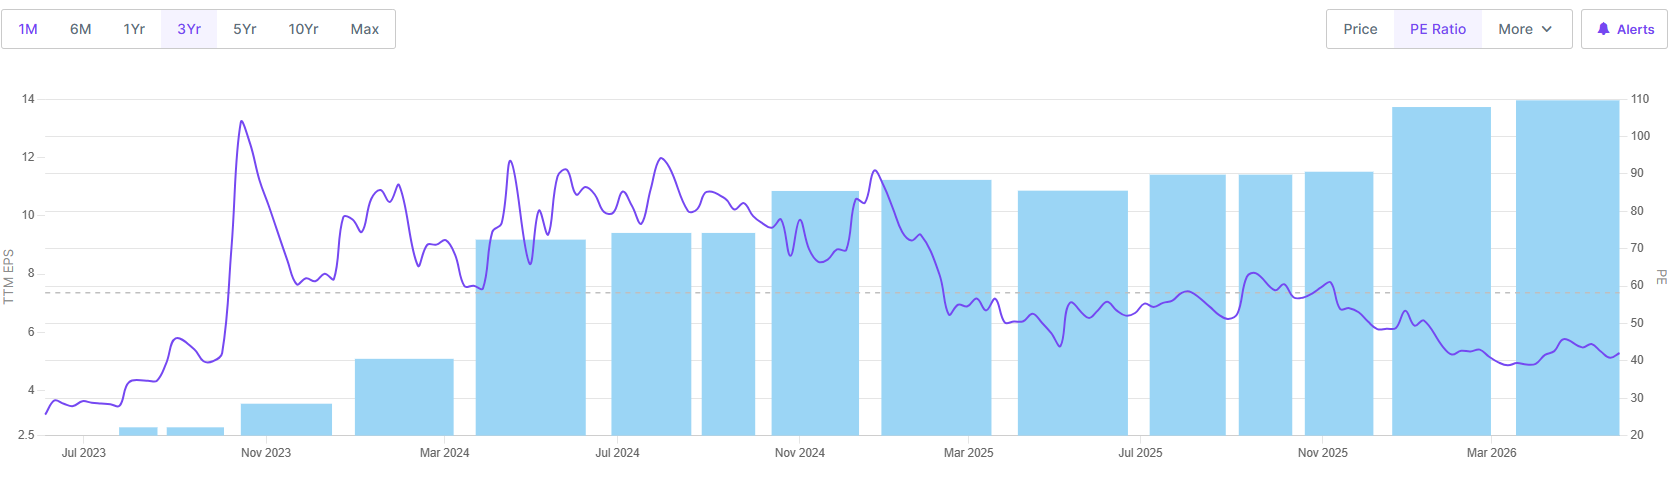
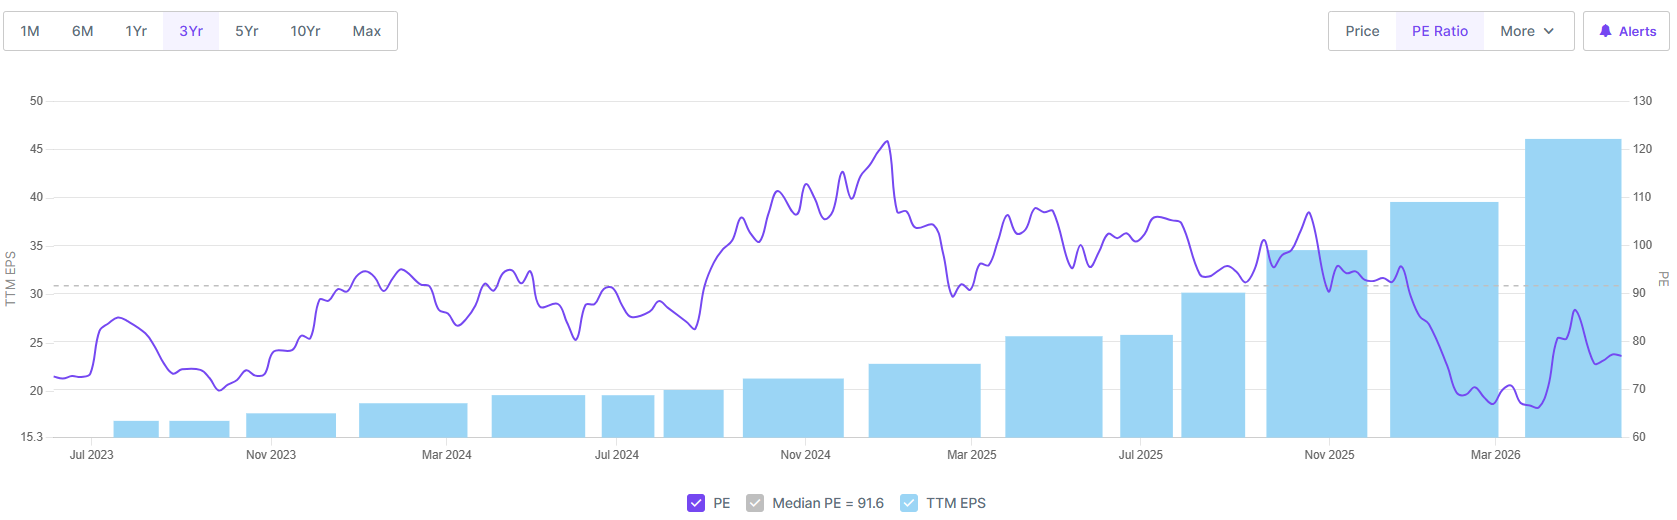
First con call scheduled by Piccadily. Extremely positive step. The stock is due for a re-rating now or Radico / USL are due for a de-rating.. there is no other way to explain the story in next 12 months
For ref - Piccadily and Radico are neck to neck in their overall luxury sale portfolio (inching towards Rs 500 Cr revenue in FY27)
Expect analyst coverage and IC reports coming out soon, followed by FII stake to a certain degree
No.Non renewal of peer review is clearly mentioned as the reason for resignation. It means that the erstwhile auditors peer review certificate has not been renewed making them ineligible to continue .Unless an audit farm has it, they can’t legally operate as an auditor and actually SEBI also mandates that statutory auditors must have peer review certificate when auditing listed companies.So that resignation is actually a forced resignation because of professional non-compliance of the auditors themselves.Nothing much to do with Piccadily .
Greenfield Chattisgarh plant monetisation starts from May 2026 itself. Barrels are in various different phases of maturation, incremental revenue growth will be seen instead of all at once. Full capacity utilisation will be seen in next 6 months.
CSD canteen stores contribute to roughly 30% of revenue, export market roughly 25% and rest 45% is domestic. Focus is on to increase export revenue to 50%
Specific product wise revenue breakdown and volume growth not given.
Change in audit firm because of re-alignment of partners at their side. Company chose to stick with specific partner (Mr Mangwa) who understands business well instead of firm.
Company eyes 60% growth in alco-bev business in FY27 (mainly through IMFL). Previously there were supply issues which now has been ironed out.
Company eyes 3-4x revenue and value creation from current levels in next 3 years.
Exploring inorganic expansion- both on domestic and international side.
Scotland facility land acquired. Construction will be completed in coming couple years.
New products are in pipeline- my guess is on gin.
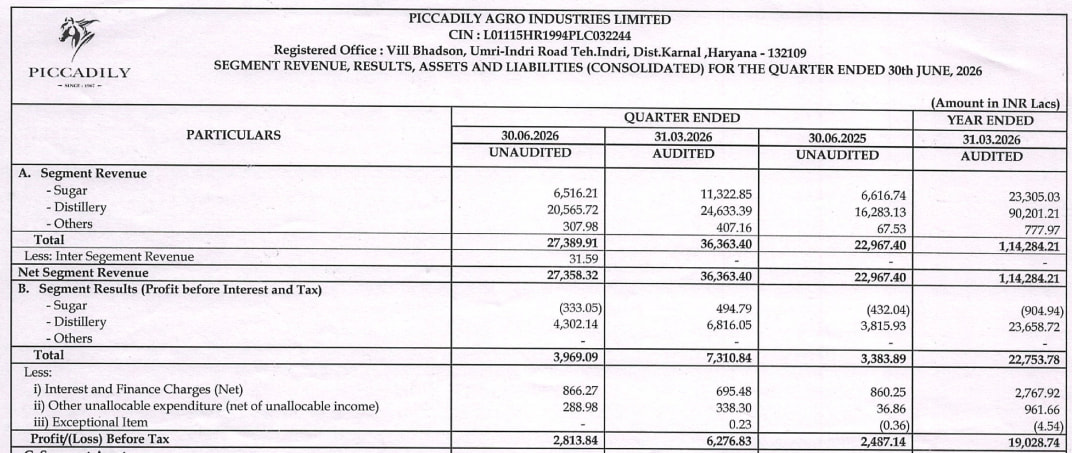
Drop in EBITDA in previous quarter is because of sugar business, plan to demerge it already filed.
Majority of capex already done - (purchase of barrels). Capex for rest of year would be under 25 crores
Multiple questions from Hiren Ved’s Alchemy was nice to hear, Hiren himself was on call. Finally we can expect some institutional stake. All points are from top of my head, ignore mistakes.
Disclaimer- invested and biased, major chunk of portfolio.
Some of the points that I found interesting from the concall :
Expect 60-70% value growth for FY 27 as well as for next 3 yrs !!
Want to be an international brand . One of the top 5 brands in the world.
IMFL ebitda margins currently are 50-55%.
Most of the Capex already completed. The resulting increased output will flow into revenue in FY 27.
The demerger proposed should make Piccadilly Agro a pure play alcobev company with a large bias towards super premium brands . If the revenue growth projected plays out this can be an interesting play.
Disclosure: Invested recently with an initial allocation.
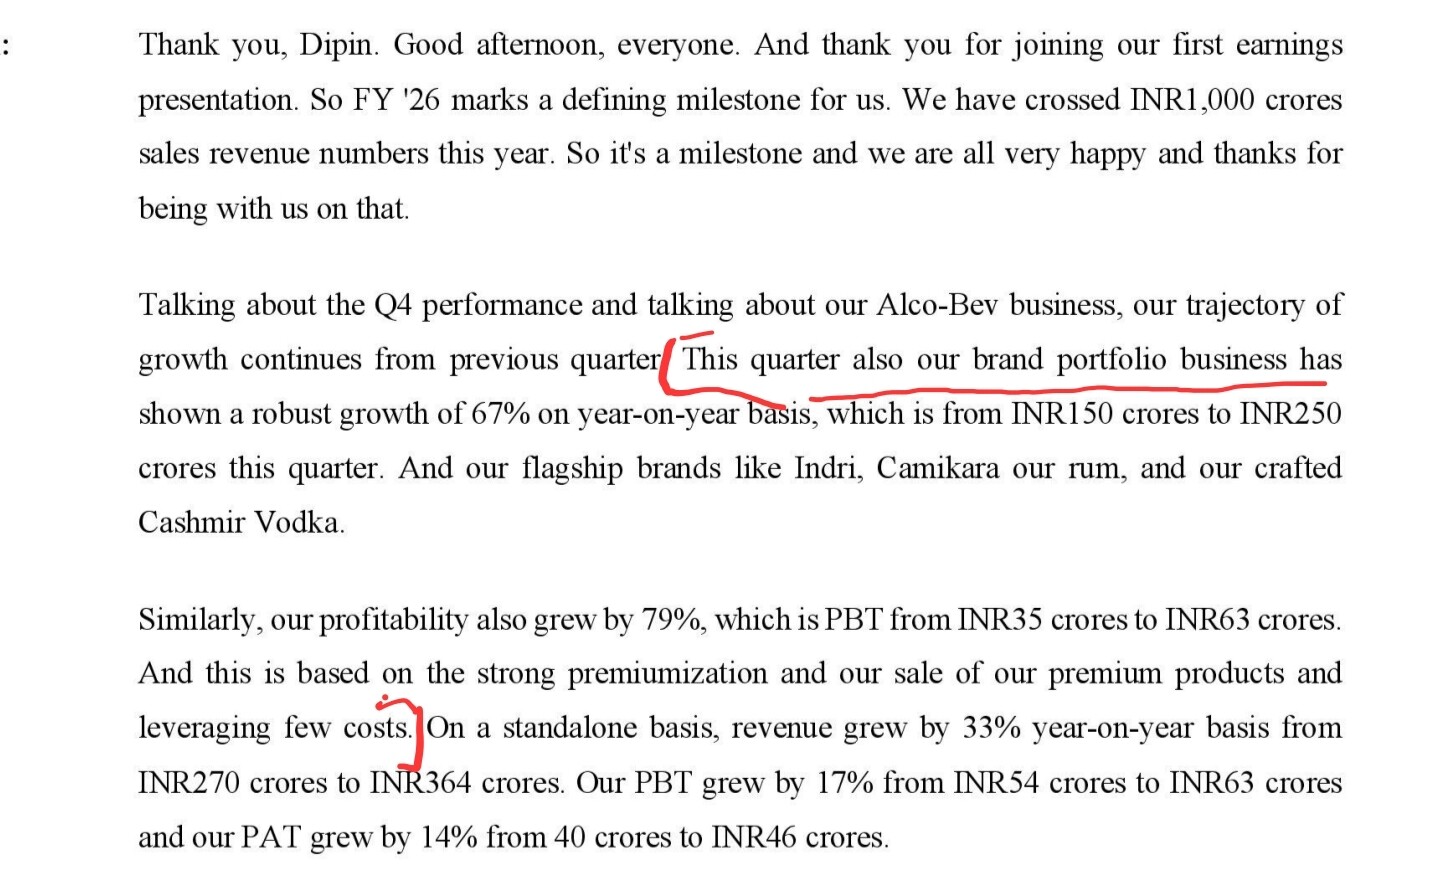
Similarly, our profitability also grew by 79%, which is PBT from INR35 crores to INR63 crores. And this is based on the strong premiumization and our sale of our premium products and leveraging few costs. On a standalone basis, revenue grew by 33% year-on-year basis from INR270 crores to INR364 crores. Our PBT grew by 17% from INR54 crores to INR63 crores and our PAT grew by 14% from 40 crores to INR46 crores.
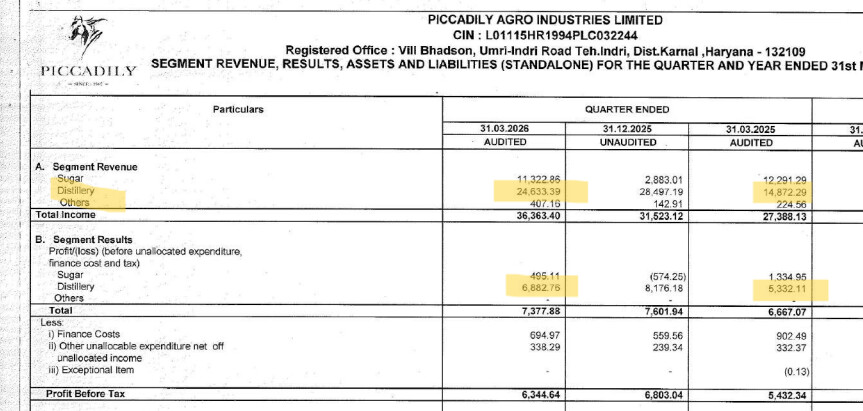
Can you pls tell me, Q4 Fy 25, Distillery EBIT was 52.75 cr, then how come they are stating it was 35cr??
They have quoted revenue and PBT from this (incl consol) financial statement only. Since this being the first concall, I am giving the management the benefit of the doubt and hoping it is not a deliberate attempt to downplay the moderation in margins in the alcobev segment.
They had stopped selling of malt produced in house last year to fill up their own barrels stock for maturation .That had reduced revenue and increased margins since malt is commodity .Anytime they start selling again margins had to reduce and revenue would increase .Either they have started selling malt again or the other possibility is the commisioning and ramp up costs of the expanded facilities . Ramping up also means producing large volumes of ethanol/ENA initially which they would need to sell to OMC or other alcobev producers etc. at much lower margin. Plus, new factories means trial of new machinery ,new extra employees, fine tuning of factory processes etc. which adds to Cost of material consumed and other costs ..
The company is building up for new leg of growth ,They sell products that takes years to mature ..so its not really useful to expect a steady state of operations now.
Disc. Holding . Added recently to a separate portfolio .
From financial statement it is quite evident that power and fuel cost and Other Expenses have increased by around 25 cr YoY compared to minimal increase in employee cost. I am bothered why they have given wrong figure for comparing this quarter result??
I think the answer is as explained in another post to your question.Those concall numbers are only for premium section ..but only for the PBT part . For this quarter the PBT on your screenshot is near 69crores and Q4 25 is 53 crores .And they have mentioned 63crores (not 69) and 35 crores(not 53) . So they are not quoting the PBT numbers for entire distillery segment in the concall. Considering they stopped selling malt sometime inbetween , I think it makes sense but you are right..they should be more specific .Mixing up revenue and PBT for different set of items sold is confusing indeed.
Barrels: ~85,000 filled, plan to reach ~100,000 in FY’27.
Notably, the company does not sell malt/bulk barrels: “We don’t do a malt sale… We don’t do any bulk malt sale. It will all be for bottling for our flagship premium brands.”
When I last had a look at piccadily around 1.5 years ago, I was looking at RPT and saw 10 crore as a rent to promoter’s manali hotel. The cost of a room in that hotel was 3k per night then. The company also paid 15 Cr for a parcel of land to soon and sure holding ( a promotor entity ). Other RPTs were also suspicious.
Since they have started concall and are heading in the right direction of splitting sugar and distillery business and the valuation seems to be attractive, I am reading about it again.
Can someone pls confirm these practices have stopped. I am not an expert in balance sheets so can someone please look out for the red flags in balance sheet ( i can see current borrowings ballooning and receivables increasing ).
Indri’s so popular so why receivables increasing? Shouldnt they be selling in cash?? Sorry, a bit new in this sector so trying to understand how it works.
Management repeatedly guided FY’27 as “exceptional” with 60%–70% growth (explicitly value growth).
In next 3 to 4 years, we expect revenue to grow by 3x to 4x of the current revenue.
EBITDA margin guidance of flat to 50 bps improvement
Company delivered Rs138crs in FY26. Assuming 70% PAT growth FY27E PAT likely to be Rs 235crs. The stock at current market cap of Rs5659crs trade at a P/E multiple of 24x which is super cheap for an alcohol stock.
The guidance has been very strong and if Q1 demonstrates the execution, the stock should do well from here. Institutions have still not shown much interest, positive Q1 results can be a trigger for their entry. Overall the sector (FMCG/Beverages) has been on the sidelines for quite some time which is a good news for investors to build a position in the stock. Demerger by the year end will eventually take the monkey off the back and the journey from there should be interesting.