
All the results are out for pf stocks. Everything has been great, some have been outstanding. Overall, no big surprises on the upside or downside. However, a lot has changed on the outlook for all the stocks I own. So I felt I will put down my thoughts on what’s new only.
MTAR - Guidance was upgraded to 80% revenue growth coupled with EBITDA margin of 24%. Earlier guidance was I think 50%. This is of course a night and day change in earnings power. Sometimes a stock at 300 P/E can be a contra value bet. In fact this is what I was trying to convey in my previous post, that while I was pessimistic on overall market valuations, I myself had loaded up on very high P/E stocks - precisely because P/E is not useful for valuation. Bloom has upped guidance and going by a recent report Goldman Sachs report, 25-50% of BTM power will be provided by fuel cells (though relatively expensive, its nothing compared to overall costs). So my guess is Bloom will have to continue doubling its capacity every year from here almost to get to something like 20 GW by 2030. The nuclear and defence segment as well is doing quite well and in addition to this, they have also received another data center order outside of Bloom. As they say, when it rains, it pours. I think FY27 PAT could be 250-270 Cr here and in all likelihood, 500 Cr by close of FY28. I know it sounds outlandish, but I feel its likely.
Sai - Market sold off despite a 109% PAT growth YoY for full year. I am not sure what market was expecting. Thankfully it did recover most of it though by close. I suspect people still havent understood how to read CDMO results. I saw the same thing happening in Neuland with market getting excited over the bumper quarterly number when it was sedate compared to its FY24 base. Anyway, the key takeaways are that tariff has no impact - its not new but reassuring to know. I had done extensive research on this - since CRO is 35% and exempt and development work is also exempt (Sai does a LOT of phase 1/2/3 supplies), among commercial innovator molecules bulk of it is to large pharma who have made deals with the govt. Only United Therapeutics and Tyvaso I felt could be impacted (if at all) so good to know tariff impact is a non-issue. Other than this, the new detail is that 1100-1300 Cr is planned capex next year after 650 Cr spent this year (220 KL coming in H2 and 220 KL next year). Since Sai has never invested without visibility, its clear they will continue on their growth path over next 2-3 years as well. With USD to INR nearing 96 and Sai deriving 100% of revenues nearly from exports, this investment gives access to a naturally hedged and growing future cashflows in USD. Some info from the innovators. In this Qulipta/Ubrelvy are end molecules for the intermediate Sai supplies and they are growing at healthy rates of ~50% (International doubling YoY). Rinvoq is the one that Anthem/Divis supplies (ignore the highlight on that)
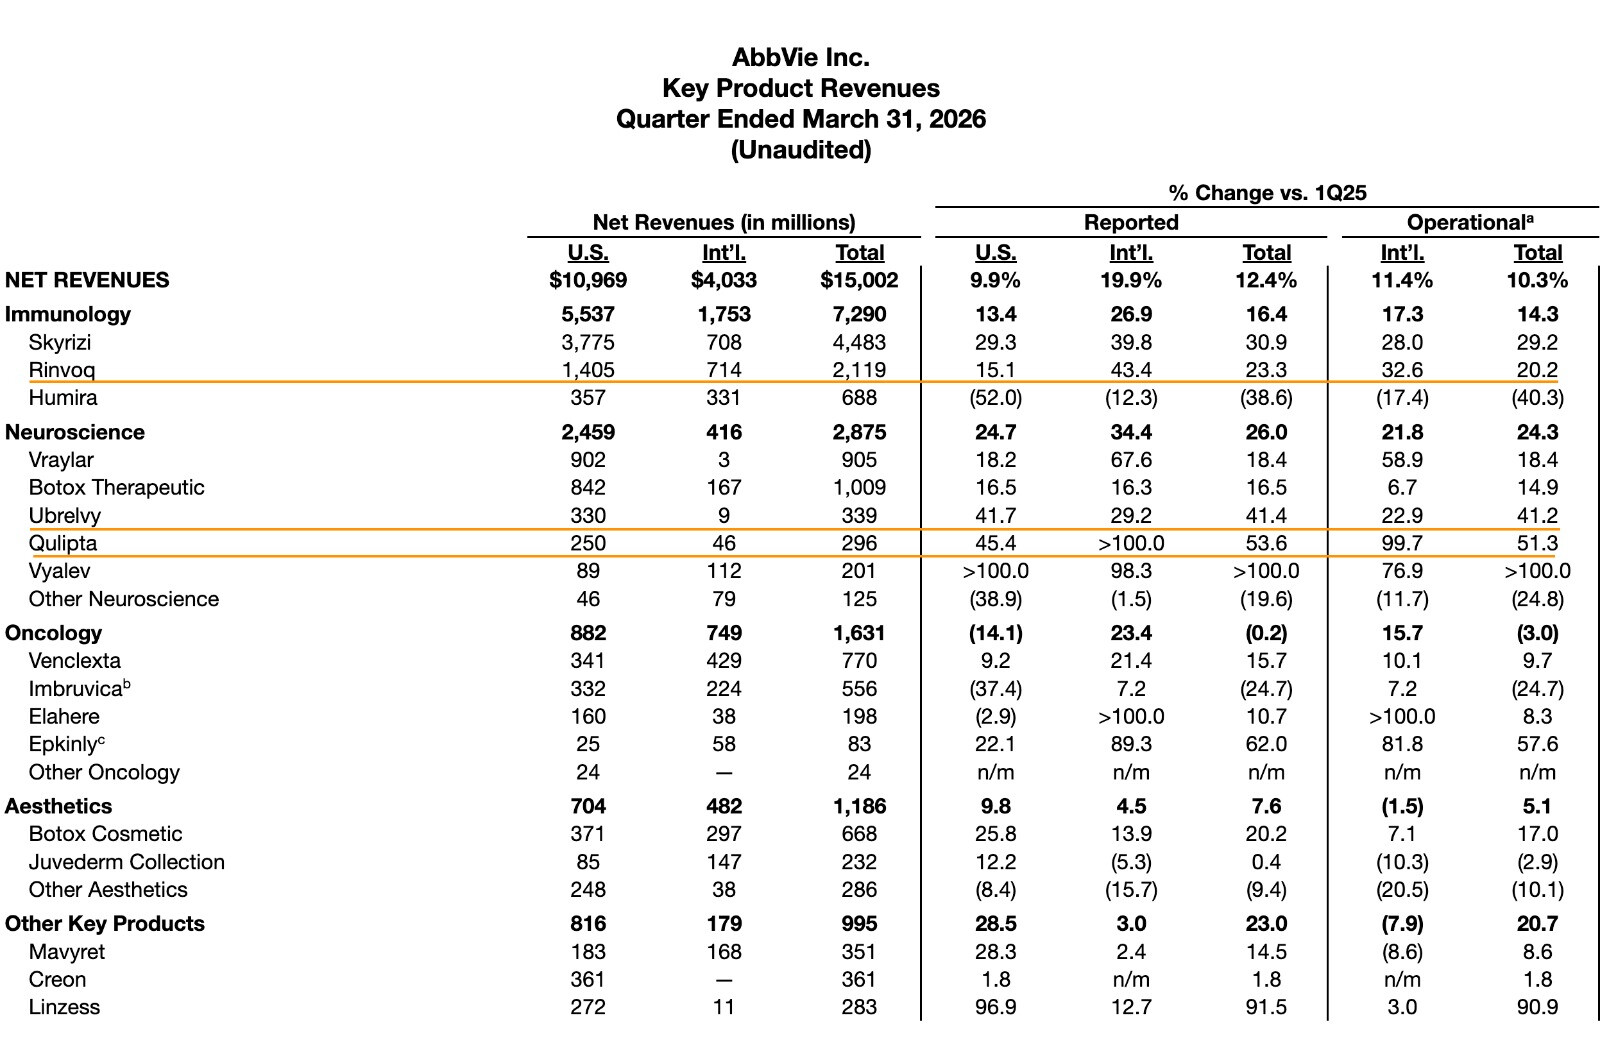
Quviviq is growing 74% and Vanda has launched Tradipitant as Nereus. The other nice detail comparing Q3 and Q4 PPTs is that Active commercial molecules has gone up from 30 to 34 (+4) and Phase-3/Pre-reg has gone up from 6 to 11 (+5).
TD Power - Execution is on track with new capex coming online helping numbers as expected. They are well on track for 2400+ Cr (conservative) FY27 and 3200+ Cr FY28 (very conservative imo). Gas engines and gas turbines to DC is what will continue to drive the numbers and Innio has filed papers for IPO and is very bullish on its forecasts. TDPS management mentions they have a long-term commitment from Innio that extends to 2030! Just like MTAR will grow with bloom, I think TDPS will grow with Innio (and CAT’s subsidiary Solar turbines) since Innio is tripling capacity as per their IPO papers

I think between SOFC and gas engines/turbines, bulk of the BTM buildout will be captured - since it may not require grid backup or BESS. Just a 20% redundancy should guarantee a N+1 which will be cost-effective as well. Irrespective, both Mtar and TD are set till 2030.
Aeroflex - I feel this is the dark horse among the pack because there is a lot that can go right here if they can leverage capabilities quickly enough - and so far, they have shown that they can, since the liquid cooling skids wasn’t even part of business same time last year and is now a 5% contributor for FY26 and will be 20% in FY27 and most likely 40-50% in FY28. Sticking to the theme of only talking about what’s new, one of the most important things is this
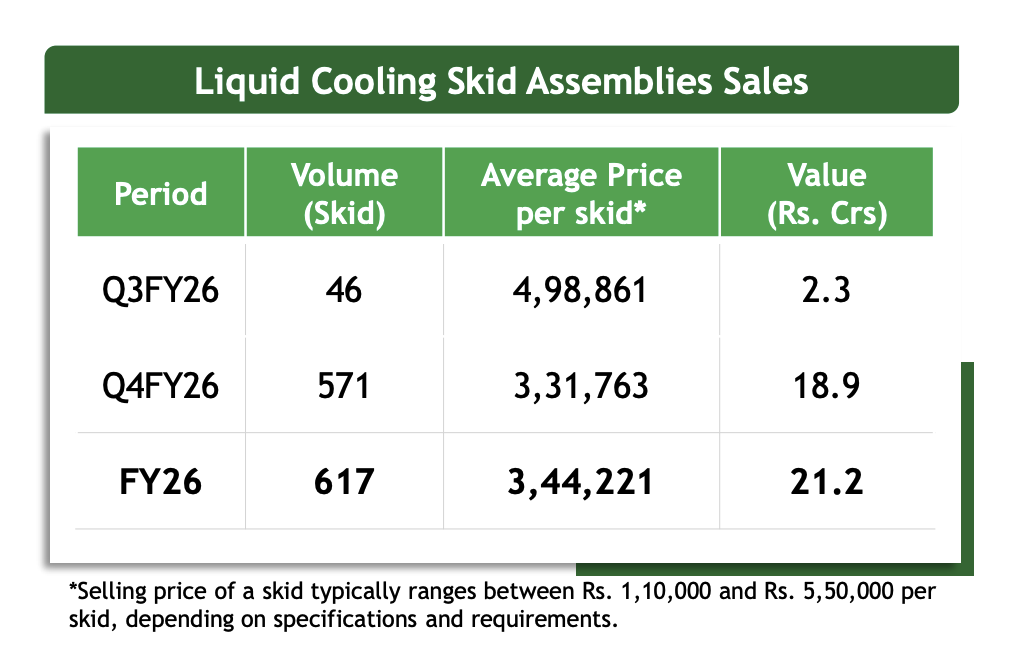
The management has guided for a 3.25 lakh as avg realisation per skid. This is a considerable jump from 15000 skids with peak revenue of 350 Cr, yielding 2.33 lakhs per skid. This I feel is still very conservative because Aeroflex can contribute a lot more value per skid. I suspect they are even capturing 10% of what’s possible. Not just in the skids, but in the overall liquid cooling - especially if they can break into the rack level components which will be much higher in value.
There are initial signs of that. I am not sure if I put out my thesis on Hyd-Air here in the previous posts. If you haven’t yet, do have a look at their products. There are a lot of high value stuff in these, like the QDC and other fittings and as per specs they are interchangeable with some of the best in the business.
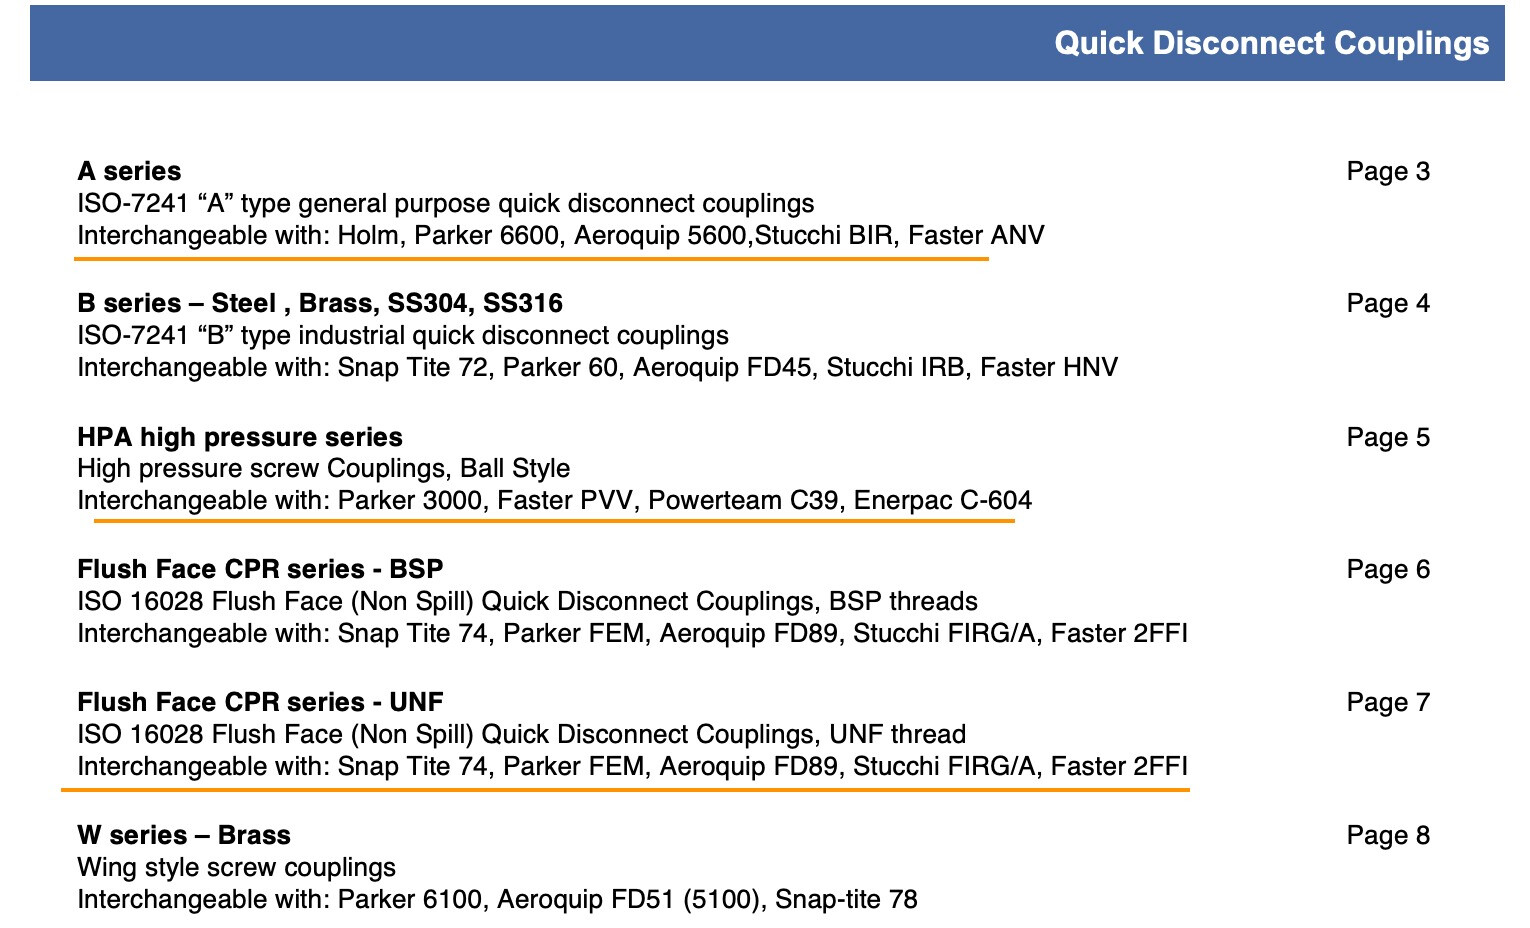
This was one of the things that got me exciting initially on Aeroflex in my initial research because this company is also setup at Chakan close to Vertiv’s own manufacturing plant. In recent call, there were some things on Hyd-Air I found interesting validating this thesis
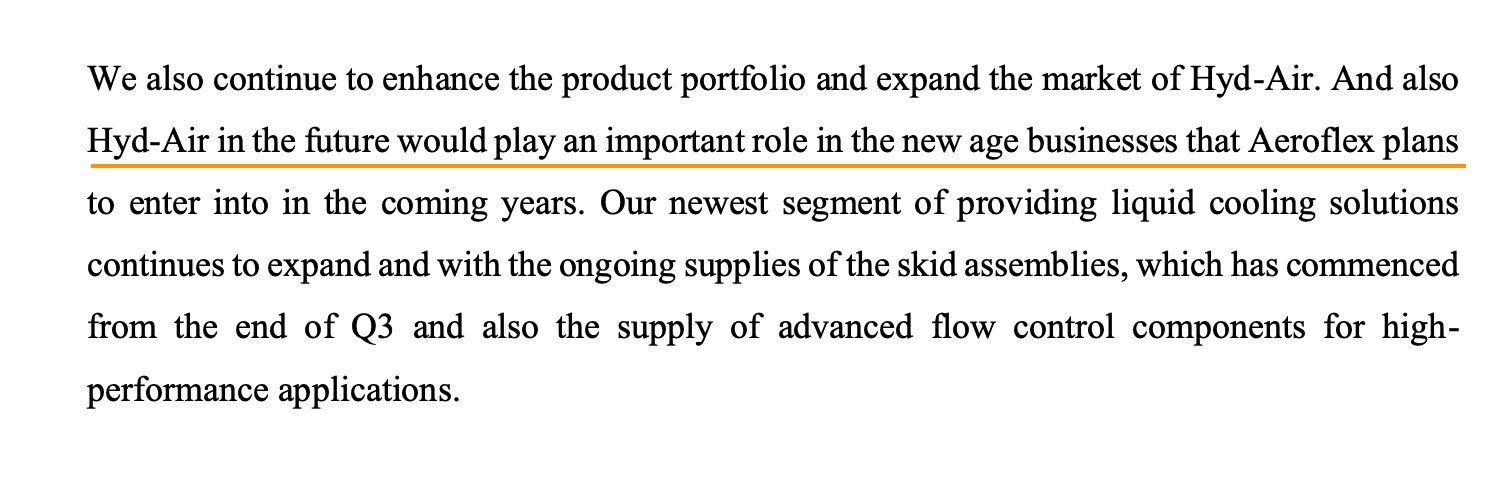
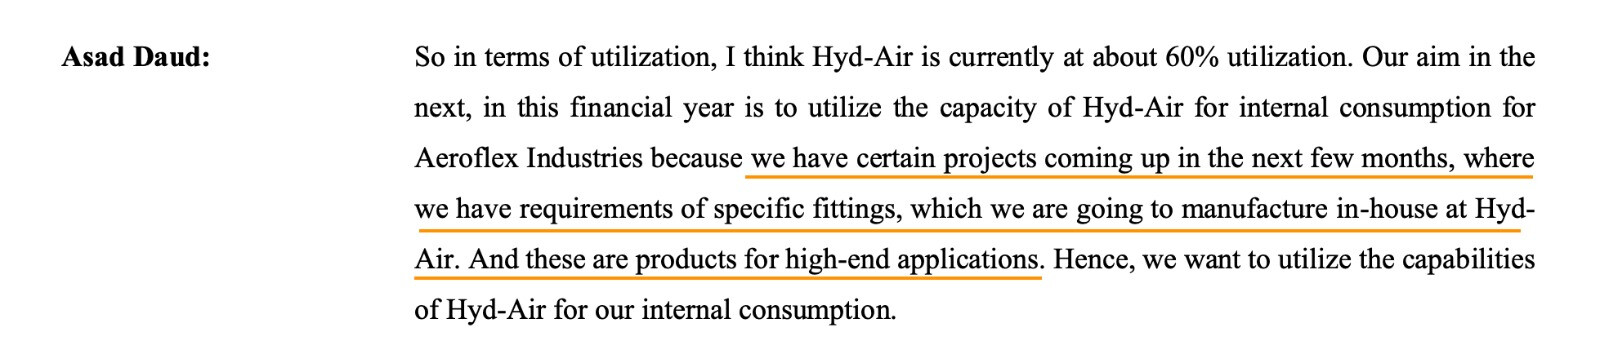
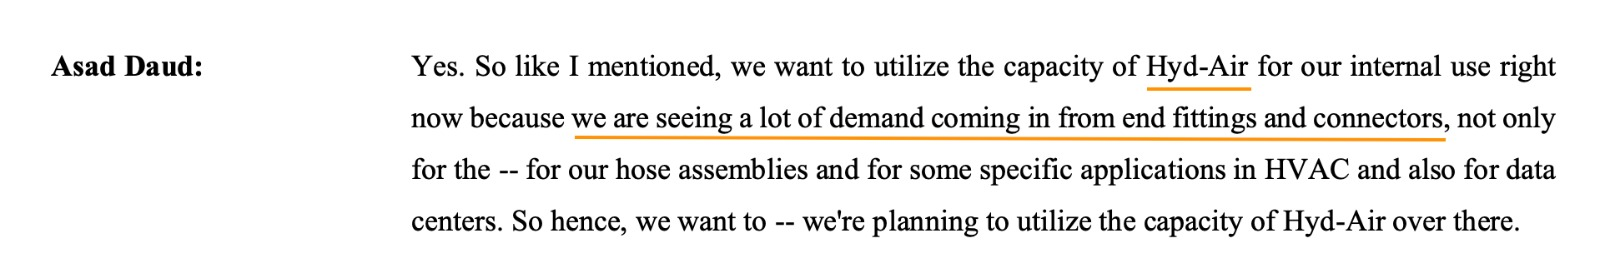
My guess is Hyd-Air will continue to grow at a great rate and contribute to Aeroflex internal consumption for value add in skids and also in the last-mile rack level components. In terms of exit run rate, looks like post 15000 skid expansion, Mar 2026, they can exit at 60% util (750 skids) which means a 300 Cr contribution from LC in FY28 (750x12x3.25 lakhs) even if we assume no growth in that run-rate. From 0 last year to 600 odd skids per quarter now to 750 per month is breakneck scaleup for what is essentially a completely new line of business. I think 15000 skids is perhaps ~200-250 MW of capacity based on some assumptions. If India has to add 5-10 GW of DC capacity and Vertiv has 70-75% of this market share (as per Aeroflex Arihant call), and Vertiv has exclusivity with Aeroflex, you can imagine how much this capacity has to go up by in the next 4-5 years. It has to pretty much double every year, just like Mtar if things play out. Its still very early days though. On top of this, they can increase the % of value add by adding new products as well which is why I feel this can be the dark horse as there are several things that can keep surprising on the upside.
Aimtron - Among other stocks I have studied recently, liked Aimtron. In short, I like how they have scaled business from doing PCB design and assembly (65%) to doing complex box builds (35%) for global OEMs. I feel the AI box builds is a fairly large market size and I think Aimtron can capitalise on it. They have a decent order book (600 Cr vs FY26 rev of 300 Cr). Among EMS players, their growth has been very good and valuation relatively cheap. The main thing that excited me was their foray into optical transceivers.
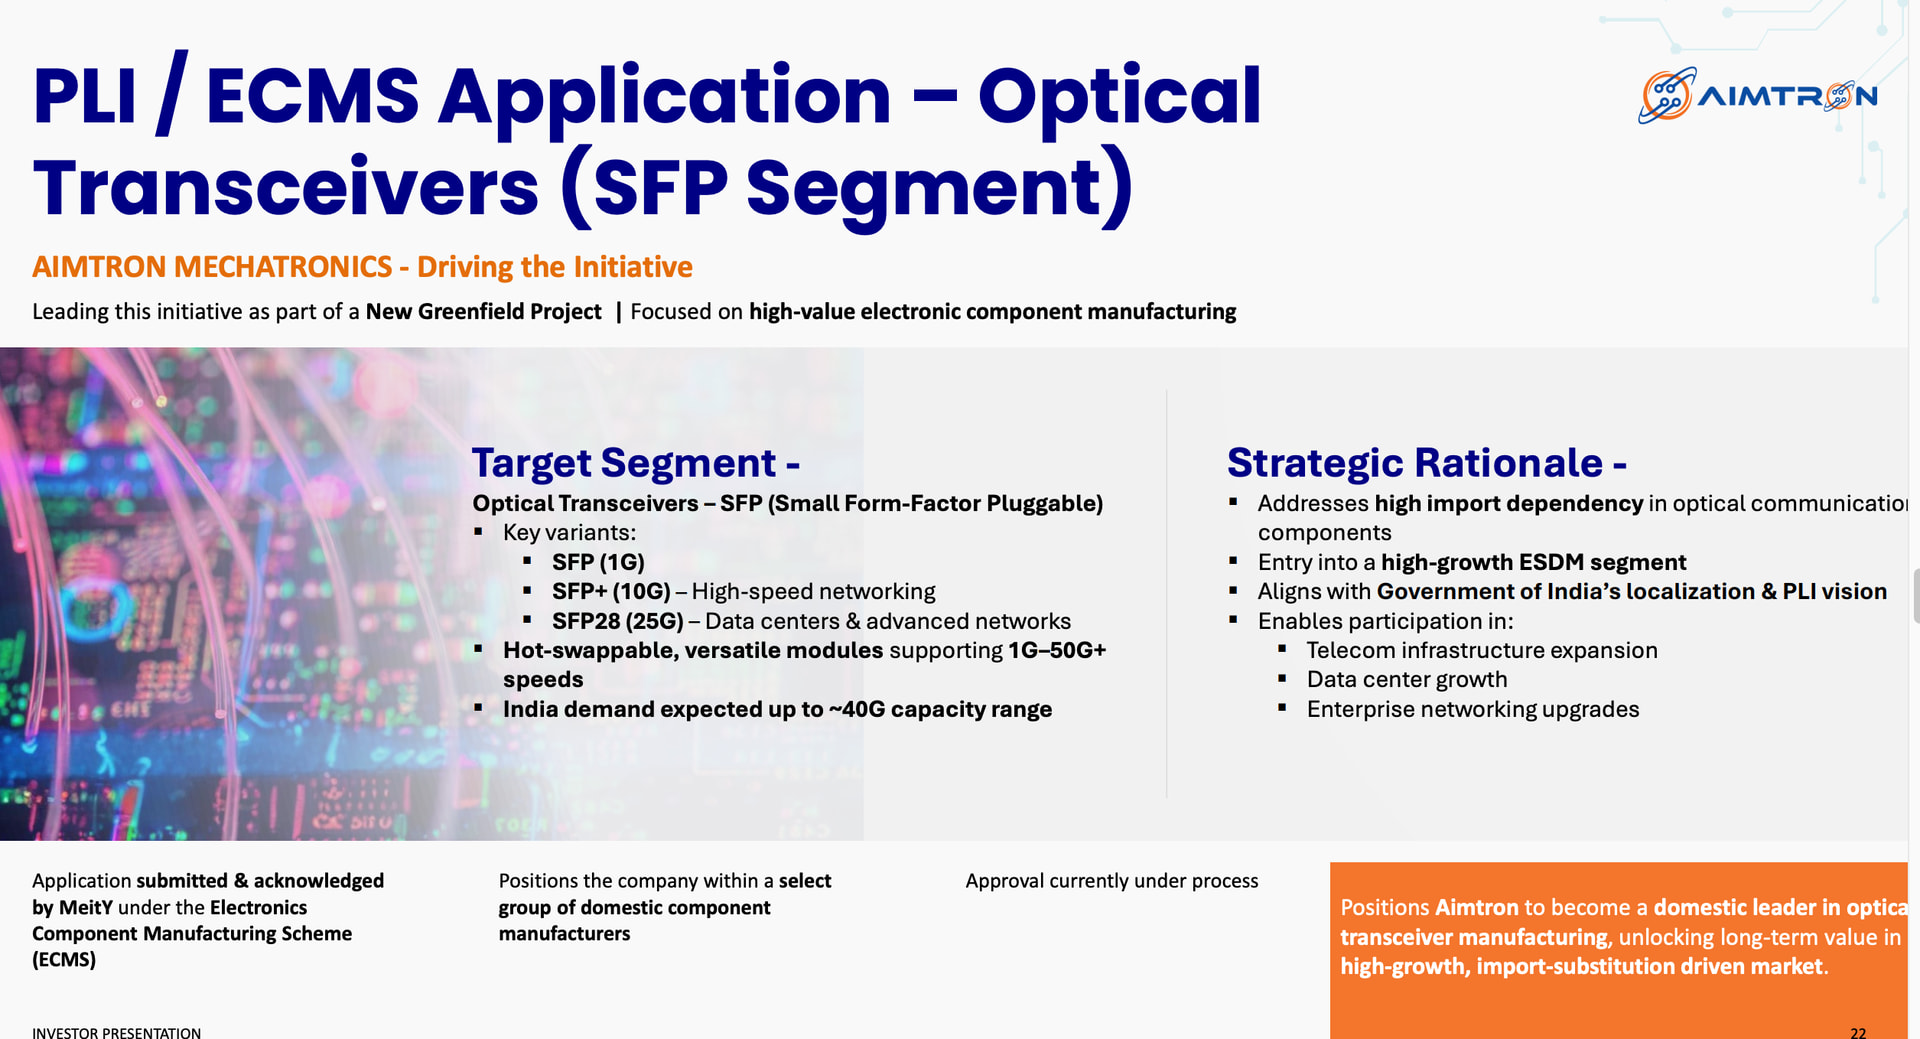
Please note that the PLI is not yet approved, so its not worth getting excited about yet. If it does get underway, its a good import substitution play of a high value component. SFP Optical transceivers are used in several places in telecom and DCs and Aimtron seems to be targeting 1G to 25G speeds. At the top end, it can be used in network level use in DCs. At speeds as high as 800G, it is used between GPUs in Vera Rubin but that is extremely specialised and companies that have that capability can be counted in one hand. What Aimtron is attempting to is the most basic stuff - but even that requires capabilities beyond what they possess. They seem to have got an international player who might transfer technology.
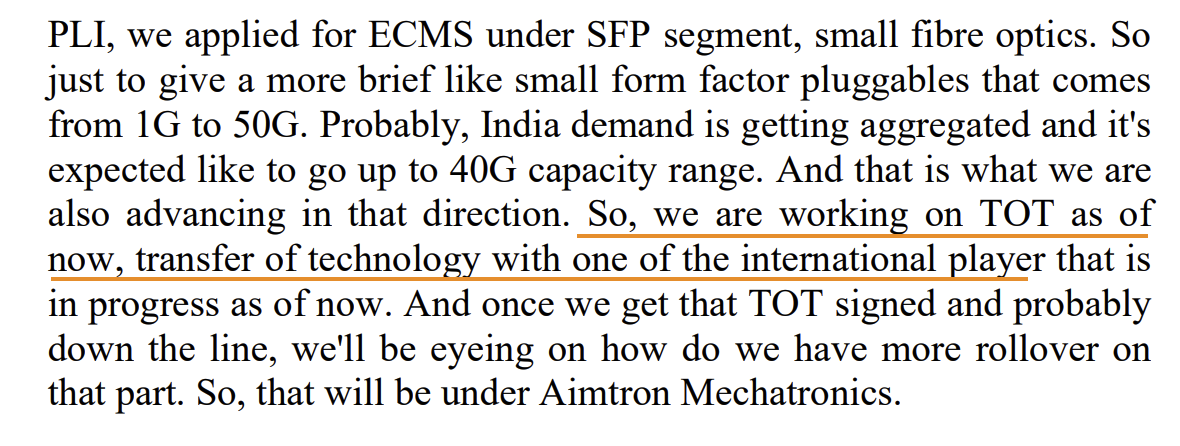
If this optionality plays out, Aimtron can do very well but I think better to treat it as an optionality. I have a tiny position here to track and see how it goes and might scale up if they get PLI and ToT approved and have a clear path to how they will finance it considering they dont have the balance sheet or cash flow for it.
Disc: Invested in all names mentioned and very likely biased. I am very much a novice and write to gather my thoughts and this is not investment advice