Any update if they will receive any PLI subsidy as that can improve margins significantly. We shoudl ask questions on this if they hold investor conference. Stock has taken a hammering however quarter to quarte peformance is really good and deal pipeline very impressive too. HOLDING with patience
I had written mail to them to know about status of pli subsidy and suggest that they hold investor conference after quarterly results like reputed companies do , no response
3 Likes
Typically contract manufacturers globally don’t trade above 0.5 P/S . Wistron trades at 0.38.
Globally what happens has little to do with it.Dixon sales at 2.5x ,kayness at 10x . Oil is free in Venezuela or cheaper than water in middle east does not mean it would be free in India .Similarly wistron listed in Taipei and operating mostly in taipei cant get same multiples as dixon in India. Uniqueness and capital market strength has a lot of influence which can’t be ignored offhand .
1 Like
One more thing: It is all about increasing EPS.
Still assessing this company. At this valuation, it seems like Good buy for 4-5 yrs then 300B electronic export target can be met.
Contra views are welcomed.
Very average quarter , AGM was equally disappointing when management just planted a few yes men shareholders who asked questions. CEO was not even present in AGM shows the professionalism of promoters. Have been holding since 3 years and will be trimming stake.
1 Like
I had done initial due diligence on this company and checked their AR…since they have a holding company structure, very little worthwhile information is available in AR to evaluate the EMS side of business and make a view on the future of the company. Management keeps giving interviews and paints rosy future, thought nothing much has materalized as yet…latest deal on manufacturing mobile phone screens (in partnership with corning) also will take time to show impact.
Considering all these factors, i exited the company in a matter of weeks.
1 Like
This is summary of different headlines on this company over timeline. If they are doing everything, I doubt what they are really doing.
Jan 2018
Aug 2021
Jan 2022
Jan 2024
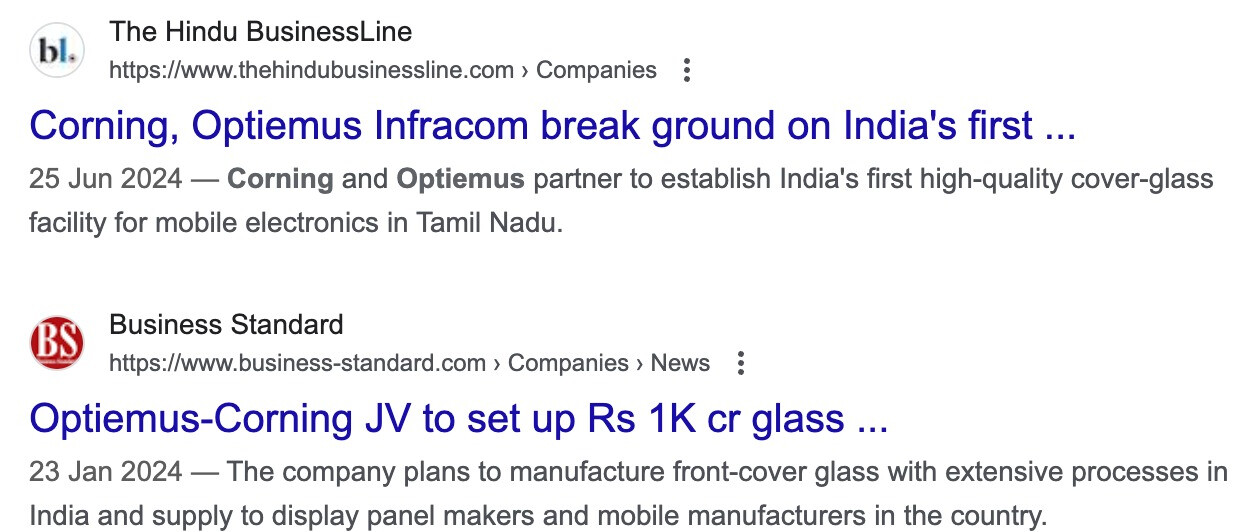
Jul 2024
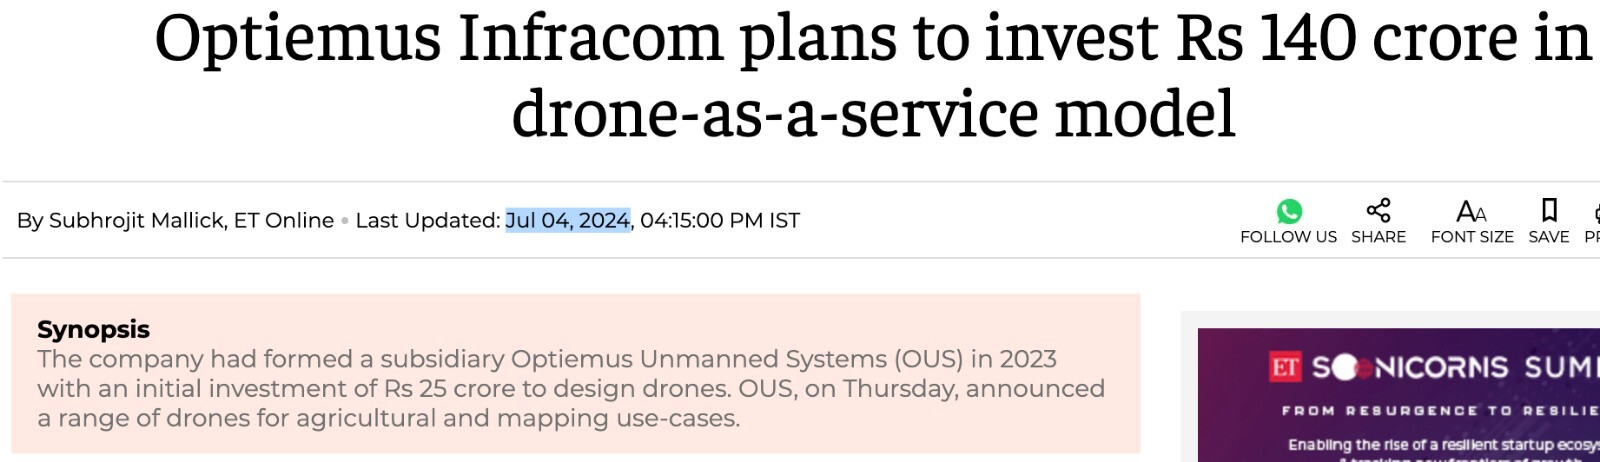
I left out the xiomi, noise news as well…
3 Likes
147 cr , 2% of optiemus valuation shares allotted roughly to DII’s, also 287 cr warrants issued to promoters & non-promoters.
at 14% discount to current valuation

1 Like
Optiemus Infra – Key Update
- Board Approval: ₹447 Cr corporate guarantee for Bharat Innovative Glass Technologies (BIGTech).
- Purpose: SBI credit facility.
- Date of Approval: Feb 10, 2025.
Date: January 27, 2025
TP-Link partners Optiemus Electronics to Manufacture Network and
IoT Devices in India.
Under the partnership, OEL will be manufacturing a range of key telecom and IoT products like GPON (ONT), cameras (Security and Surveillance), Home Wi-Fi routers, Enterprise Routers, Modems/ Gateways, SOHO Switches, and other network expansion devices. These products will be manufactured in OEL’s state-of-the-art manufacturing facility having a capacity to produce up to 6 million devices per year.
1 Like
Does anyone have any update regarding the Corning-Optiemus JV. Has OI started producing the glasses? They didn’t give any update regarding it even in the lastest report.
They are setting up a plant in Tamilnadu. Production will start from Q4 FY 2026.
1 Like
Optiemus joins hands with OnePlus to manufacture IoT devices from India.
Tws and Neckbands fall under IoT devices.

1 Like
Optiemus Infracom to set up 3 new wholly owned subsidiaries
 Optiemus Vision Technology – to manufacture & trade camera modules
Optiemus Display Technology – for display modules
Optiemus Micro Electronics – for mobile & IT hardware enclosures
All entities to be 100% held by the company; incorporated in India
2 Likes

Strengthening its partnership whith CMF and Nothing.
Optiemus infracom ( listed company) was doing JV with nothing and cmf brand. Optiemus+ Nothing+ CMF ( optiemus owns 65%) investment of $100 mil to produce 5 lk phones per month. Nothings accounts for 2% of revenues to india ( global brand).
4 Likes
The company has come into partnership with many renowned brands like Realme, TP-Link, OnePlus, and Corning. As per their timeline of production, many of the partnerships are already in progress and the recent inaugration in August of the RhinoTech facility also brings revenue in the business. The new JV with Corning (BIG Tech) will be a pivot point in the company’s journey.
My main concern is that since the company has already started production of many of this partnerships which are not small if we look into them, and from what I projected, the company should earn majority of their revenue from their Manufacturing business although based on the latest quarterly results, i.e., Q3 FY2026, the Revenue bifurcation shows that the company still earns 50% of its revenue from its Trading business.
My main point of concern is, if the company’s this many partnerships are already work-in-progress, why can’t we see it being reflected in the revenue of the business. My projections even on a conservative basis gives me the results that the company could’ve easily earned around ₹2,800-3,000 crores in revenue in FY2026. Although all 3 quarters combined together, states that the company only earned somewhere close to ₹1,300 crores as of now, and the revenue for FY25 was ₹1,890 crores.
I am confused if the company is actually doing the business it said it has got from this partnership or not. I was way bullish on the company before the last quarterly result, but now I have some doubts.
So if you guys have any source of new information or any management talk, that would be a great help to me.
PS: I am invested in the company.
MANAGMENT and History:
Pioneering the Mobile Ecosystem:
 Was the manufacturer for HTC, ZEN  and distributor for NOKIA and HTC
 Retail distribution chain in the south by the name Universecell.
 Due to fall of above brands , Revenue became 2.6kcr in 2015 to 182cr in 2022.
Credits to the managements :
Successfully pivoted to B2B and B2C EMS player ,assembling for the top brands.
Even after having such bitter downfall Share dilution is almost negligible . From 8.58cr outstanding shares in 2015 to 9cr share at present shows only 5% dilution . Even in latest warrants, management also participated inspiring the confidence in the business.
Management ownership is 71.40 % in the company
Industry Tailwinds:
- India is becoming EMS hub for global and indian players .
- China is shifting up the value chain leaving place for downstream manufacturing
- Rupee depreciation and labour cost making indian manufacturing advantageous
- PLI 2.0 provided by Govt ranging benefits from 5 to 9 % of incremental sales
- Development of Indian ecosystem and large domestic market is the leverage taken by govt to drive manufacturing in India for the world.
- Tariffs on china and recent FTAs of India
Current Buisness:
POS ,Desktop and Laptop , Wearables like headphones ,smartwatches and IOT devices
for the likes of BOAT , NOISE , Realme, z3 wireless for Oneplus ,Routers for TD link
Ordinary Theory LLC ,Surveillance equip for CP PLUS .Reliance Jio vendor, ASRock ,
Network equip for TEJAS , etc
Smartphone and related accessories -
AI+ phones(500cr rev alone in last quarter)
Current buisness is basic EMS, where managment is trying to rope in stronger and
stable brands Company is saying to double the revenue in FY27 ( because of AI+ smartphone
deal ) and growth of 30% for next 2 years in 28 and 29 . This is excluding 3 growth levers which
will be mention later.
Drones , Gimbal camera and Defence:
Technology Partners with taiwan companies like Kunway and Avik. Management seems sluggish with regards to the commercialising these technology.
3 BIG DRIVERS:
1st Driver - BIGTECH(OPTIEMUS , Corning JV 70:30)
Will me making cover glass (gorilla glass) . Phase 1 completed investment upto 660 (ICRA estimates) with trials ongoing.
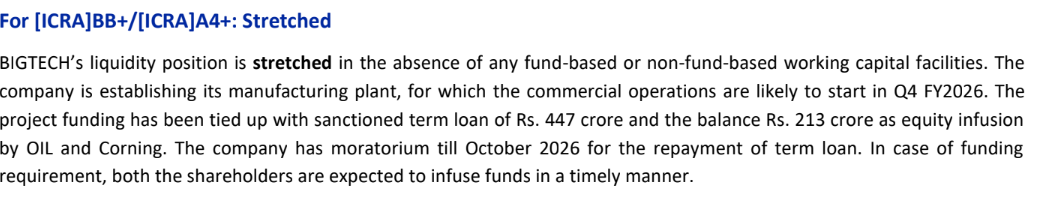
Selected for Central subsidiary Under SPECS(25% of caped ex of land, building) , Tamil Naidu Govt subsidiary of 20% approx . So approximately they will be getting back 200 crore.
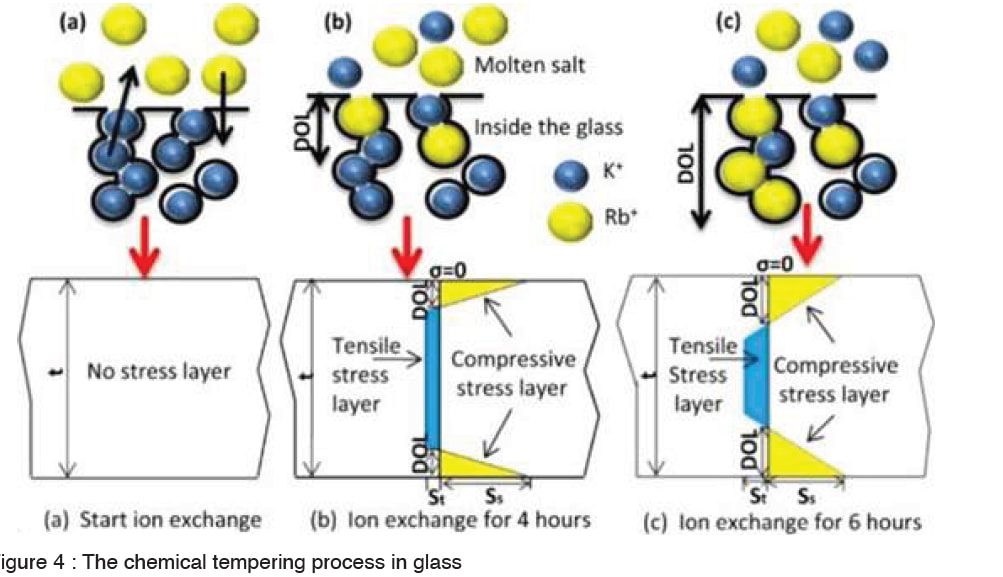
Raw material will be specialised glass sheet from corning . Their value addition will be cutting and shaping , strengthening and surface treatment and logistics to end customers. Negligible working capital is required.
Conclusion of 1st Driver
Since most phones are already using Gorilla glass , So their end customer is already sorted. Its interesting to see how much ROCE they can drive from it .
Based on 20% ROCE , this buisness is almost certain to give EBIDTA bump up of 120cr.
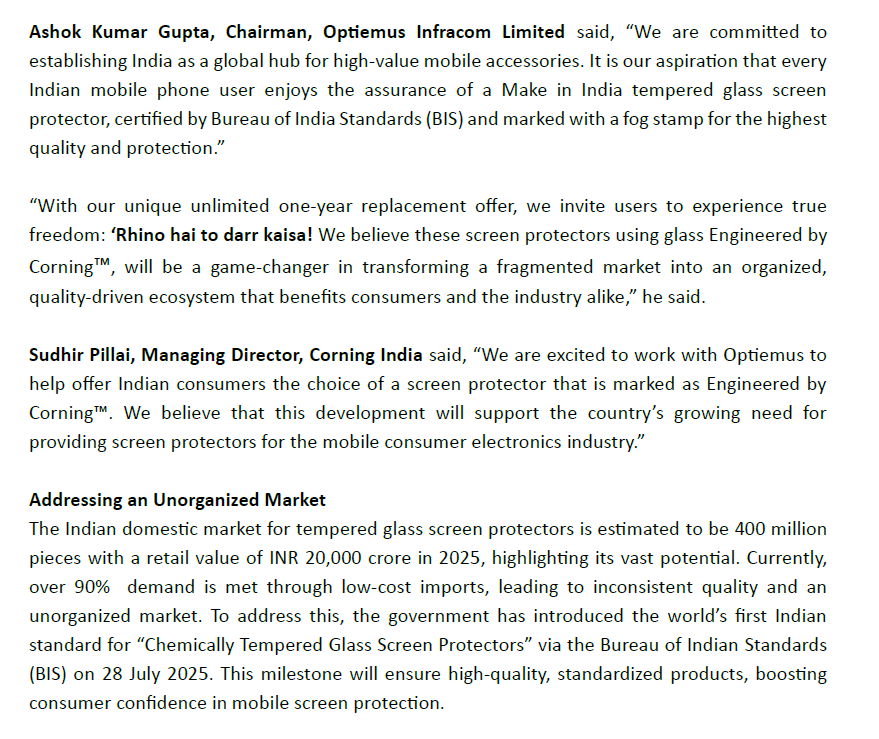
2nd Driver - Tempered Glass facility (Engineered with corning)
Today 95% of market share is low-cost imported tempered glass from china . Besides losing GST , government also found its importance for local manufacturing which is currently nil. So to restrict these low cost import
MeitY under latest circular , notified mandatory BIS certification for smartphone screen protectors from 1 April 2027.
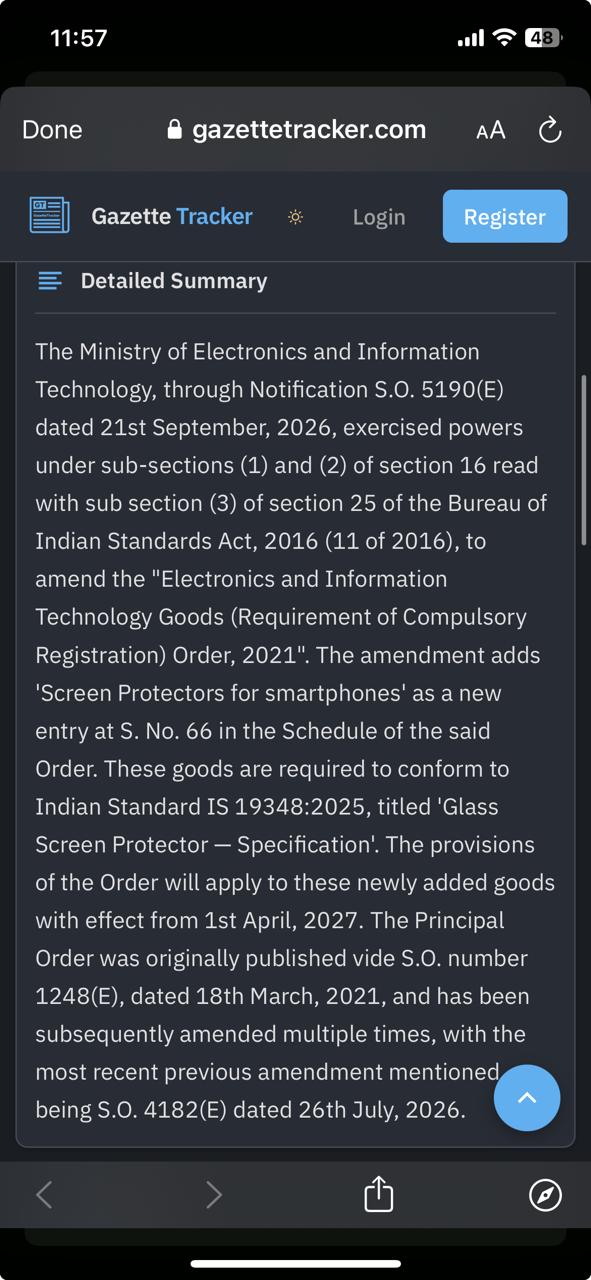
Currently India consumes 20000 crore of tempered glass annually with no local manufacturing for high quality Tempered glass . Opteimus has developed facility for these glasses with 25 million annual capacity targeting revenue upward of 1800 crore in the 1st year itself.
Conclusion of 2nd Driver
Here , Keeping in mind the Supply shortage from 1st april 2027 , and Currently no company has BIS certification acc to latest standards , healthy margins(B2C) and company partneship with corning , another significant EBIDTA bump up can happen even if BIS rules are stictly followed for online selling.
3rd Driver - Nothing partnership :
Carl pie cofounded One plus , After that he single handedly made nothing a successfull brand
Basically he wants to make nothing High end Brand and CMF mass market brand
(under 30k) which is suitable for India.
Company will be owning CMF brand(51%) , which is a budget version of Nothing and
also producing NOTHING phones and accessories for local and global market . Since they
are having synergies with NOTHING team , CMF can do wonders in the midsmartphones.
Manufacturing capacity for This JV is 6 millions smartphones annually .
Investment of 1000crore for acquiring 51% stake in CMF .
Conclusion of 3rd Driver
Manufacturing smartphone is 3.5% EBIDTA and 20% ROCE ,
volume dependent buisness(DIXON) while having a brand is a tough nut to crack but if
done can completly turn the table (market will value you as a brand) . But Since Carl pie
has already build the brand twice and his expertise in design and technology and
optiemus expertise in manufacturing their cannot be a better man to give it a try.
RISKS:
Any fail of above brands can cost hugely since OPTIEMUS is investing heavily.Performance of these brands matters. especially NOTHING partnership is the existential risk for the company as 1000 cr upfront investement will be do or die for a company.
NO MOATS in the business . Only relationship is the stickiness
5th or 6th player in the growing industry.
**BULLISH **
Company can soon come up for more capital raise because of NOTHING investment but if all cyclinders fire well , company can follow bamboo pattern.
2 Likes