Name of another 15 year back same promoter business is yet to known by ordinary investor like me. One more thing how failure of polymer business correlate Britannia promoter in present. Telling this all doubting too much will left with no investment option as finest whitewash covers dirtiest spot in big businesses, as business is no more a fare game. Who doesn’t know RIL past and their ruling in present. Its just matter of days when Indias costliest bank will prove otherwise as how in NPA burdened economy only one left light even after being one of most large player. So with due respect to all the precious inputs price definitely deserves meaningful consideration before conclusion hence there is nothing much to loose and feel afraid at these levels which support risk reward ratio.
Performance of the Company is gradually improving and seems a value buy at this level. DPD implementation had severely impacted the revenue and margins of the Company.
Inspite of loss of major revenue of CFS business from JNPT, the company has shown an impressive sales growth of 16% compounding during last 3 years. With improvement in capacity utilisation at Vapi the margins are epected to improve in future. Went through the Concal of last 12 quarters and observed that company is gradually overcoming the DPD impact and seems that now it is on a growth trajectory.
Tracking position initiated at current levels with 1% of my portfolio.
Approval for transfer of its title, rights, interest, ownership and the operations of its Business
Undertaking situated at Survey Nos. - 44/1, 44/l/l P, 44/1/2P and other, Tumb Village, Taluka
Umbergaon, Dist. Valsad, Gujarat- 396150 as a going concern, on an “as is where is” basis
(“Business Undertaking”) for a lumpsum consideration ofapproximately INR 835,00,00,000
(Indian Rupees Eight Hundred and Thirty Five Crore) to Adani Logistics Limited
(“Purchaser”) and the same shall be subject to approval of the Shareholders of the Company
at the ensuing Annual General Meeting
Stock is down 15% , any reason why the market is considering it negatively.
probably, It was the fastest growing undertaking in the company… (Not verified)
Presently, market cap is at ~ Rs. 850 Crores which is equivalent to the consideration.
The company has other ICDs, PFTs, etc as well
As per Annual Report - plans to go debt Free
Promoter has released all pledged shares…another positive sign
JSW has put in an offer at 105.32 per share. This represents 26% holding from public shareholders which as per screener is only 30%. I believe if we go by the CMP, i.e. 119 as on 12-07, it is a price that will, not be accepted. This script looks very good to me to make any short term money as JSW Infra is on an expansion spree and Navkar corporation presents a great opportunity.
Further the company seems to be capitalizing on the torrid past 1 year that Navkar corporation had financially.
Disclosure: Seeking your views and actively tracking/ not added in portfolio yet
Made a video detailing my research on Navkar Corporation and the Open Offer.
Suspension of warehousing operations under Customs Act.


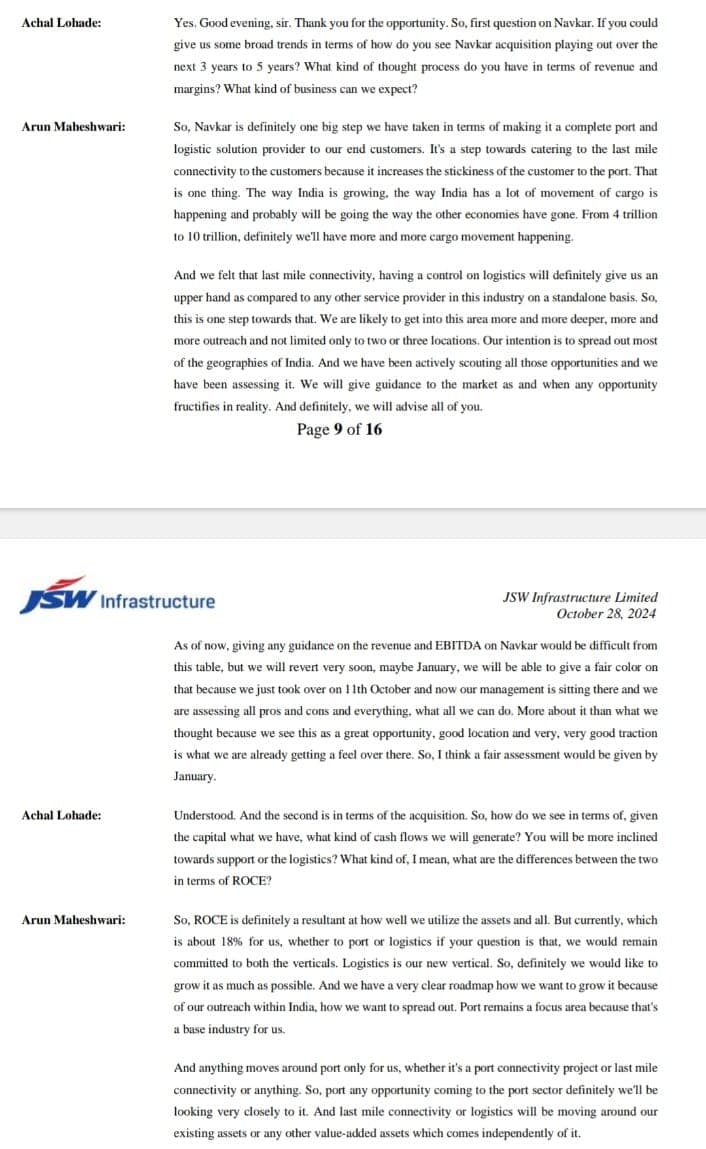
Navkar Corporation – JSW Infrastructure Concall Highlights
Acquisition and Consolidation
JSW Infrastructure has successfully completed the acquisition of Navkar Corporation at an enterprise value of ₹1,596 crore. The financial consolidation of Navkar into JSW Infrastructure’s books commenced from October 11, 2024, and was reflected in the previous quarter’s results.
Financial Performance and Accounting Clean-Up
Navkar Corporation incurred short-term losses post-acquisition, primarily due to adjustments arising from consolidation. Management indicated that a one-time clean-up of accounting practices and provisioning was undertaken. While the normalized EBITDA for Navkar is estimated to be in the range of ₹50–55 crore, the reported EBITDA for the year stood at approximately ₹10 crore, owing to these transitional adjustments.
Planned Investments and Strategic Outlook
Recognizing untapped potential at Navkar—given the absence of major investments in the last two years—JSW Infrastructure has approved a capital infusion of ₹170 crore specifically for enhancing operations at Navkar. This initiative forms part of the broader strategic push in the logistics sector, where JSW Infrastructure sees substantial growth opportunities.
Looking ahead to FY26, JSW Infrastructure is targeting over 50% revenue growth across its logistics vertical. While this guidance encompasses the entire logistics segment, Navkar is expected to play a key role, with a projected EBITDA of ₹100 crore. Management anticipates that Navkar’s performance will benefit meaningfully from group synergies and operational integration.
Guidance for Navkar has been explicitly provided only for FY26; long-term targets are expected to be communicated in subsequent updates.

navkar.pdf (2.2 MB)
Excellent turnaround by JSW Ports management (JSW Infra) but I guess market is worried about drop in volumes in export.
This quarters, results are also good, but still the stock took a hit. I am trying to understand, what could be the market expectations. The return ratios are not good, definitely bad but we also need to understand this is a turn around story.
If anyone have any rationale, why the stock is takling a hit, Please let me know.
During Q2 FY27, the company achieved its highest ever topline of ₹223 Cr (growth of 37% YoY) but EBITDA margins remained at 15% - there was no benefit of operating leverage. This is the likely reason markets didn’t give it a thumbs up in my view.
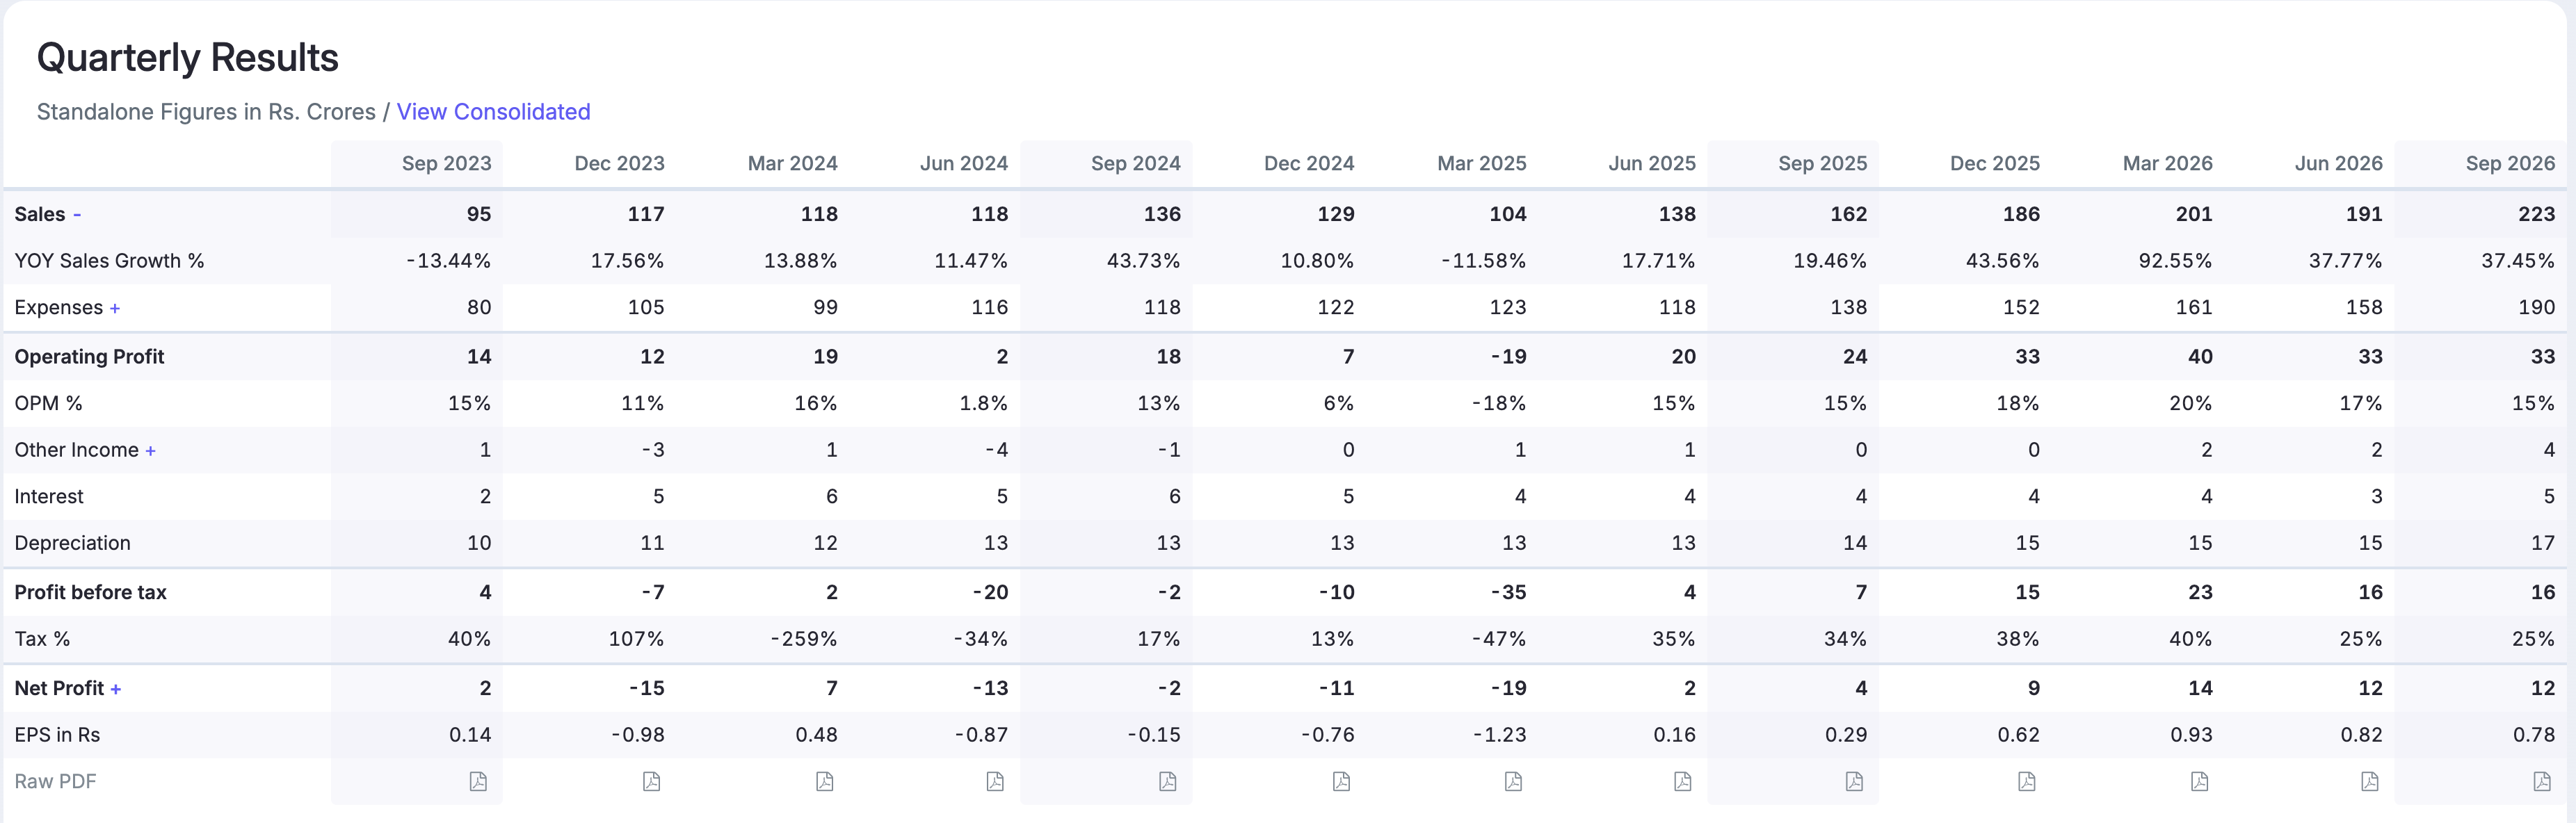
There might have been some impact of the geopolitical situation on their EXIM biz so next couple of quarters are very crucial. If they can regain 20% EBITDA while maintaining this revenue runrate of > ₹220 Cr, we might see a good rerating. In that case, EBITDA can cross ₹45 Cr and PBT should be > ₹25 Cr and PAT > ₹19 Cr (annualised ₹78 Cr PAT and market cap of ~1.1k Cr).
The company has also received LoA for 2 GCTs on railway land - 1 of which will become operational this year and most likely 2nd one will be operational in the next financial year end.
In my view, the peak revenue potential would be > ₹1300-1400 Cr with 20% EBITDA. Return ratios will also improve as incremental capex will not require land acquisition. The current value of land on their books is ~ ₹1100 Cr out of total fixed assets of ~ ₹1900 Cr.
So if I am buying a company at ₹1100 Cr which can achieve an ebitda of > 250-260 Cr without much of increase in debt levels and the company is backed by JSW, I don’t think there is anything to lose. JSW acquired Navkar at ₹1500 Cr market cap.