Interesting PF @nav_1996 . Glad to see your long term conviction on HDFC, Biocon etc.
I also hold ITC among your picks a small picks. Likes to.know what is your overall CAGR and which pick of yours did well
Interesting PF @nav_1996 . Glad to see your long term conviction on HDFC, Biocon etc.
I also hold ITC among your picks a small picks. Likes to.know what is your overall CAGR and which pick of yours did well
I really don’t know CAGR and I don’t intend to measure it as chasing CAGR is fraught with accidents . (Also difficult to measure as I have few demat accounts and last time I tried to figure out it was close to index + div yield). Idea is to hold simple to understand, secular growth stories for long.
Downside is that I completely missed out on chemical growth.
Biocon: I had much larger weight. But I trimmed as it too complex to warrant a large holding.
Chola and Titan have been 10 baggers whereas Dabur, Marico, Biocon and Nestle ~3x .
Glenmark and Lupin where temporary 3x but back to buying price 
Thought I will update my portfolio as it has been quite sometime.
There has been no major changes. Moved out of Dabur and trimmed some OFSS. Funds went to add Brookfield REIT, IRM Energy and SF Holding.
Moving out of Dabur was based on slower growth in FMCG going forward and I wanted to trim one of FMCG stock. Dabur appeared to be obvious choice as its portfolio is full of legacy products rather than aspirational products.
Trimming OFSS was super costly mistake due to recent runup. Last time I made this mistake was with ITC. One of reasons I am so scared to make changes to PF.
| Cholamandalam | 13.6 |
|---|---|
| HDFC | 13.2 |
| TITAN | 11.6 |
| OFSS | 10.5 |
| L&T | 8.4 |
| M&M | 7.1 |
| Nestle | 6.1 |
| United Spirits | 5.6 |
| Marico | 3.7 |
| Reliance | 3.5 |
| ITC | 2.7 |
| Brookfield REIT | 2.1 |
| IRM Energy | 1.9 |
| SF Holding | 1.4 |
| Cipla | 1.4 |
| Lupin | 1.3 |
| Biocon | 1.1 |
| Glenmark | 1.0 |
| Sanofi | 0.7 |
| ITBEES | 0.7 |
| Indus Tower | 0.2 |
@Vivek_6954 for your review.
Added Rane Brakes < 1% by trimming bit of Marico. Intention is play emerging manufacturing theme with well established and entrenched player
Thesis on Rane Madras board
Have not been updating this thread for a long.
Another milestone today after Titan became a 25x . Second one after Chola.
Have got rid of all pharma names except for Cipla and Emcure.
Had added Aditya Vision in 2024.
Continue to build on manufacturing themes. In addition to SF Holdings (which was added earlier), have aggressively added Carraro India and SKF India Industrial this year.
Regret having missed out on electrical and EMS themes completely. Was never able to develop conviction vis-a-vis valuations.
Here is what PF looks like now
| Cholamandalam | 15.2 |
|---|---|
| TITAN | 13.8 |
| M&M | 12.3 |
| HDFC Bank | 10.1 |
| Oracle Finacial | 9.6 |
| United Spirits | 6.2 |
| PowerGrid InvIT | 5.1 |
| Marico | 3.6 |
| Carrarro India | 3.4 |
| TSF Holdings | 3.1 |
| Reliance | 3.1 |
| SKF India Industrial | 2.8 |
| Brookfield REIT | 2.3 |
| Aditya Vision | 2.1 |
| Nestle | 2.1 |
| ITC | 1.5 |
| Emcure | 1.4 |
| Cipla | 1.2 |
| Orkla India | 1.2 |
Expecting maximum alpha from HDFC Bank, Carraro India and SKF industrial over 2-3 years and may be Reliance
you exited dabur at right time and good decision. I am still stuck with it although 2% of portfolio but it hurts that its still around covid levels!
same with hdfc life … even sbi life has been almost 3x ipo price but hdfc as a group has been laggard. This one is around 5% of portfolio.
Any suggestion on these two and if i swap, which sectors look promising to you for coming decade to look for switching winners?
Lastly i see you exited L&T…whats the reason for that as its in your core theme of manufacturing/epc/data centers/energy ?
Electricals/EMS and manufacturing seems to be theme which I see growing.
I am not comfortable with valuations of electricals/EMS so I have focussed
I am focussing on manufacturing overall where I find valuations more reasonable.
L&T is mainly a construction company. EPC no one makes decent money. They are too large with moderate growth.
Manufacturing and other new age biz are too small to move the needle for L&T. Software biz is also mature now.
I exited in 2024 when valuations became uncomfortable.
can you pls mention some thoughts about business & growth for your manufacturing picks like skf, carraro and others…
SKF India Industrial
Why ignored:
SKF India Industrial came into picture after its de-merger from SKF India.
Last few quarters numbers are messed up due to demerger charges.
What is business:
Industrial bearings (Railways, Defence, Wind power (main) and other industries
Off-highway machinery
Tractors
Competitive landscape will not change much as three companies listed in India SKF, Timken and Schaffer are market leaders globally also.
Investment thesis:
Valuations:
Using last Q and forward looking numbers
Sales based
Timken India: 5.5 Price to Sales
Schaffer India: 6 Price to Sales
SKF: 3.5 Price to Sales
Profit based
SKF combined was around 600 Cr profit. 400 Cr roughly for industrial and 200 Cr for Auto.
(ICICI report: For FY26, revenue from operations stood at ₹3,440 crore, while PAT came at ₹218 crore despite absorbing exceptional costs of ~₹196 crore related to demerger expenses and land transfer premiums.)
That gives SKF Industrial a valuation of close to 35 PE.
Schaffer trades at PE of 53 (Despite having auto which is lower margin than industrial)
Timken trades at PE of 58 which is mostly industrial and heavy vehicles.
What is changing:
Growth accelerating : Last Q saw a sales growth of 30% YoY and 10% QoQ
Driven by focus due to demerger and they getting back into railways which they had ignored
Currently margins are lower due to imports and using SKF auto manufacturing.
They are putting up a new factory in Pune with investments of 600-800 crore.
Upside
If price to sales and PE converges with existing players by year end, SKF India Industrial can easily see more upside from current levels.
Also, pre-demerger share prices were close to 5000 for SKF combined. After demerger it is still 4200 (2700 industrial + 1500 auto). That suggests price discovery has not been perfect.
Disclosure: Invested between 2200-2400. I am not a certified advisor. Use your own discretion.
Carraro
I am not a big fan of MNC companies(especially in non-FMCG category) because they are typically a small fraction of parent business and don’t get required bandwidth and have multiple unlisted subsidiaries in India often with conflicting interest.
But Carraro India appeared very different.
Who are they and what they do.
They are subsidiary of Carraro Italy.
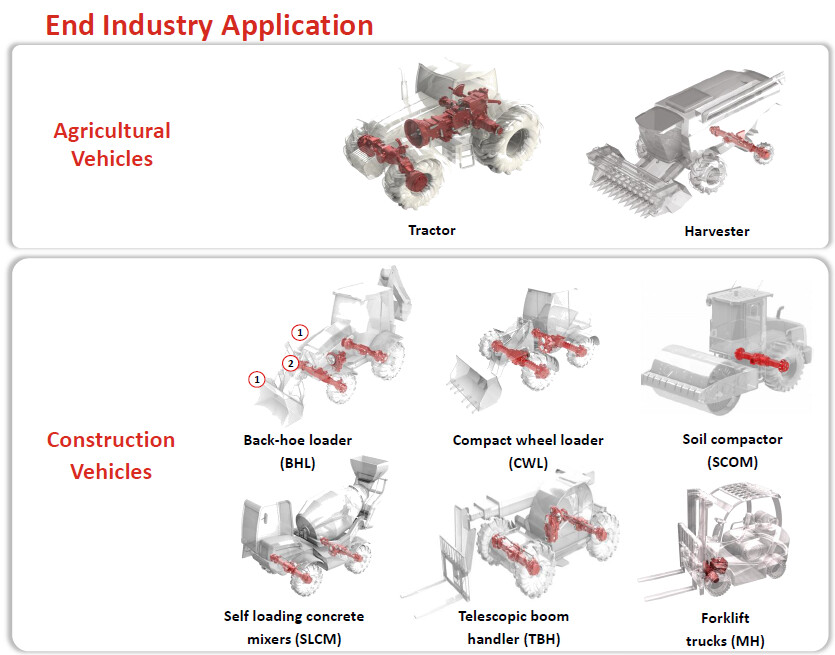
Carraro India is a Tier-1 provider and manufacturer of axles and transmission systems for tractors and off-highway vehicles like construction equipment, cranes etc Parent company is in same business.
This diagram explains it neatly.
They make axles and drivelines (things in red).
These are critical systems designed for OEMs and can not be replaced by another vendor. OEM has to plan in years to get the right vendor. And that is the moat.
What are revenue streams

Financials:
They have done 2325 crore revenue and trade at mcap of 2850 crore and PE of 21-22.
Last Q they had 10% growth but margins were slightly suppressed due to higher raw material costs and war issues. Raw material is generally passed on to customer with a lag.
What makes it attractive:
Attractive valuations: Very low PE compared to similar tier-1 OEMs like Bosch, ZF or Jtekt India.
Attractive valuations: Dana had offloaded global off-highway axle and driveline biz at similar price to sales. So valuations are in line with global valuations and not demanding Indian premium.
Unlike other MNCs, Indian subsidiary forms 30% of parent revenue. So key entity for parent.
They don’t have any other subsidiaries. They have transferred all product IPs and India design centre to listed entity before IPO.
Design centre is becoming important as minor revenue stream. They are taking up complex projects like electrical drives.
They only have 3 global manufacturing centres, Italy, China and India. So huge opportunities for export.
Tractors are steady state biz.
Govt has incentives for pushing construction equipment biz.
Moat with most Indian OEMs as end customers.
Risks
OEMs doing backward integration. This is low risk as OEMs depend on Tier-1 supplier for bringing in innovation.
No after-sales secondary market like simple auto parts as these systems typically last for the life of equipment.
Disclosure: Invested around 540. I am not a financial advisor. Use your own discretion.
There are detailed thread on Mahindra, TSF, Titan etc
SKF India industrial revenue growth was solid 18%. But like all manufacturing companies margins were hit and had slight drop in profits.
Rail, defence and wind power should continue to provide solid tailwinds for next couple of years
SKF India Industrial expects top line to nearly double in 5 years | Company News - Business Standard
@Administrator @Satishwe Can you kindly rename the thread to “nav_1996 portfolio - Discussion & Ideas”
Carraro is going through some interesting developments.
@Satishwe Can you kindly rename the thread to “nav_1996 portfolio - Discussion & Ideas”
I feel that relentless rise in US bond yields and even Indian interest rates will put pressure on stock valuations.
FIIs have no incentive to invest in India now. They can get risk free 5.2% on US bonds.
I am no good at prediction but have tried a raise a little cash.
India is at biggest capital cost arbitrage situation in ages .. All the time India capital cost was > 5% of rest of world .. This is huge incentive for capital hungry India ..
Yes, that may be true in long term. But doesn’t help markets in near to medium term.
But our interests have been kept artificially low as RBI front loaded interest cuts to spur economy last year but inflation didn’t behave the way it should have.
I wrote this last year in Long term bonds thread
Market is expecting rates increase this month