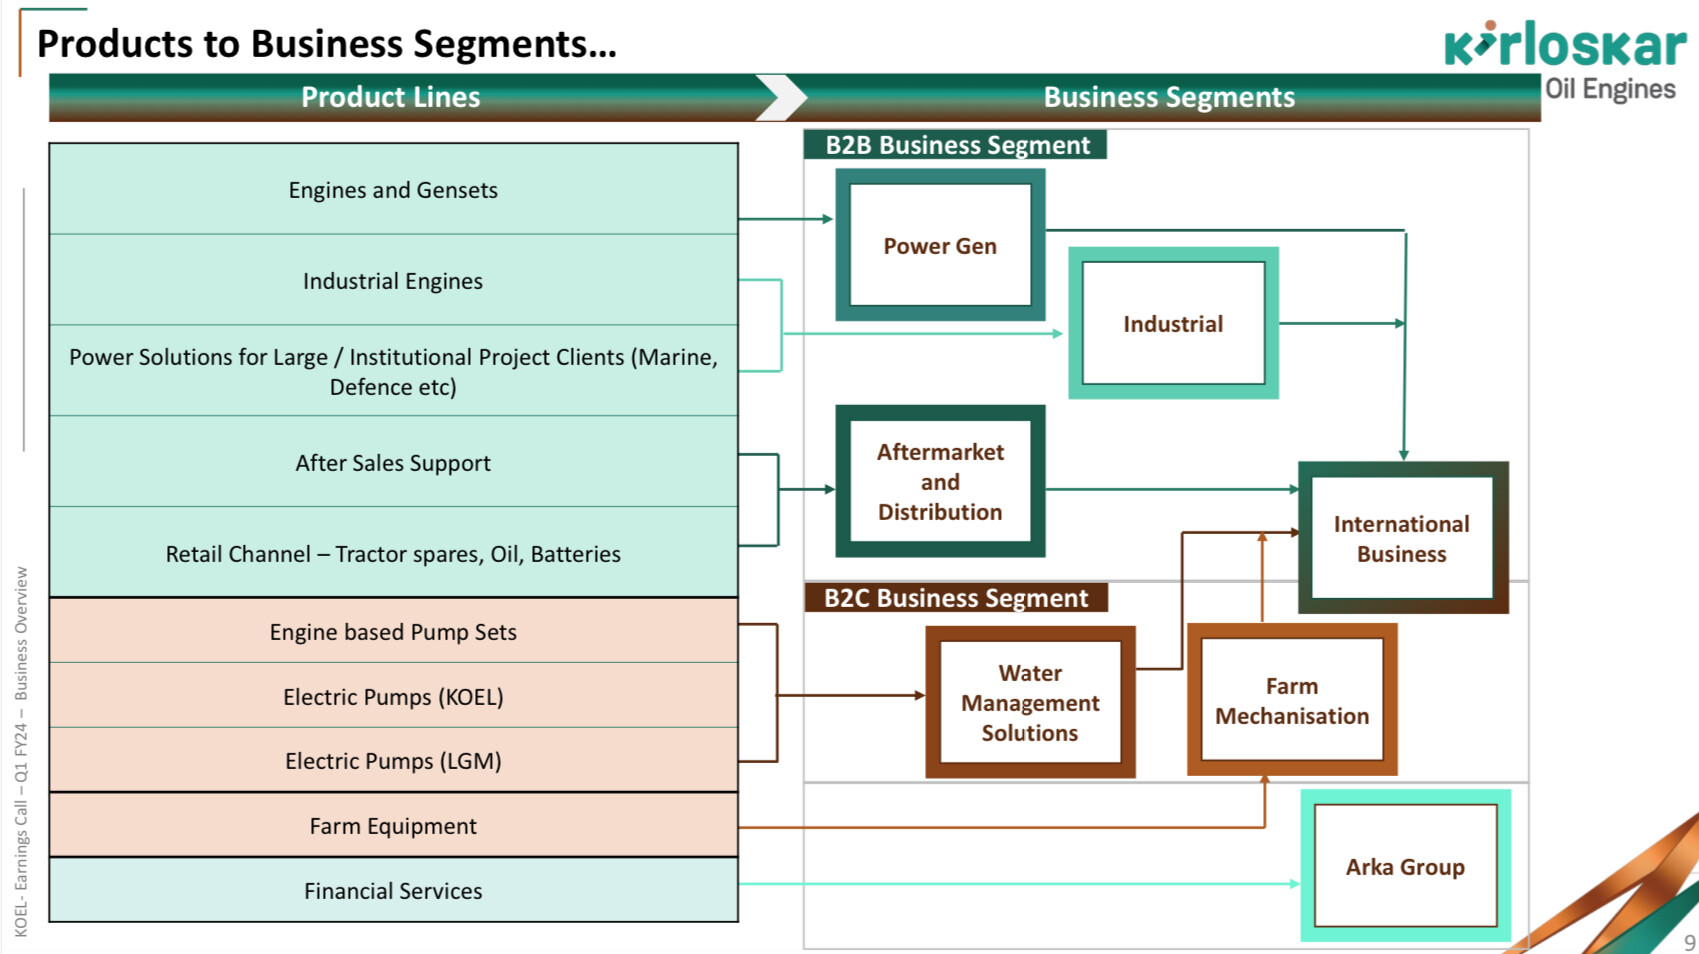
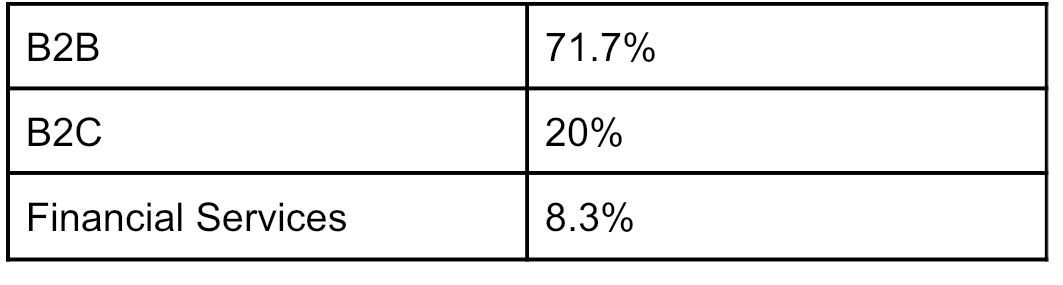
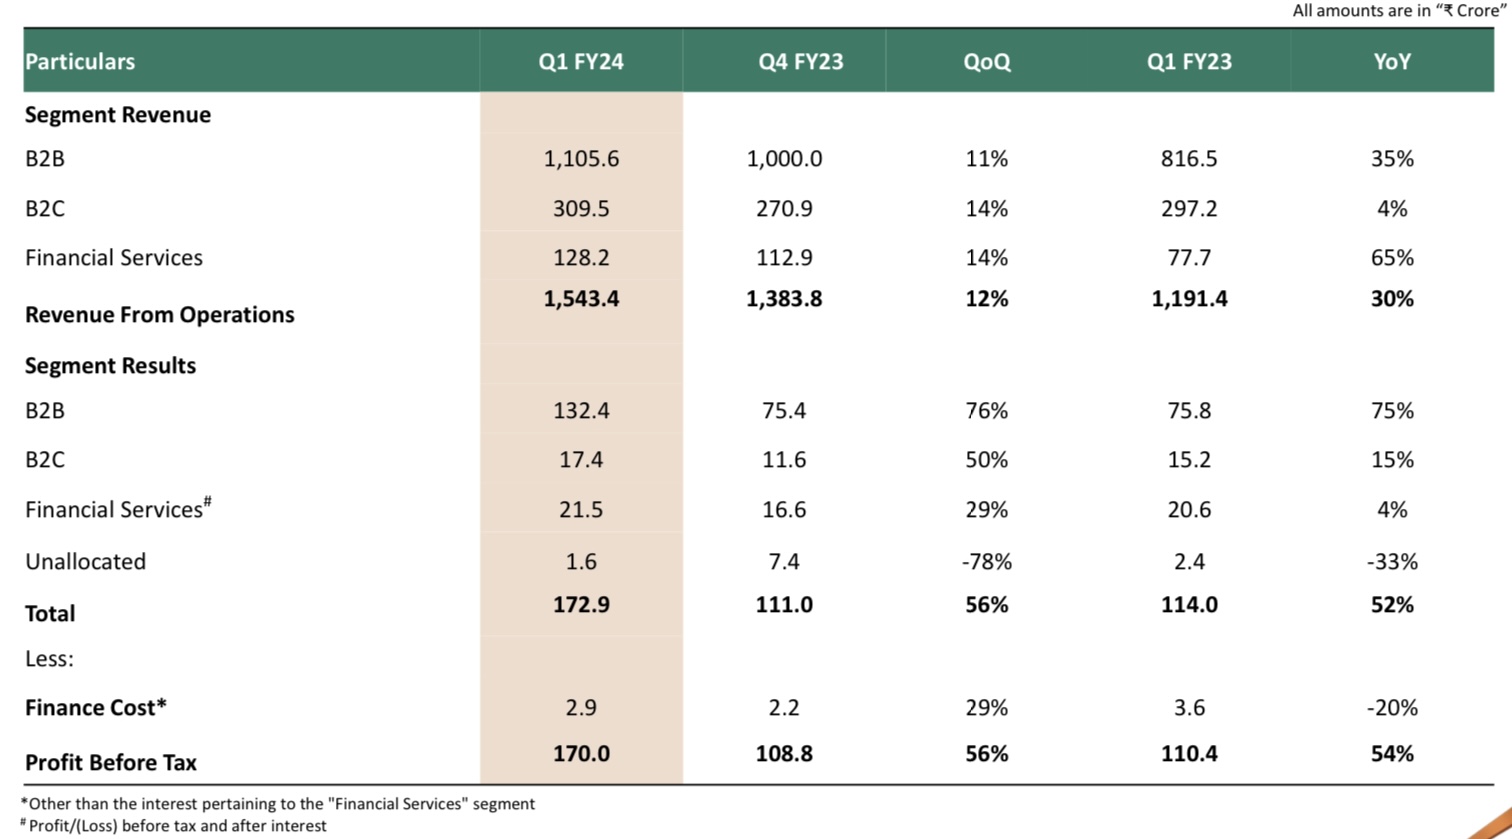
It’s customers in the B2B business are predominantly from industries like Power, Telecom, Railway, Infra, Railway, Defence and also Data centres
B2C customers include ones from Agro and Irrigation
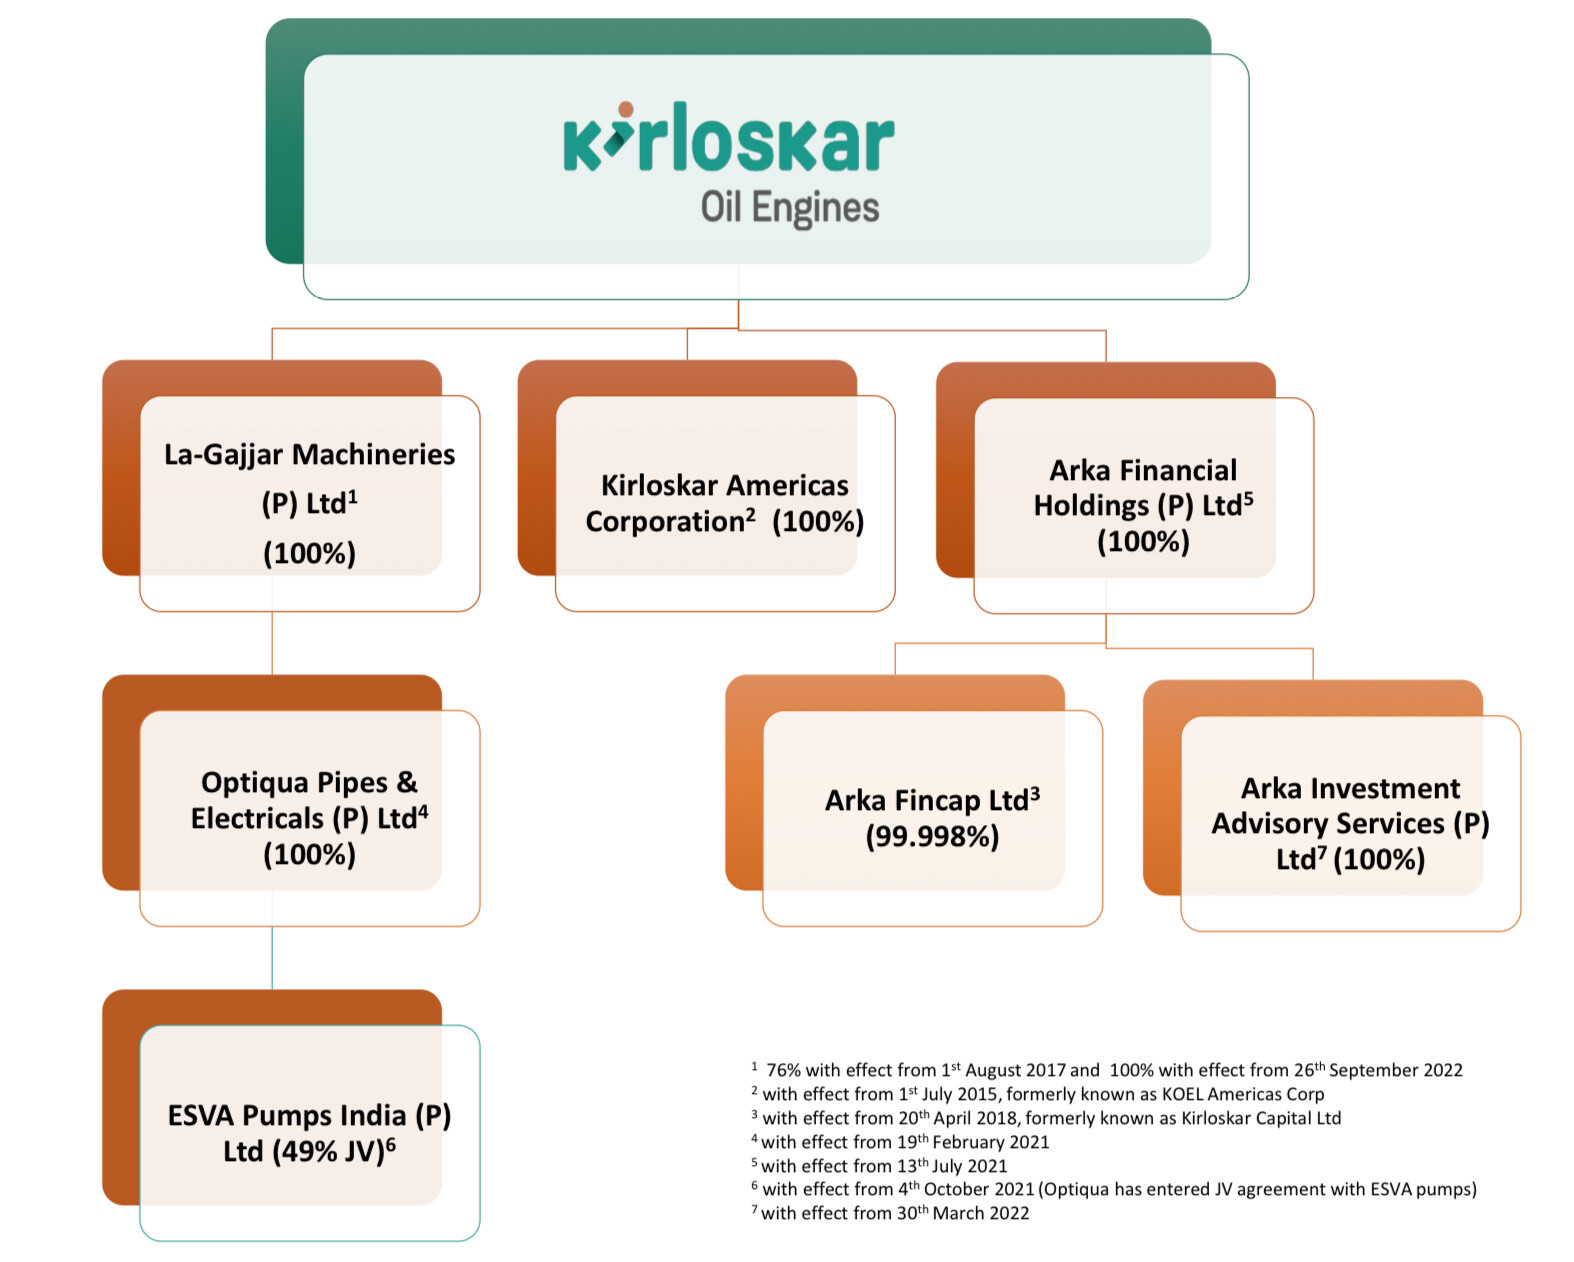
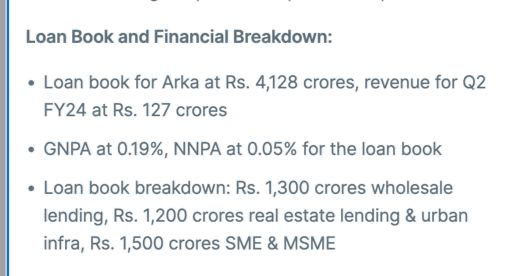
Arka Group is a NBFC with focused lending in sectors like real estate, Coporate lending and SME lending (initially started with 500 crores, to diversify business; had very strong and robust balance sheet, and maintained healthy cash positions)
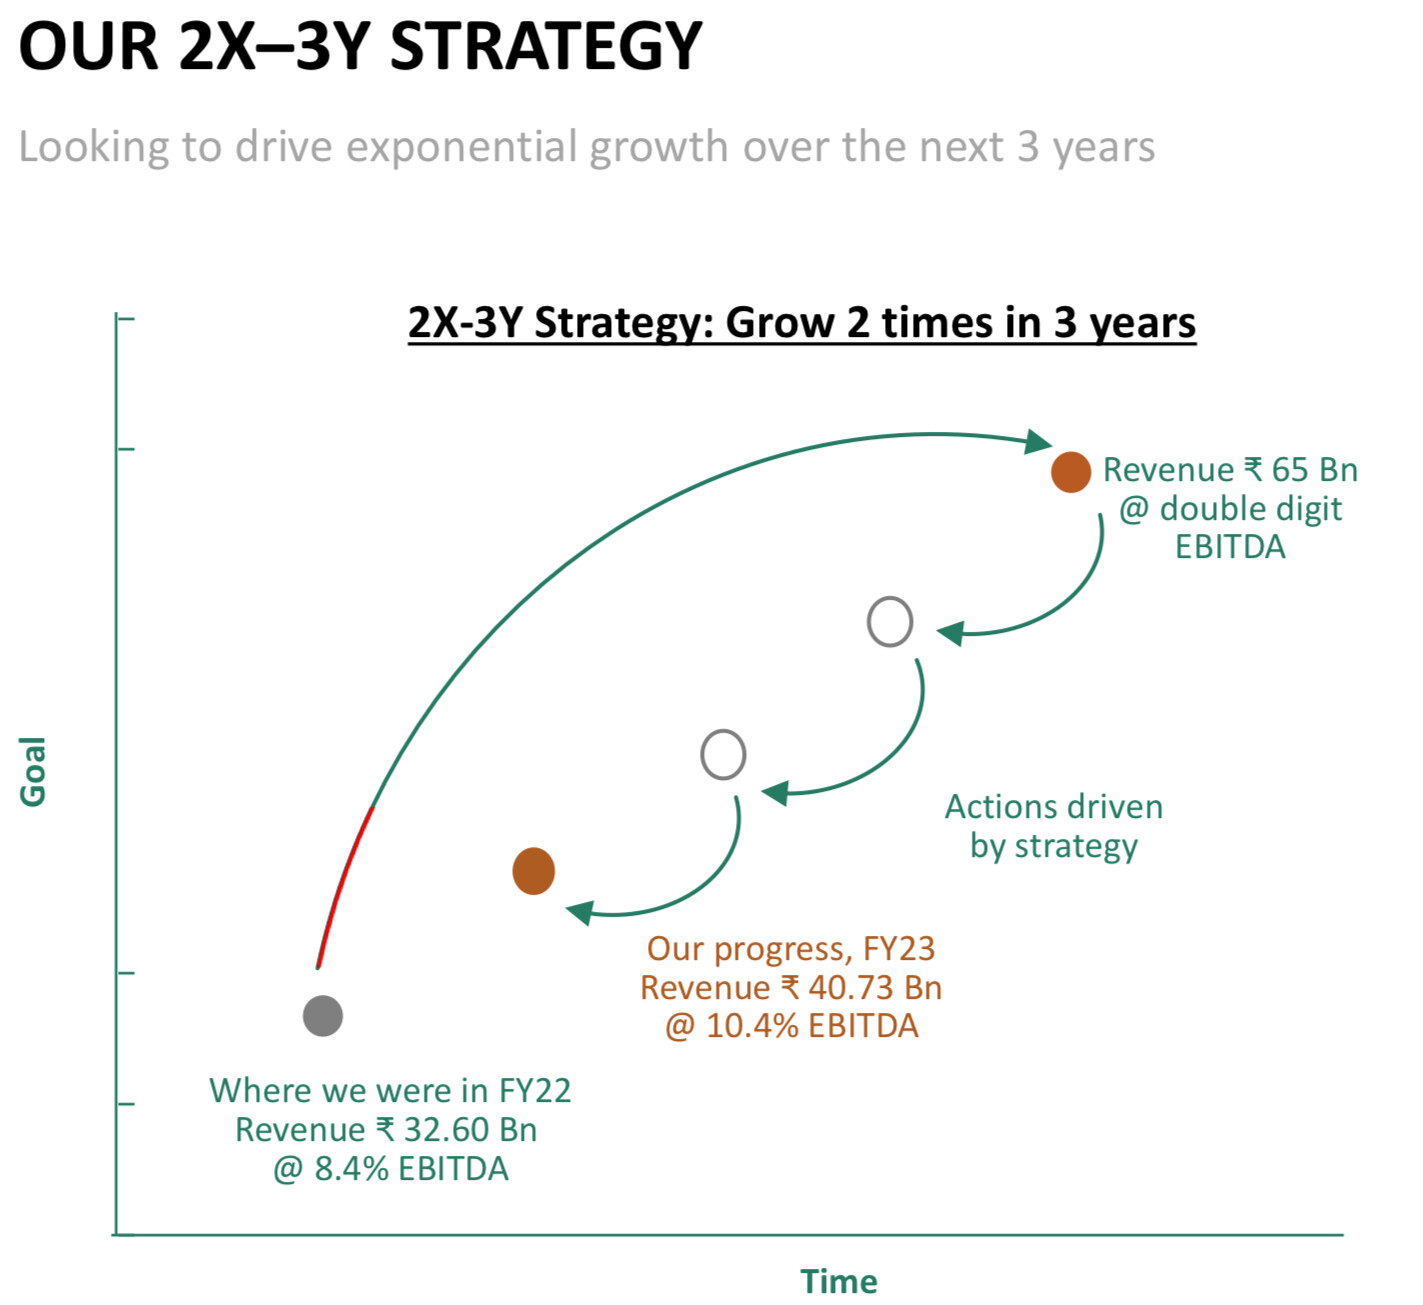
The management had planned for 2X-3Y Strategy; Double the topline in course of three years(indicating an avg revenue CAGR of 24%)
Thanks @Subham_Jain for sharing
People who are believing in capital goods cycle/ manufacturing upward trend in coming days… this is good company to play it. Debt free , good ROCE, proven management and reputed brands in B2B
Disc: holding this company from lower level
B2C business showed more than 20% YoY growth in Q2, with margins on track
Launched new products such as OptiPrime and OptiPrime Hybrid range of gensets
Focus on margin enhancement through high horsepower segment, service and aftermarket business, and international markets
Strong order book and readiness for CPCB IV+ norms in the second half
White labeling not preferred option for exports
Strong demand from OEMs in the industrial segment
Strong demand from infrastructure and data center sectors in Power Gen segment
CAPEX focused on technology and engineering for emission norm changes and new product launches
Q3 FY24 saw highest ever sales with a 14% year-on-year increase in gross revenue.
Growth in net sales, EBITDA, and net profit on both quarterly and year-to-date basis. * Expansion in the Middle East market with the appointment of a GOEM called My Span.
Notable achievements include winning a large NPCIL order for gensets and acquiring Wildcat Power Gen in the US.
Industrial segment saw strong demand from construction and railway sectors.
Strong growth and margin improvement in Water Management Solutions business, focusing on domestic and agri pumps.
@Subham_Jain can you shed some light on whether there’s any further valuation left after the recent run-up. Looking at their targets, it looks like the PE already discounts all near term positives
Also, have a few other questions after glancing through the latest PPT:
The company grew it’s standalone sales by 18% in FY24 and as per their target, they need 35% growth in FY25, do you think that is possible?
What are the revenues that are not considered in Standalone but considered in Consolidated: A) Financial revenue of 564 Cr but I can also see revenue gap of 47 Cr in B2B and 481 Cr in B2C revenue?
Highest ever Q1 sales recorded during Q1FY25. The first quarter of last year had pre buy included and thus 6% yoy growth over that quarter is great because if that effect is negated growth on a yoy basis is 18% in Q1FY25
On the power gen side the CPCB IV plus capacity has been ramped up effectively and the company has also got approval for natural gas nodes
In the B2C segment the relocation of manufacturing facility is happening as per plans
The AUM in ARKA stood at 5768 crores as on June 2024
Over the past 2 years the business has been restructured and cultivated a strong company culture which will prepare the company for the long part that lies ahead
The idea is to change the company from an engine manufacturer to a power and energy solutions provider
The path for next five years is to be a $2billion enterprise by 2030 and the levers that will be used to achieve this are to manufacture more, the new plant on the B2C side and the company is an engineering company which will continue to invest behind R&D
The company will evaluate inorganic opportunities only in areas which are core to the company and its operations
The net cash as on end of Q1FY25 was around Rs 400 crores
The long term debt rating has been upgraded by CRISIL
Participants
Sancheti Family Office
DSP
Subhkam Ventures
Edelweiss
Macquarie
One up Financial
Motilal Oswal
Oaklane Capital
QnA
The data centers buy a various type of power backups and power gensets are critical for a data center. The company is developing a range that will allow them to be aggressive in this segment along with maintenance contracts for the same which brings in annuity business
The life of a genset is 15 years
The annuity contracts associated with maintenance varies according to scope of work and can vary but the idea is to help keep 24x7 uptime
From an end customer standpoint not seeing any varied signals and demand continues to be strong without any challenge or softening
The service channel is being ramped up and capabilities are being built so that after market can be serviced and growth can be maintained
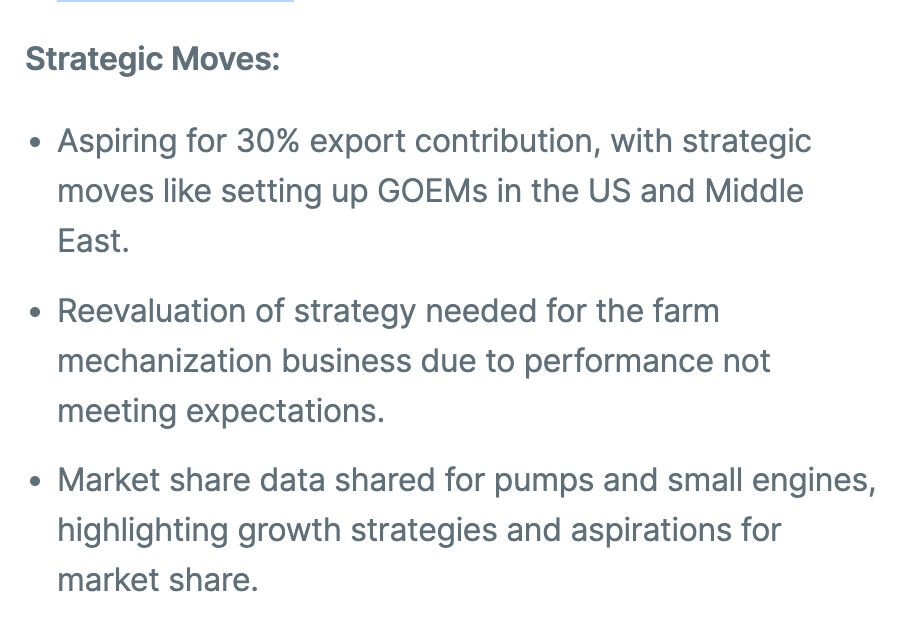
The 5 year target is an ambition and not a clear number with areas of focus already outlined and most of the growth that will be achieved will be on the B2B side
On the international business identifying open space where the company can win and working on what kind of channel and distribution network will be needed
Currently the capital adequacy in “ARKA” is adequate and there are no considerations for new capital addition as the company is not leveraged to that extent
In power generation the company currently has a market share of 30% and in CPCB IV Plus it has a product range across both diesel and natural gas segment
On margin front expectation will be to remain in double digits without a firm commitment on any certain number
The demand is stronger across construction and infrastructure sector. Across railway and defense there are stronger opportunities
The focus is currently on augmenting capacity of high horsepower gensets and bulk of the execution of this capacity will happen over next 2-3 years
The company has received the patent for India for hydrogen internal combustion engine gensets
In the B2C business very close to double digit margins on an annualized basis and idea is to maintain double digit levels going forward as well
The big improvement in margins in CPCB IV Plus will come from aftermarket and services which will commence once the warranties get over for the products
The Rs 700 crore capex that the company will incur is a fresh investment over and above the normal capex that the company will incur over the next 2-3 years
At this point channel will focus on CPCB IV Plus products as the industry has moved to that era
Was researching this company mainly for the uptick in manufacturing including data center capex, but the high levels of debt, low ROCE. mostly negative FCF is not encouraging! What am I missing? are these due to cap additions or a symptom of something else?
ATH, 49 PE. I think the risk to reward ratio is not good now. Everyone is talking about Kirloskar Oil now. The interest paid for the debt was more than net profit till last year.
Kirloskar Oil Engines wins 192 MW power order for AI data centre (not a good idea to trade on news)