Kheria Autocomp Ltd
Auto ancillary - Plastic Molding of car parts
Exchange: NSE Emerge
Basic Details
• Market Cap: ₹ 141 crores
• Issue Price: ₹ 101
• Current Price: ₹ 89 (as of 13-Oct-2026)
• Listing Date: 24-Sep-2026 @104.90 only
Financial Highlights
• Revenue (Latest FY): ₹[X ] crores
• Net Profit: ₹ 120 crores
• ROCE : 26%
• Debt-to-Equity: 0.43X
Business Overview
Kheria Autocomp manufactures durable exterior and interior plastic parts—such as bumpers, spoilers, and dashboard trims—for popular passenger vehicles like the Tata Nexon and Hyundai Creta.
The operational model of Kheria Autocomp functions within a closed-loop automotive manufacturing framework where raw materials, physical conversions, and economic transfers proceed through five distinct stages.
At the manufacturing stage, Kheria operates injection moulding machinery across varied clamping tonnages equipped with automated material conveyance, robotic pick-and-place units, and secondary finishing tools such as ultrasonic welding fixtures and hot-stamping cells. Production is executed against customer-owned or amortized tooling dies engineered to strict CAD/CAM tolerances established by Tier-I engineering teams
Revenue is generated through the contractual manufacturing and supply of components segmented into four functional categories:
- Interior Trim Components, including tailgate trims, C-pillar garnishes, front door inner trims, and luggage partition panels
- Exterior Functional Modules, consisting of roof garnish bases, front bumper garnish mouldings, rear spoilers, and protective door claddings.
- Under-the-Hood Assemblies, comprising engine coolant expansion tanks (P-tanks upper and lower) and cooling fan shrouds.
- HVAC and Ventilation Assemblies, including air blower housings, fresh-air intake ducts, and temperature-control routing paths
Kheria does not have traditional business moat but it has Geographic Proximity inside Vendor Parks - Operating within the Tata Vendor Park provides a structural logistics advantage, Switching Barriers and Dedicated Tooling Capital Commitments.
Sales growth from 62 cr to 120 from 2024-2026.
OPM % - 16-19%
PAT from 3 to 11 in same period.
Quality of Earnings & Cash Conversion - Cumulative CFO of ₹58cr outpaces Cumulative PAT of ₹25 cr(2.29x conversion)
The company is led by the founding Kheria family Chairman and Non-Executive Director Tara Chand Kheria (age 74) brings over 32 years of precision injection moulding experience. Managing Director Vinay Kheria (age 53) oversees operations, tooling strategy, and Tier-I commercial relationships, with 32 years in plastics and 14 years in automotive components.
The execution record indicates consistent capital deployment. In FY25, as Plant I utilization reached 98.90%, management added 1,200 MTPA of capacity for FY26 while sustaining high utilization at 93.73% .
Future Growth
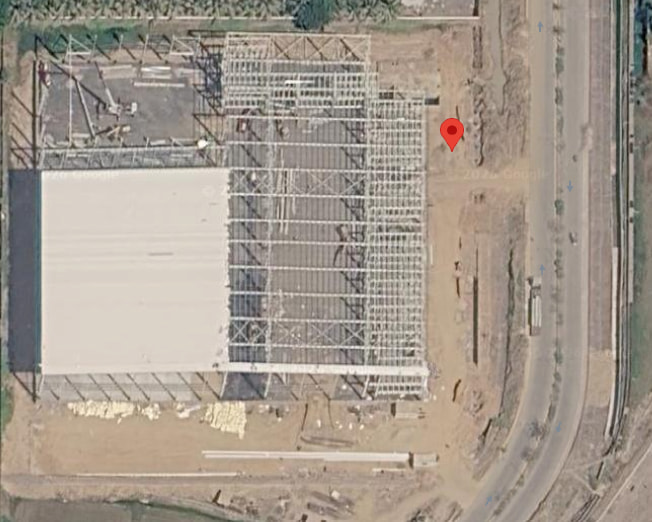
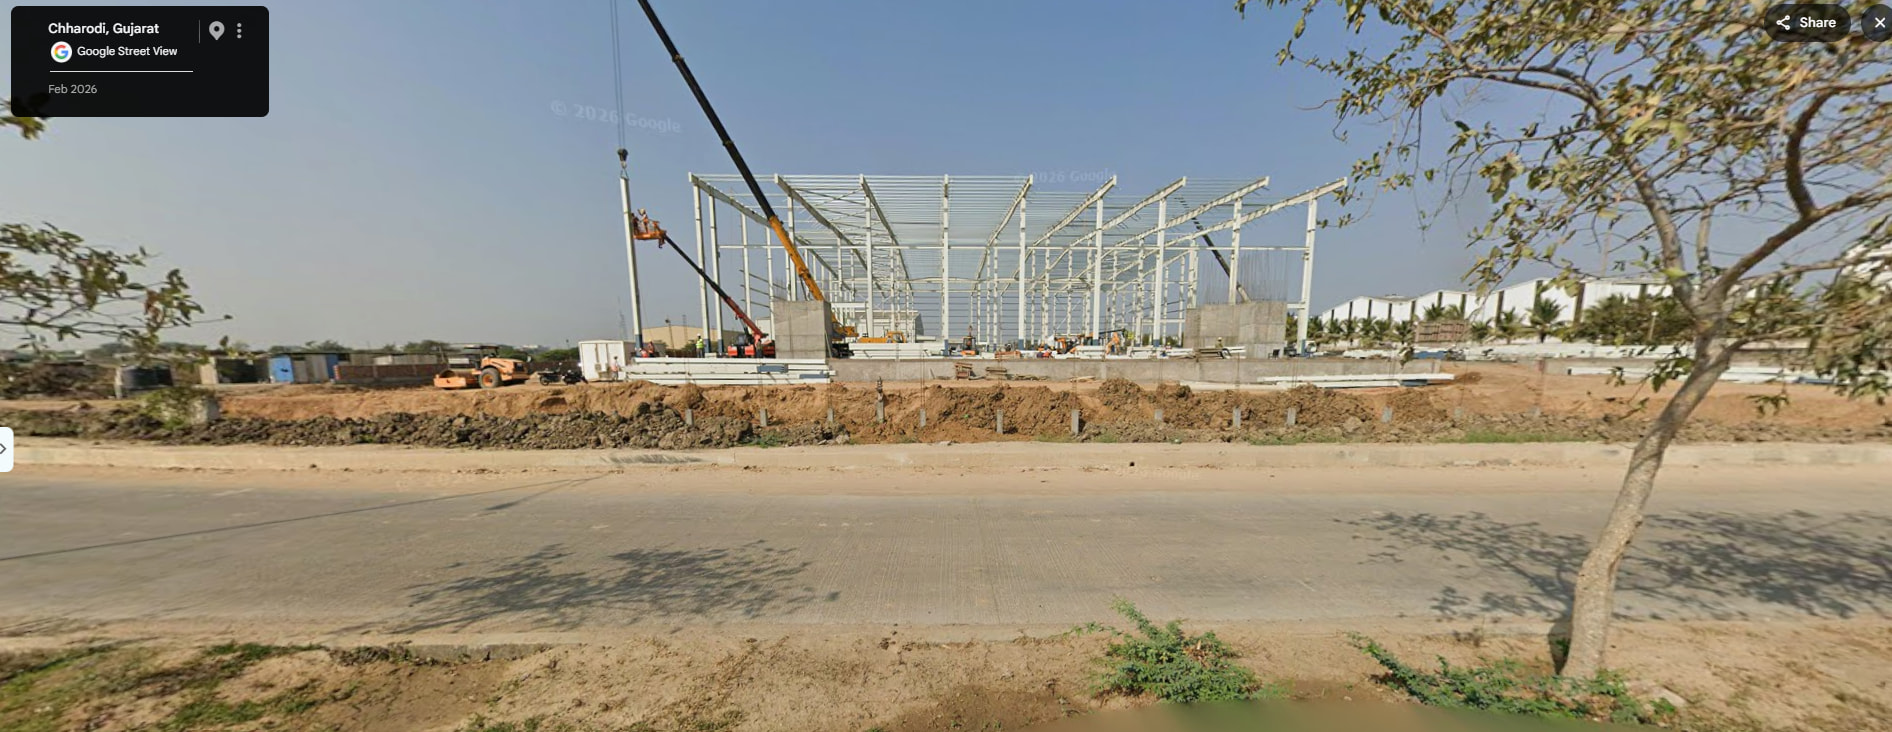
Kheria is constructing Plant II at Plot E-560, GIDC Sanand-II Industrial Estate, Ahmedabad. Estimated cost is 67cr. out of that 25 cr already deployed and rest around 40 via ipo proceed. This will increased the capacity to 7800 MT/year(Addition of 2400 MT/year). and Operation may be start from Jan-2027 and Incremental revenue will be 120 cr appx. and impact start from FY27 and full in FY28.
Valuation
- Pre-issue FY26 P/E stands at 9.95x based on an EPS of ₹10.15 on 1,12,50,000 shares
- Post-issue diluted FY26 P/E is 14.01x on a diluted EPS of ₹7.21 across 1,58,48,400 shares
- Current PE is 9X
- Peer - Machino Plastics trades at a trailing P/E of 104.31x and PPAP Automotive trades at 5.82x P/E
- Paying 9x post-issue diluted earnings for a company expanding its bottom line at a >50% CAGR provides a reasonable valuation framework for growth-oriented investors.
Forward Projection
- Based on Plant I maintains high capacity utilization (5,400 MTPA capacity base) through FY27 Plant II (2,400 MTPA) commences commercial operations in January 2027 (Q4 FY27), contributing ~300 MT of volume in FY27 before reaching normalized utilization in FY28
- Rev may reach at 180 cr in FY27-28 , Growth of 26% and PAT from 11 cr to 20 cr. EPS from 7.21 to 13. If considered 16X PE than Appx Price will be near to 180-200
Concentration RISK
The largest single customer accounted for 30.99% of total FY26 revenue and The top 5 customers generated 97.32% of total FY26 revenue and The top 10 customers contributed 99.95%. Customers located in Gujarat generated 99.96% of FY26 revenue
Final Thesis
profitable Tier-II auto-component manufacturer located within the Sanand automotive corridor in Gujarat. Generating 33.95% revenue and 60.87% net profit 3-year CAGRs, with restated FY26 ROCE of 26.89% and RoNW of 33.72%. Fresh IPO proceeds eliminate term borrowings on a net basis and fund a 44% capacity expansion via Plant II (COD January 2027). High cumulative cash conversion (CFO/PAT of 2x) confirms reported earnings are supported by operating cash flows.
Disclaimer
Data - Publicly available data and AI.
Not Invested currently but think of the same. Pl give your view.
SME stocks carry higher risks due to their smaller size, limited operating history, and relaxed regulatory requirements. This analysis is for educational purposes only and should not be considered as investment advice. Always conduct your own research or consult with sebi registered financial advisors before making investment decisions.