
JASCH IND margins in range of 11-12% vs MAYUR margins of 19-20%. Valuation wise JASCH is at 8.6 PE & 0.9 P/S while MAYUR is at 20 PE & 2.9 P/S
Does anybody know if this falls under the “Uber Cannibals” framework?
Jasch Industries is doing capex of 28 crores to meet the requirement of Kia. Already received 4 PVC / PU coated fabric machinery and erection of plant is under way. The company already started supplying to Kia as per the information submitted to BSE.
Kia produced around 2.55 lakh vehicles in FY23-24, if we assume each vehicle requires around 10 to 12 meters leather cloth and Kia gets its entire requirement from Jasch (earlier it was importing material and signed supply agreement with Jasch in Nov 2024), production of 2.5 lakh vehicles will require around 25 to 30 lakh meter of cloth which can fetch revenue of around 80 to 100 crores. Last year Jasch did a revenue of 170 crores. As high quality synthetic leather will be provided to Kia and crude oil price is down by ~20 percent, I am expecting margin expansion in coming quarters for the company.

1 Like
As per the annual report, Jasch Industries has developed new types of high quality coated fabric, particularly breathable ones which presents fresh opportunities in automotive sector. Jasch industries in the only significant manufacturer of PU synthetic leader. I think this is the one the company will produce for Kia.
I firmly believe that Jasch Industries is eating market share of Mayur Uniquoters in domestic market. If we look at sales of Mayur, it has not grown much over last 8 - 10 years and company’s PU plant is still under utilized and not selling much mainly due to tough competition in domestic market where as Jasch has continuously increased its capacity and delivered robust sales growth over last 8 years.

1 Like
Jasch Industries increased its production by ~2.5 times over last 8 years. This will further increase with ongoing capex of 28 crores, profit margins can also increase considering offering of better quality products to automotive sector.
Total Production in 2015-2016 = 36.62 lakh meters
Revenue = 83.21 crores

Total Production in 2023-2024 = 86.87 lakh meter i.e 18.96 (PU) + 67.91 (PVC)
Revenue = 172.31 crores

3 Likes
Jasch Industries reported strong March 2025 quarterly results. Revenue grew by 26% YoY and net profit by 232%. Higher PU leather contribution lead to significant increase in profit margins. With ongoing capex and launch of value added products, company is expected to perform even better in coming quarters.


The scrip is 44% up in 2 days, anyone still actively tracking the company? Seems like an infliction point.
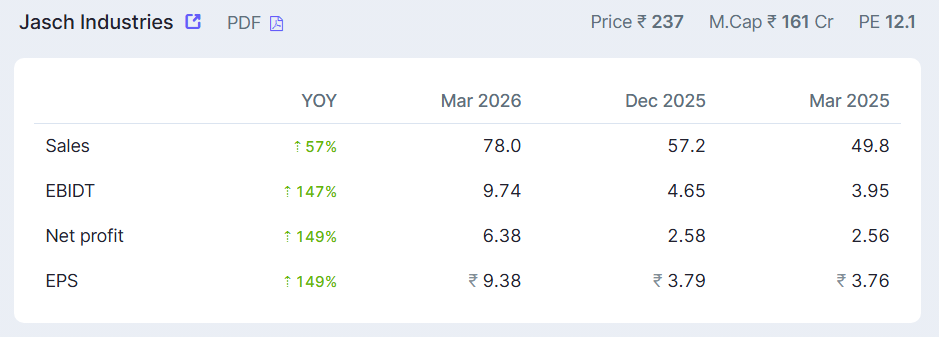
Very surprised to see Jasch shares not reacting to very positive set of numbers. It is in the same industry that of Mayur uniquoyers. But Mayur share is flying though Q4 result was due to a big addition from Forex gains. But Jasch case is more fundamental reflected by Q4 topline improvement. Another signal is company enhancing PU capacity which signals to a positive demand scenario. With UK FTA being implemented from July, company is ready to get further benefits.
But much information on the company is not available as the company is not doing con calls. So members tracking the company or having information can update latest position for awareness of fellow members.
3 Likes
It’s literally up 56% in a month, also most of the times the import duty is paid by the customers. So FTA will only cause sales growth, not margin, that also provided they can onboard new customers.