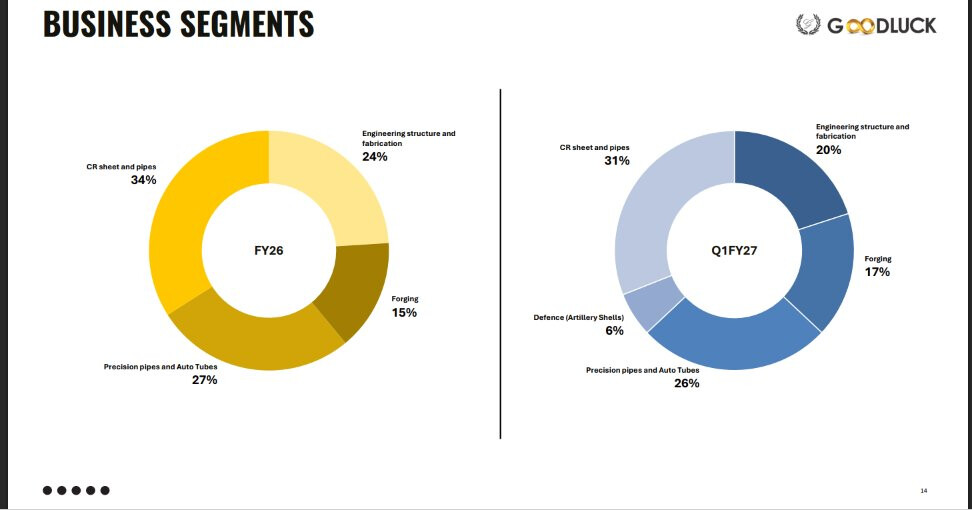
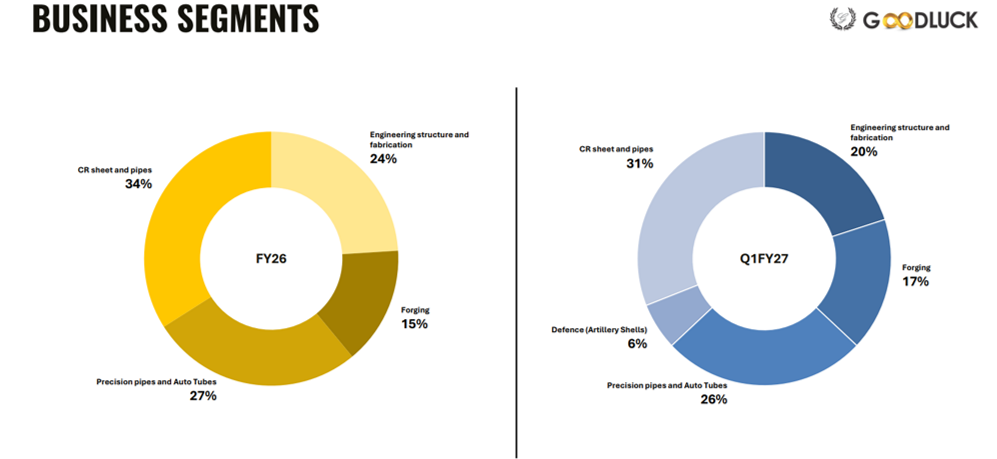
Goodluck India has around 6% of the total revenue in Q1FY27 for the Defence (Artillery Shells) segment which comes to around 77 crores which according to the management if it has did 30% EBITDA margin then constributed around 23.1 crores which is around 17% of the overall EBITDA IN Q1FY27
So Contribution of shells business,
Case 1
Revenue - 77 crores (6% of revenue in Q1FY27 on a higher base) EBITDA ,margin of 30%, EBITDA of around 23.1 crores (17% of the overall EBITDA).
Case 2
Revenue 77 crores, EBITDA margin of 35% (upper end), EBITDA around 26.95 crores (20% approximately)
Interestingly increasing mix will inch this to upwards, at this rate it will go to around 92.4 crores (23% of FY26 EBITDA, at 30% margin) at quarterly run rate of 77 crores for full year, and 108 crores (At 35% margin, 27% of FY26 EBITDA).
Export revenue grew by ~53% YoY and contributed ~29% of total revenue during the quarter.
Steel segment recorded total sales volume of 1,22,718 MT during Q1FY27, marking a YoY growth of 8.8%.
The Company maintained a robust annualised capacity utilisation rate of ~98%.
Export Order: Order secured for supply of approximately 14,500 MT of Transmission Line Structures valued at USD 13.6 million from an international entity (execution over 18 months as per approved drawings).
Goodluck Defence and Aerospace Limited, a subsidiary of the Company had decided to expand the Production Capacity to manufacture empty shells from 1,50,000 Nos. to 4,00,000 Nos. (Increasing by 2,50,000 Nos. empty shells production) with an investment to the tune of approx. Rs. 500 Crore finance through equity and debt is now expected to be completed by September 2027.
Board of Directors of Goodluck Defense and Aerospace Limited, a subsidiary of Goodluck India Limited, at its meeting held today, i.e., Thursday, 6th August, 2026, has, inter alia, considered and approved the further issue of equity shares to persons belonging to non-promoter category through preferential and private placement to raise fund up to a sum of Rs. 285 crores (Rupees Two Hundred Eighty-Five crores) approximately at a rate of Rs. 375 per share (including a premium of Rs. 365 per share).
Transmission line towers : This sector is likely to grow by 50% in next 2, 3 years.
Steel railway bridges, road bridges, road safety barriers: We see a 100% growth in this sector in coming 3, 4 years.
Oil and Gas sector Flanges : We see almost 60% growth in the next 3, 4 years in this particular sector.
DOM tubes, construction tubes, hydraulic tubes: Right now, we are doing almost INR1,000 crores plus turnover in this product, and we would like to double it in the coming 4, 5 years.
DEFENSE:
Company aims to achieve INR300 crores to INR350 crores target this year with a marked EBITDA of 30% to 35%.
Order pipeline is quite good. we have a good visibility. There is no doubt of orders for this product right now for the company.
IPO of the Defence segment : We hope that 18 months from today, it should be the time.
Qtr sales of 80 crores and with a EBITDA of 38%.
INR255 crores order has only about 50,000 shells, you will still have some capacity left for Fy '27, correct? Yes, yes. Orders in pipeline.
Earlier we had spoken about INR1,000 crores for the Defence subsidiary for '28, INR800 crores from shell and INR200 crores from aerospace? That number, definitely, it will go forward for 6 months to 9 months. By the time this project gets delayed. So that time will be added to our forecast what we had given earlier.
Basically, the world demand has converged to the tune of 90% to 95% demand has converted to 155. So yes, the machine is capable from producing from 120 to 155. But normally, the demand is for the 155.
As far as this Defence is concerned, we have a lot of inquiries enough for the next 5 years. However, as a policy, we do not announce till we have technically and commercially clear order. This is the reason we have announced only 50000-piece order. Others, we will let you know as the order comes as per our specification.
Holding company discount risk for Goodluck India if defense subsidiary IPO happens separately.
The growth for exports is coming both from the U.S. and Europe. The outlook is positive at the moment. But again, depends on international geopolitical situation, which is very much evolving on a daily basis.
We also hope that when this turmoil gets down, that margins should increase, but it all depends in the future because nobody can tell today. Today morning what is the place and what will happen – but margins should increase. You are very correct that if this turmoil settles down, so it will give a positive pressure to the results.
Sir, to the minority shareholders, it seems like all the initial struggle or the risks are taken on the balance sheet of Goodluck India, whereas all the upsides have been given to the external investors.
Top line should grow by 15% to 20%. So, we are maintaining our earlier guidance as well.
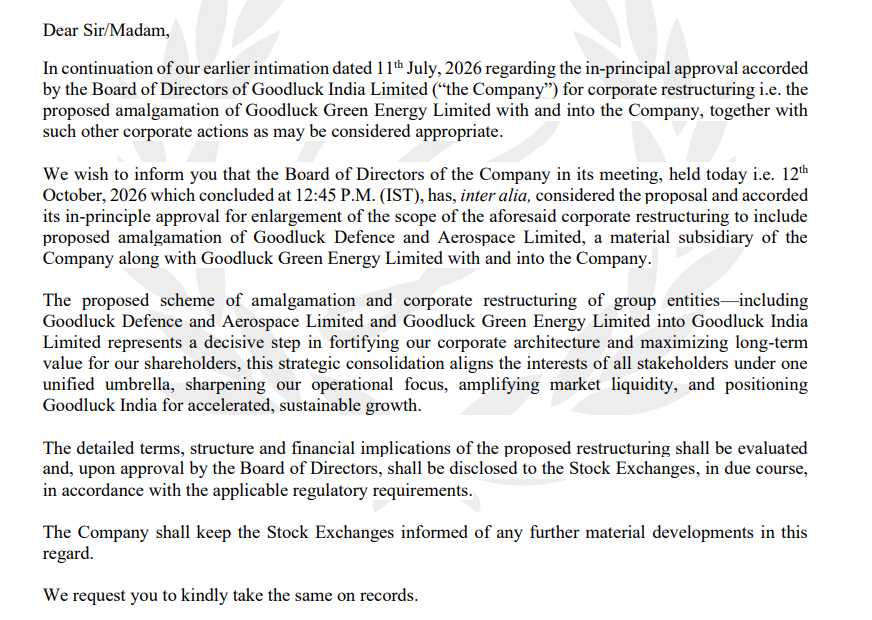
I will just like to clarify as many people have asked, with regards to our plan on Goodluck Defence, we will do what is beneficial for all our shareholders, give us some time to discuss with our Board and key stakeholders, and we will ensure what will work best for our all shareholders.
Operating performance by Goodluck in Q1 was perfection. But the management has clouded the sentiments around the company with their actions regarding capital decisions in the defense subsidiary.
Let’s hope the grilling by shareholders in concall makes them alter their course.
Opertionally, future looks bright for next 2-3 years for the company. Share price returns will come down to management actions around the defense subsidiary.
Results were good. What concerned me was how the management responsed then investores grilled on the “Goodluck defence.” Their standard response was that their advisors had recommended the same approach. I am sure the management understood what they were doing and the potential impact it could have on minority shareholders. I’m not sure, however, whether the grilling will actually make them reconsider or reverse their current course.
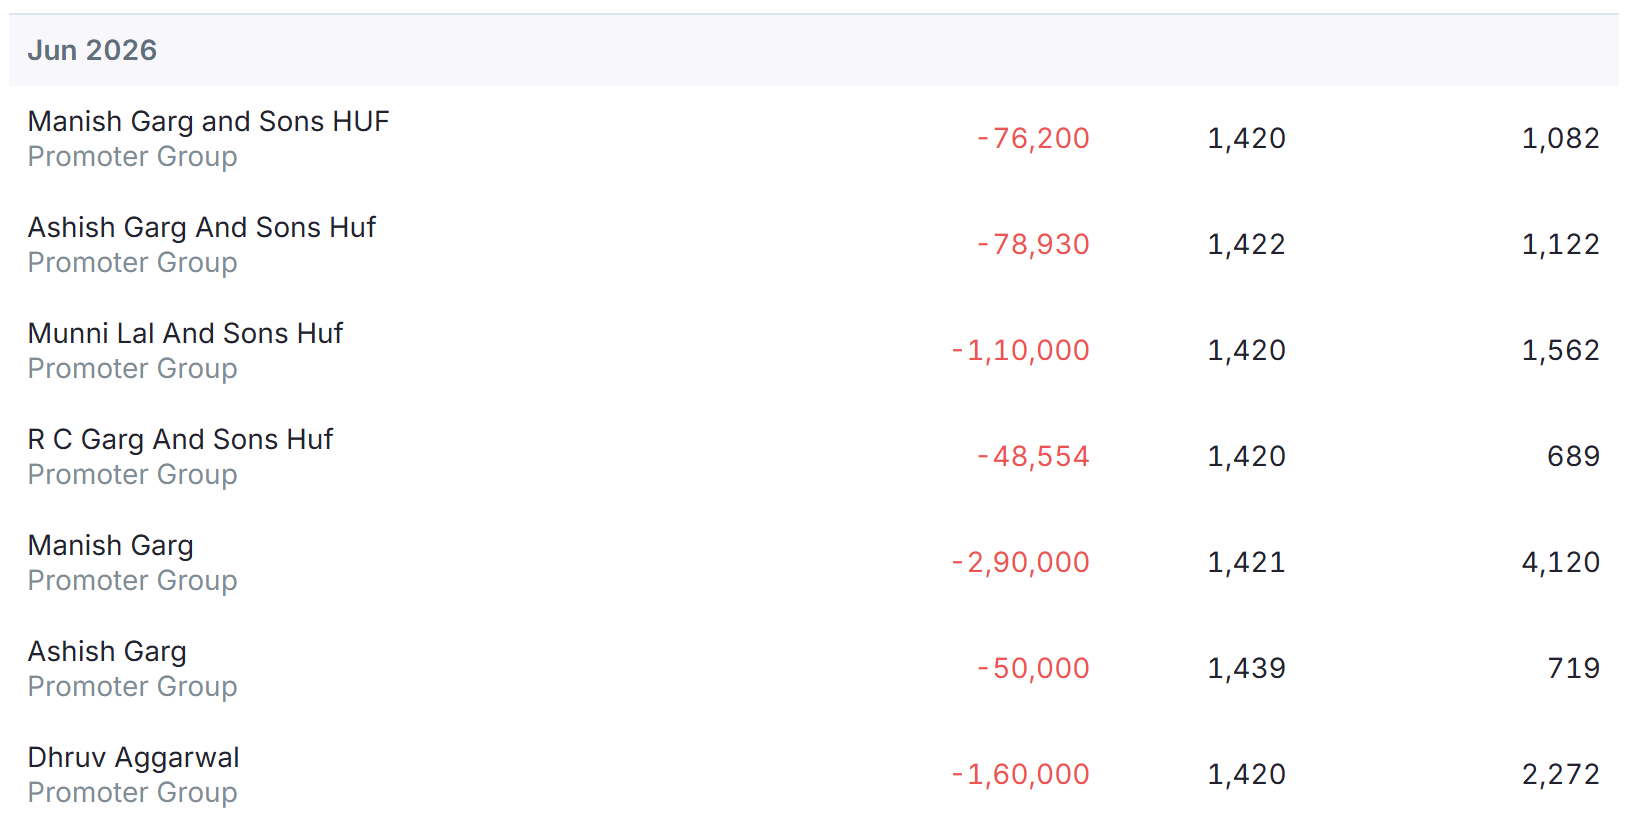
There was also good amount of promoter selling stake (close to 2.44%) in June 2026, which makes me wonder whether they already understood the potential impact.
ENGINEERING STRUCTURE & PRECISION FABRICATION: New areas of opportunity include:
Special formwork for elevated corridors
Special formwork for tunnel boring machines used in high-speed rail Station buildings for the high-speed bullet train
Super-critical bridges for the bullet train corridor
Smart city structures Car ports and solar parks — design engineering, supply and wire-drawn bridge architecture
FORGINGS: With a strategic shift towards stainless steel, duplex and alloy grades, and a single-piece forging capability now scaled to 14,000 kg, the segment is evolving from a component’s supplier into a trusted end-to-end forging solutions partner for its marquee customers.
Well positioned to benefit from anticipated recovery in global oil & gas infrastructure investment and repair demand, with the Company’s forging unit ready to service urgent supply requirements.
DEFENSE: The facility is licensed to manufacture artillery shells across all major calibres — 105mm, 120mm, 125mm, 130mm and 155mm — including variants such as HE M107, ERFB, ERFB BB and ERFB BT. That breadth matters: it positions the Company to serve multiple platforms and customer specifications from a single facility, rather than being locked into one calibre and one buyer.
Front Fork Tubes: Higher-margin line, guided EBITDA margin of 15–16%, broadening the automotive tube portfolio
GI Conduit Pipes: Targeted at the US export market — a high-profitability line (15-20% EBIDTA margin) supporting margin mix improvement
The global metal forging market was valued at USD 70.36 billion in 2025 and is projected to grow from USD 73.43 billion in 2026 to USD 103.35 billion by 2034, at a CAGR of 4.40%.
The Indian metal forging market was valued at approximately USD 4.2 billion in 2024 and is projected to grow at a CAGR of around 7% during 2025– 2034.
The global steel pipe market is on a steady growth path. According to Future Market Insights, the market was valued at USD 105.6 billion in 2025 and is projected to reach USD 109.7 billion in 2026, growing further to USD 160.9 billion by 2036 at a CAGR of 3.9%.
The India steel pipes and tubes market is estimated to be worth USD 18.06 billion and is expected to register a CAGR of 5.4% during the forecast period (2025-2031).
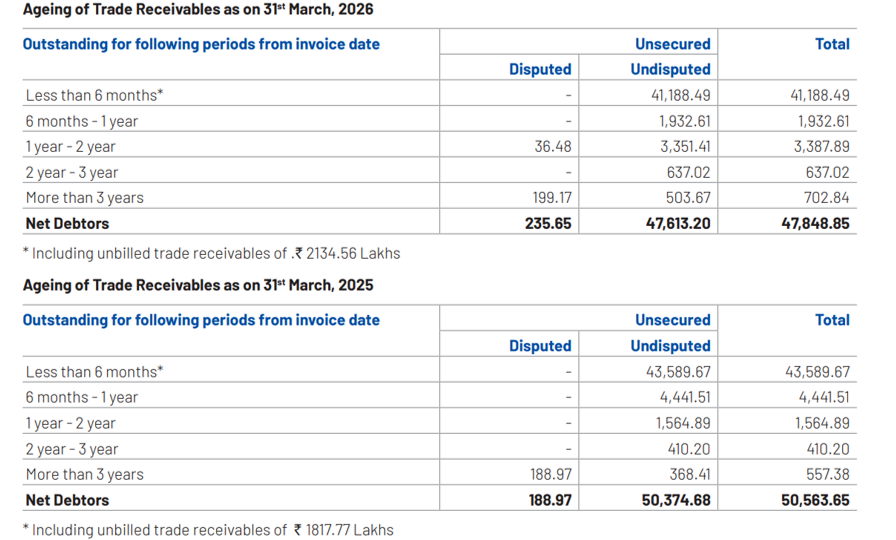
(Slight deterioration in ageing of trade receivables)
Advance received from customer – 103cr (vs 49.6cr in FY25)
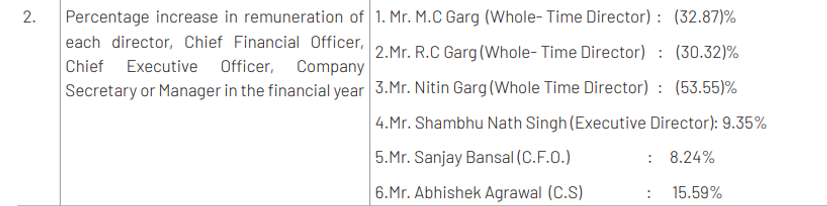
Remuneration, salaries and rent paid to promoters, relatives and related entities – 16.83cr (PAT – 183cr). 9.1% of PAT.
Previous year it was 27cr, 16.2% of PAT! So, a red flag has turned into a green flag.
PAT increase in FY26 is 17cr (166 to 183cr). 10cr is from promoter remuneration reduction. If EBITDA is considered, then 311 to 398, 10cr is from promoter remuneration reduction.
EBITDA growth is still healthy at 24.75% if we remove the 10cr reduction in promoter remuneration. Whereas PAT growth will be reduced to 4.2% (from 10%) if we remove the same.
Promoter and related persons taken big reduction in remuneration from goodluck india. But are they compensating it by alloting goodluck defense shares at cheap prices to known persons/ some kind of back of the hand deal?
This is just skeptical speculation from my side.
Further inputs from members would be greatly appreciated. Especially those who have contact with the management.