Will be a positive move if it goes through as it will ease there debt and working capital requirements
Also they bought scorpious for 135cr 2 years back so they will get get 2.5-3x returns and with Indian operations still with them
Will be a positive move if it goes through as it will ease there debt and working capital requirements
Also they bought scorpious for 135cr 2 years back so they will get get 2.5-3x returns and with Indian operations still with them
I think once they sign the agreement they need to execute the projects with in time line like 15-18 months as per agreements unless it’s delay with client like land clearance etc
So I think they will execute this order book of 7000cr at any cost with in this next 18 months and thats the reason they are aggressively deleveraging ( selling leasing assets and scorpious ) and building their working capital
Agree they have high debt, loose talk by promoter who misses guidance and many other issues and they why stock price is beaten down
But I am betting on recent changes they did like brining Shilpa from sterling and Wilson to head their solar EPC biz and this change is already working as they are getting bigger orders compared to competition
and we just need to track if these orders are converting to nos with proper execution
I feel Mr. Anmol is changing. While many were upset of the lack of guidance, it’s good that he just didn’t say something like 2000 cr will be achieved 3 months later or something. And their intent to deleverage is showing. The US operations for Scorpius makes sense given Gensol’s India focus. I never liked their EV leasing business and that should have been reason for me to exit but here I am … but now it seems that they are getting on the right track. And the Scorpius returns are pretty good too given what it was acquired for as you said.
Newbie to this site. And find the writeups thoughtful and interesting.
I have a question as I was trying to figure out what is a “PROPER” PE ratio of Gensol. These are what I found in different sites.
NSE - 28.71
Sceener - 25
ET - 21.19
MoneyControl - 20.99
BSE - 16.79
PE is one of the important factors in buy/sell decisions (among others). But, here there is almost 50% difference between low figure 16 and a high of 28. I understand about coming to a different number based on using TTM vs latest quarter x 4 vs last full FY.
But, if someone who is used to seeing BSE site and basing their opinion might be tempted as PE is mouth-watering 16 for a company having past performance of 52% CAGR in profit over 5 years. Whereas if I consider its PE to be 28, it might be only modestly interesting.
Thoughts?
The CMP is Rs.569 on NSE 25-Feb-2025 with slight difference in other sites.
(my first post on ValuePickr)
With this company, it appears “A new announcement a day to keep bears away !”.
Only a curious bystander. No investment.
Due to Rating downgrade, it is in lower circuit. Rating downgrade is mainly due to not paying properly overdues by Gensol. Source: Disclosure on Exchanges
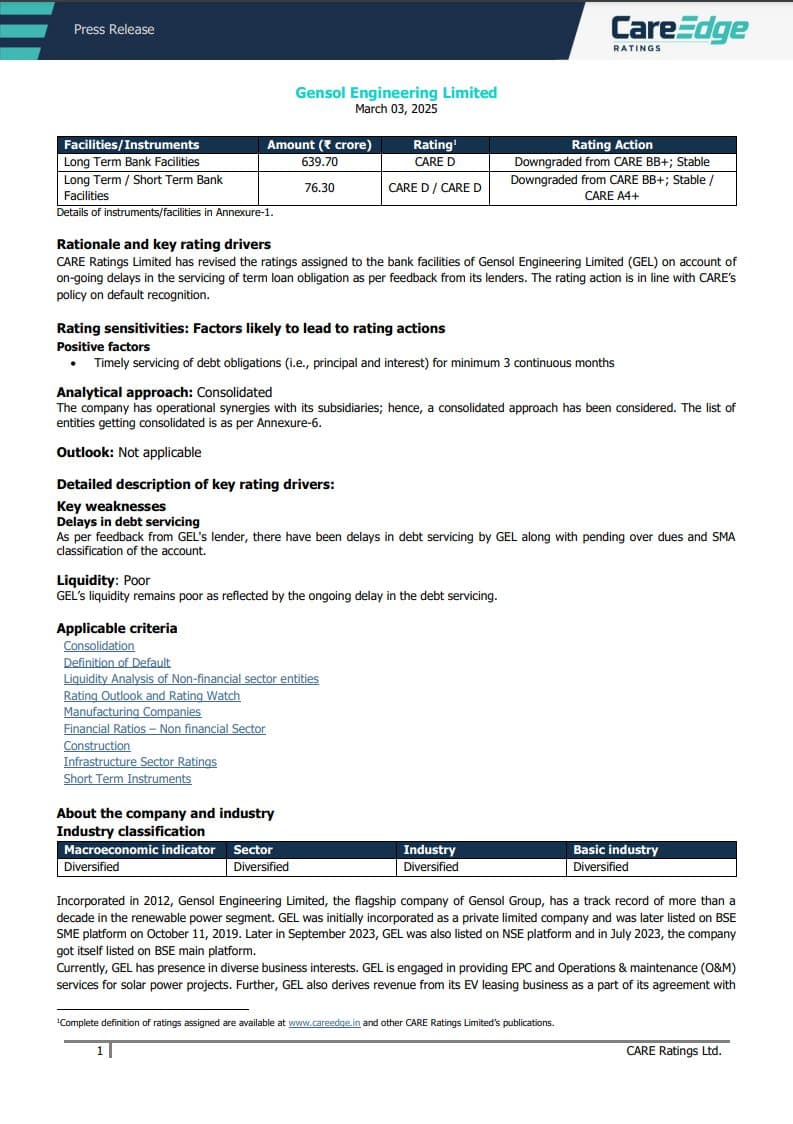
CARE Ratings downgraded Gensol Engineering Limited’s (GEL) credit rating to CARE D, meaning “default”, because the company has not been able to make payments on time for its loans.
What I understand is:
a. * Loan Payment Delays: The company failed to pay its term loan obligations as reported by its lenders.
b. * Liquidity Issues: Gensol is facing cash flow problems, making it difficult to meet debt commitments.
c. * SMA Classification: The company’s bank account has been categorized under “Special Mention Accounts” (SMA), which means it has missed payments and is at risk of becoming a non-performing asset (NPA).
d. * A CARE D rating indicates that lenders and investors may see Gensol as a risky borrower. * The company may face difficulties in raising new loans or investments at favorable terms.
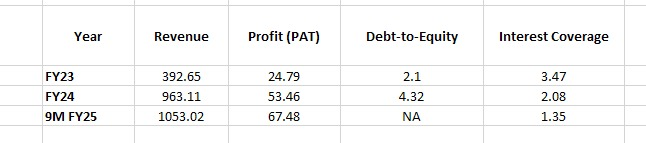
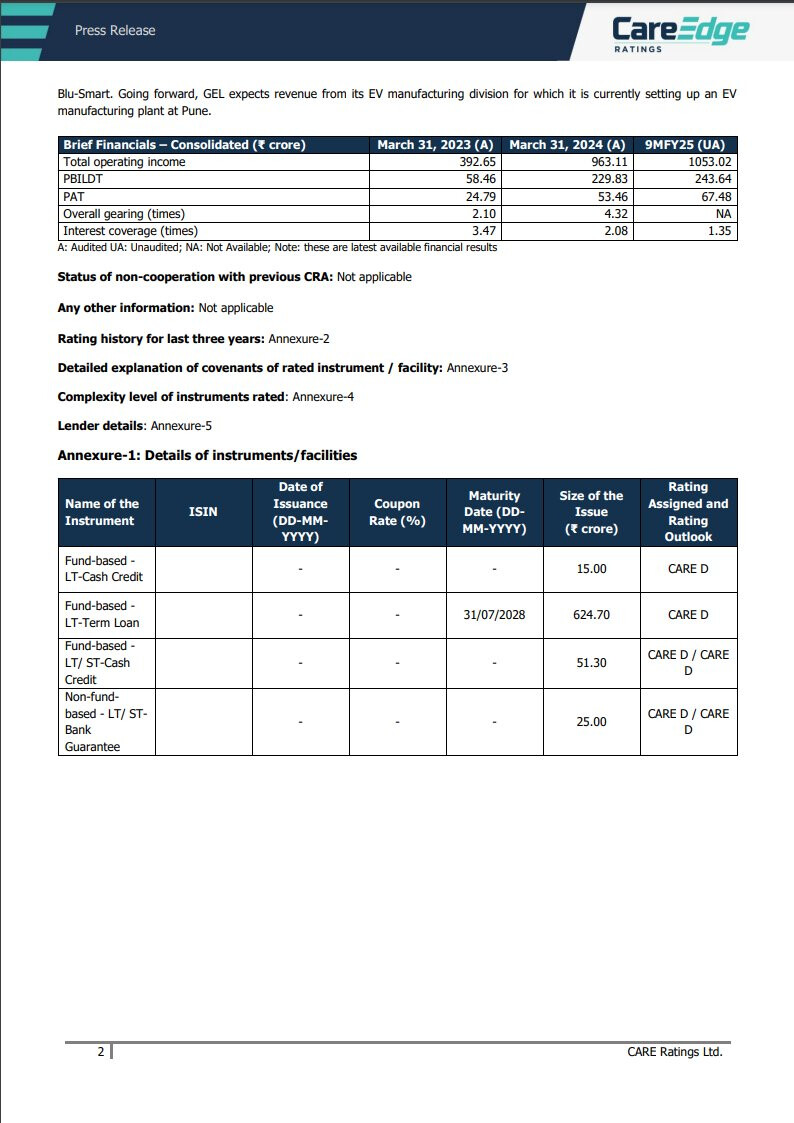
Debt-to-equity has doubled (2.1x to 4.32x), meaning the company has taken on more debt.
Interest coverage ratio has dropped (3.47 to 1.35), indicating lower ability to pay interest.
Now the margin calls wll begin; the fall going forward can be very severe as brokers will offload without looking at the price. Don’t catch a falling knife…
Looking at today’s sell orders.
Seems brokers / lenders are triggering the sell orders.
It’s a painful journey for the ones who have had already invested.
Looking at the downgrade by CARE to ‘default’ rating, questions will arise of the firm continuing to be a ‘going concern’. Company is not paying its interests on time, has huge cash flow/liquidly issues, debt to equity is very high and the promoter has pledged shares. Looks like a single-digit penny stock soon.
Hope you are not holding the bag on this. One should not be very exuberant on such firms
Todays volume on both exchanges is just 10 lacs; shares pledged by promoters are upwards of 1.7cr I believe. Long way to go…
Not all lenders would rush to offload.
If jaggi has provided some additional collateral with some lenders, they will back off from selling.
Holding heavy losses, there was always a concern of pledging and high debt.
But somehow got sucked in projecting future earning for couple of years and the valuations.
But lesson: there is no value at any valuation for the some scripts.
Disclosure : holding and looking to get out when exit is there, No recommendation
Yes, I think this is on its way to be a penny stock. If invested, get out when you find a buyer at some price. This is likely to hit a series of lower circuits to a penny stock
Feel sad for those who are holding the bag on this.
This is what I wrote about this stock last year when hype around it was at an all time high. This should be another lesson to retail investors to be suspicious of all good stories that small caps companies tell their investors whether their big order book, capex expansion or rosy prospects.
There were enough hint in the Q3 concall which lead me to believe that there was no cash left.
Booking loss in this time was relatively easy 
Thought of mentioning it here but not wanted to spread anything negative without knowing the fact 
Very similar thought process. The writing was on the wall. Booking small losses is key to long term investing success.
https://x.com/vineetjain1101/status/1896883278092616048?t=r3kjIT1jOBw6xrlRjXIIGw&s=19
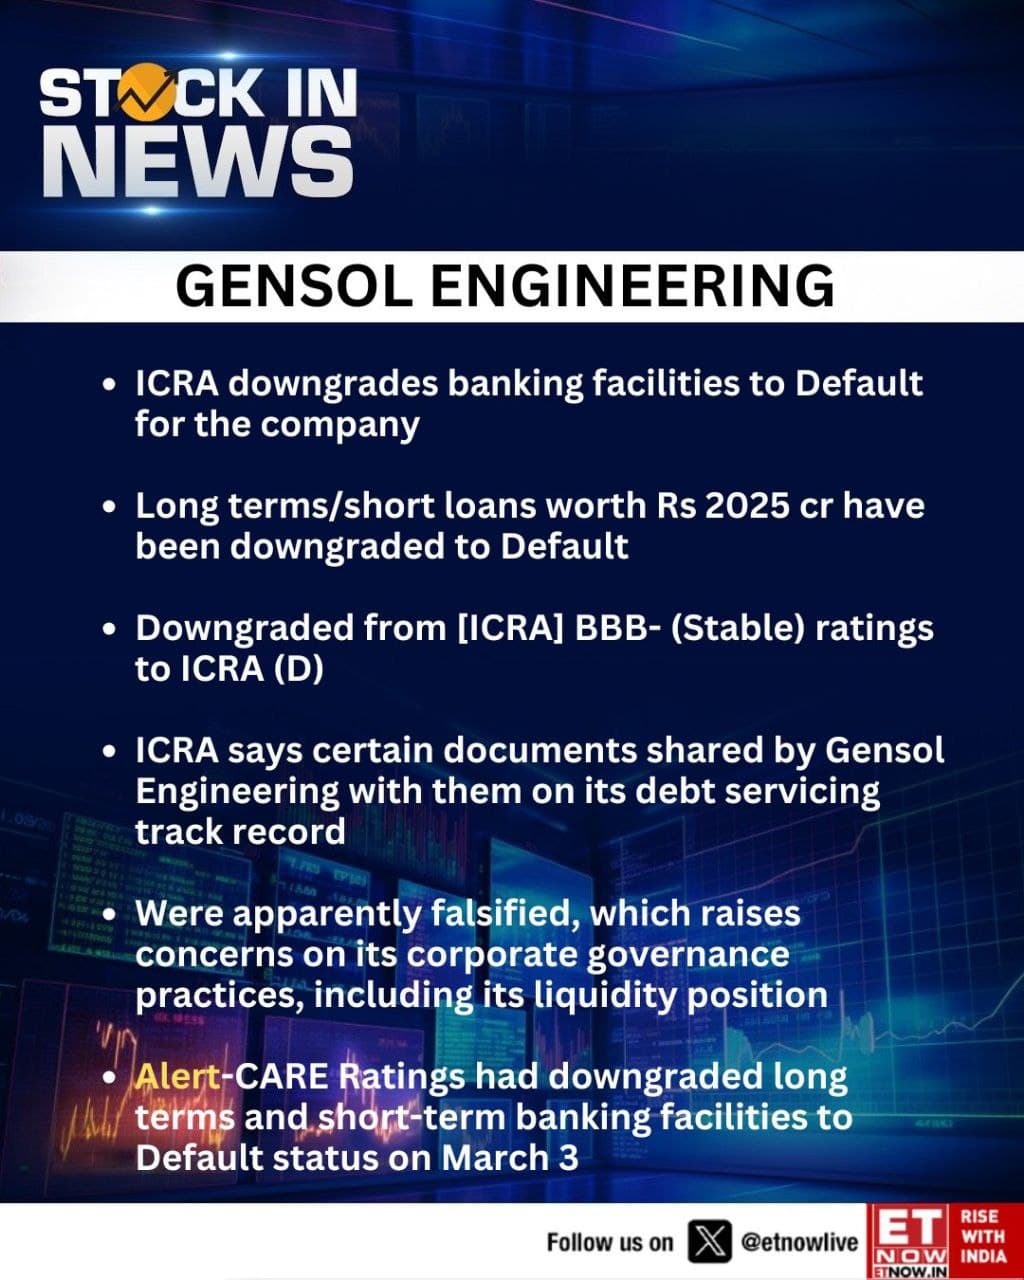
Debt Servicing Record is falsified. This means it is not a case of hubris and too much ambition. It is a clear case of fraud.
Note: Never even considered investment in this one.
I mentioned last year amid the hype surrounding the stock that biggest flag I saw in Gensol was heavy debt raising against their stocks. The deep corrections in market over last months may have also contributed to what is unfolding. When management doesn’t have money to pay off their debt bad things happen.
I think the biggest mistake gensol did was venturing into the ev vehicle manufacturing (new business ) with such high debts.
They could have sailed through easily with their epc business and market would also have rewarded them with earning multiple premiums solar companies are enjoying.
It’s quite sad to see such promising companies facing financial ruin.