9657ece5-7469-4d60-8ac2-f732e7b44713.pdf (358.7 KB)
GEL denied fake documents claim of icea
Has the asset divestment been completed or they are just planning to do it? If they haven’t then they need to find buyers. Merely saying that we have initiated the process does not bring in cash to repay debt. You need the actual sale and we know that its tough. Their statements cant be considered as reliable. In the past as well they over promised and under delivered.
They have signed an agreement with Refex on the sale of 2,997 cars for 315 Cr. They also signed a term sheet for the sale of Solar Tracker subsidiary (without Solar IP rights for India, which was good) for 350 Cr. (to be paid to Gensol in two tranches by March 2026). I am unsure if they have sufficient Working Capital to execute the huge amount of EPC orderbook in next 18 months or if they will find short term loan facilities for working capital requirements. I believe if they are able to execute the projects well this year and the divestments go as planned, they would be back on track again. Depends if they currently have / would find sufficient liquidity for the EPC executions.
Disc.:
Invested, given the growth prospects and the issue only seems short term liquidity, which I think they should get given there huge order book. No existing lender would want to unnecessarily force liquidation, if in the worst case scenario the debt can still be restructured so the some repayments are formally postponed by the lenders i.e. government owned power development financial institutions aiming to promote and support renewable energy development (majorly IREDA and PFC). Nervously hoping for the best…
6 Likes
To my best of knowledge where i work as client of solar epc contractors…having done small plants.
- Solar EPC is ~10% margin.(higher for goverment/lower for private)
- Working capital management is key.
- Execution speed is the expertise.
- Payments often delay ( hence point 2)
- Competition is intense. All solar EPC have good orders.
- Solar EPC is no moat biz.(hence point 3)
Its human to be hopeful on investments ( all kind of investments monetary as well as non monetary)
All things aside, a default is a default, doesnt matter what caused it.
In my short experience with direct equity i feel, short term, the capital deterioration shall persist untill they raise money and payback. ( if there is a chance to avoid further deterioration why not take it ?)
I am mostly good at selling when stock hits much lower levels and losses.
D- No investments.
3 Likes
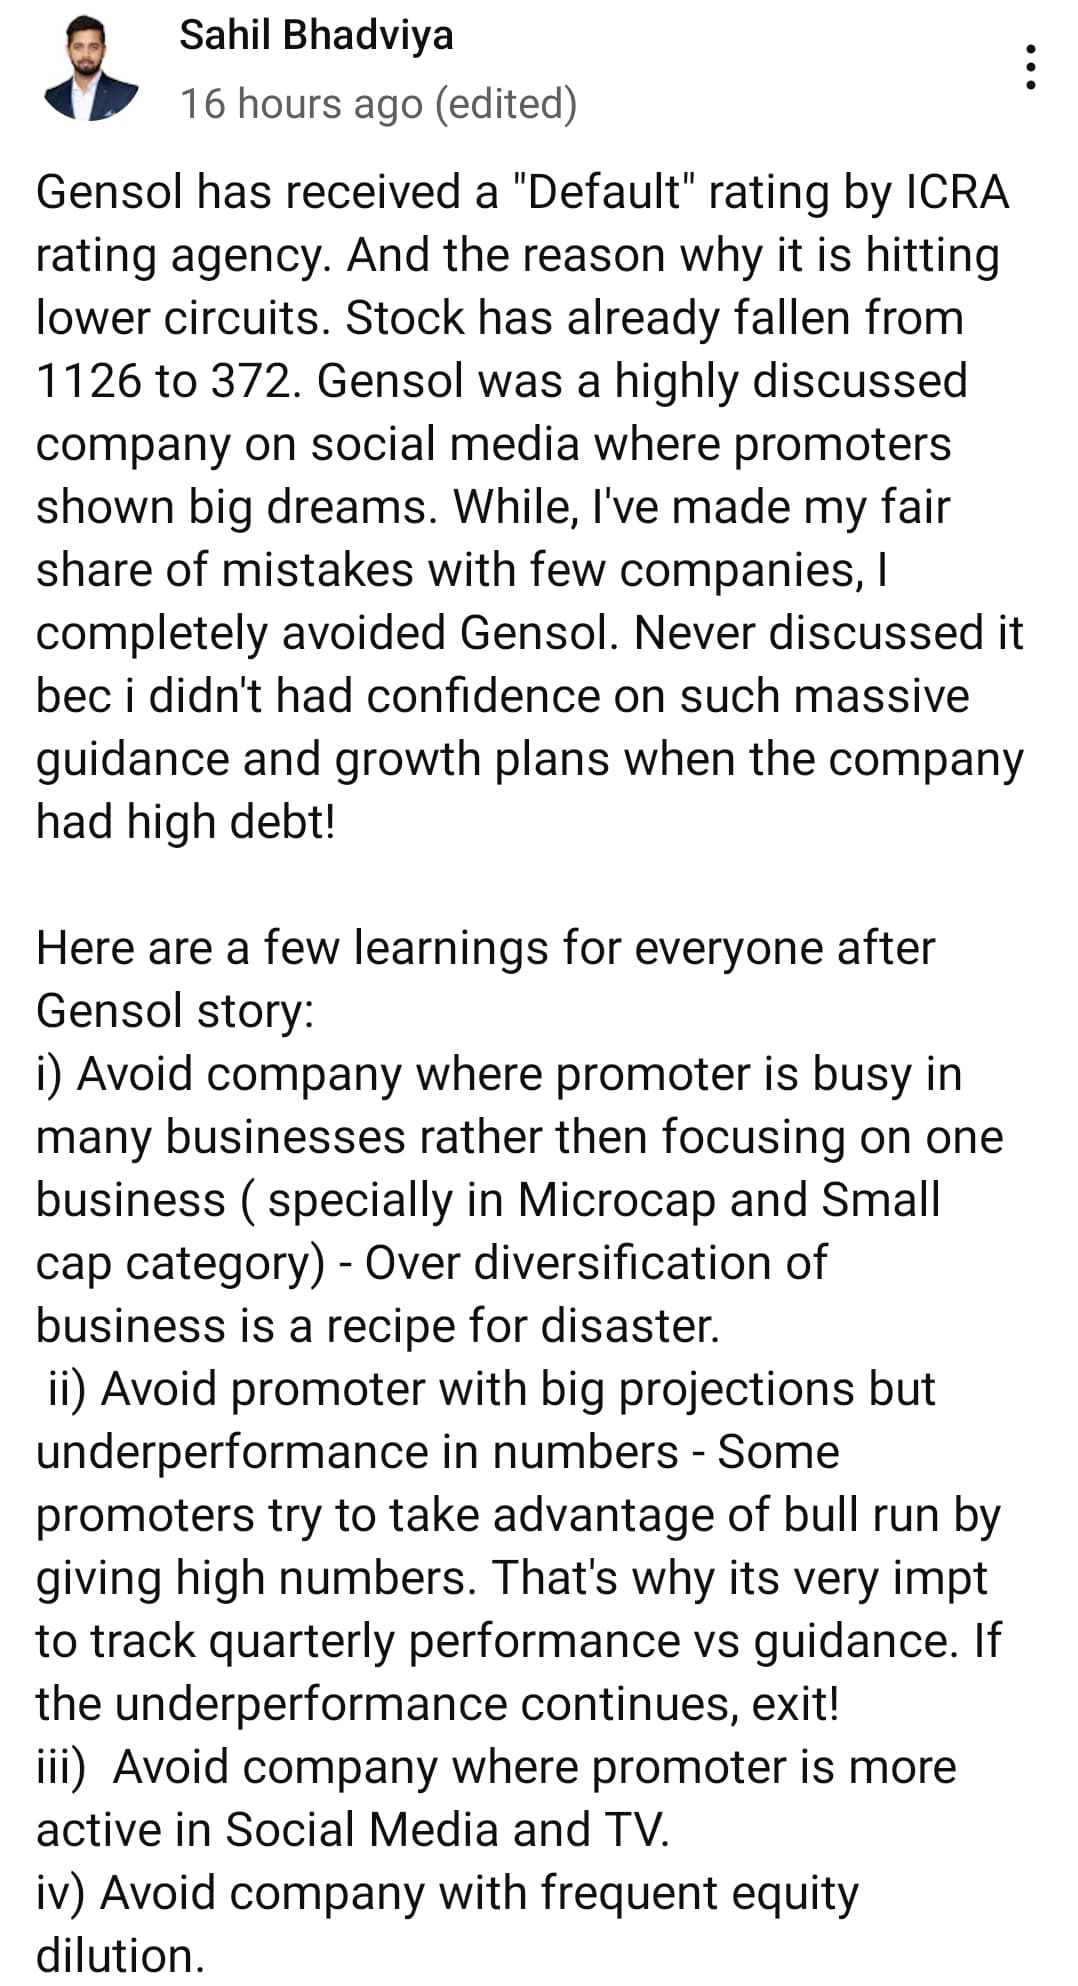
Good points on when to be cautious about companies making huge promises without a decent medium/long term track record.
Personally was always suspicious about this company and still feel there are a lot of skeletons to tumble out from this one.
For now they have denied the falsification claims officially but personally I’m not convinced.
Disclosure: not invested
5 Likes
Gensol engineering MD shares his thoughts on recent developments
1 Like
Gensol Engineering | Management Interview
Gensol Engineering after rating agencies, CARE and ICRA downgrade the company to default grade.
- Did not fabricate documents
- A default on debt payments, but he hopes for a rating upgrade in 3 months.
- Promoters will soon buy shares from the market or convert warrants.

The next one to lookout might be IREDA. I had shared some findings between the sketchy loan disbursement activity of IREDA to gensol some time back here .
4 Likes
buy additional shares with what money.
They already are pledged more than 60%. If promoter has cash, do a prefrential, put in money and ensure no default.
Building Castles in the air for last 5 years. Hoping for next set of retail chumps.
7 Likes
‘The more things change, the more they remain the same.’
Even in the case of Gensol ratings was only downgraded after payment defaults
2 Likes
I have got a question. Correct me if wrong. As per my understanding, Gensol supplies EVs to BluSmart. BluSmart needs to show some profitability for a fund raise. This would be possible if Gensol lowers lease prices. This means Gensol has to lose something for BluSmart to gain something. So both cannot win at the same time. Now the question is - Will it be a case where BluSmart winning gives more gains to promoters even if Gensol loses ? I am just trying to figure out the inclination of promoters and if there is any conflict of interest. Can someone explain?
1 Like
All the typical ingredients: invoking Paternal Roots,EBITDA earnings and one thing I fail to understand why would refex pay 300 crs for 2-3 year old fleet of mostly Tata Tigor cars(3000*6=180crs max) 3-4 year car is depreciated by 50. Best part was,he says more IPOs would come.
3 Likes
Even I don’t understand that calculation.
How can 2997 cars be sold at 300 cr.
Value per car comes more than 10 lacs in that case?
1 Like
The life cycle of a car in this business is 5 year. I remember hearing this from blusmart owner itself. The depreciation can only go higher.
They are not selling the cars at full price, they are simply transferring the loan obligation of those vehicles to refex. I believe refex will take care of the monthly EMIs from here on of that 300cr loan amount, and gets to own that car fleet. Gensol won’t get any cash out of this deal, only that the EMI payment for this particular 300Cr. Loan would stop, reducing their monthly debt servicing obligation by about 20 odd crores.
2 Likes
Between 4:25 to 4:35 in this interview, he is agreeing that rating agency received the falsified document, but committee is formed only to check who shared the falsified document 
So net net, there is an issue with the business, if not financial mismanagement, then issue of mismanagement as all these documents should have been vetted by management before sending to rating agency.
2 Likes
Meaning no cash would come into the books of gensol,only interest savings on diminishing basis for the duration of the car loan. It’s being presented by the management as if 300 crs would come into the books. Thanks for the explanation.
2 Likes
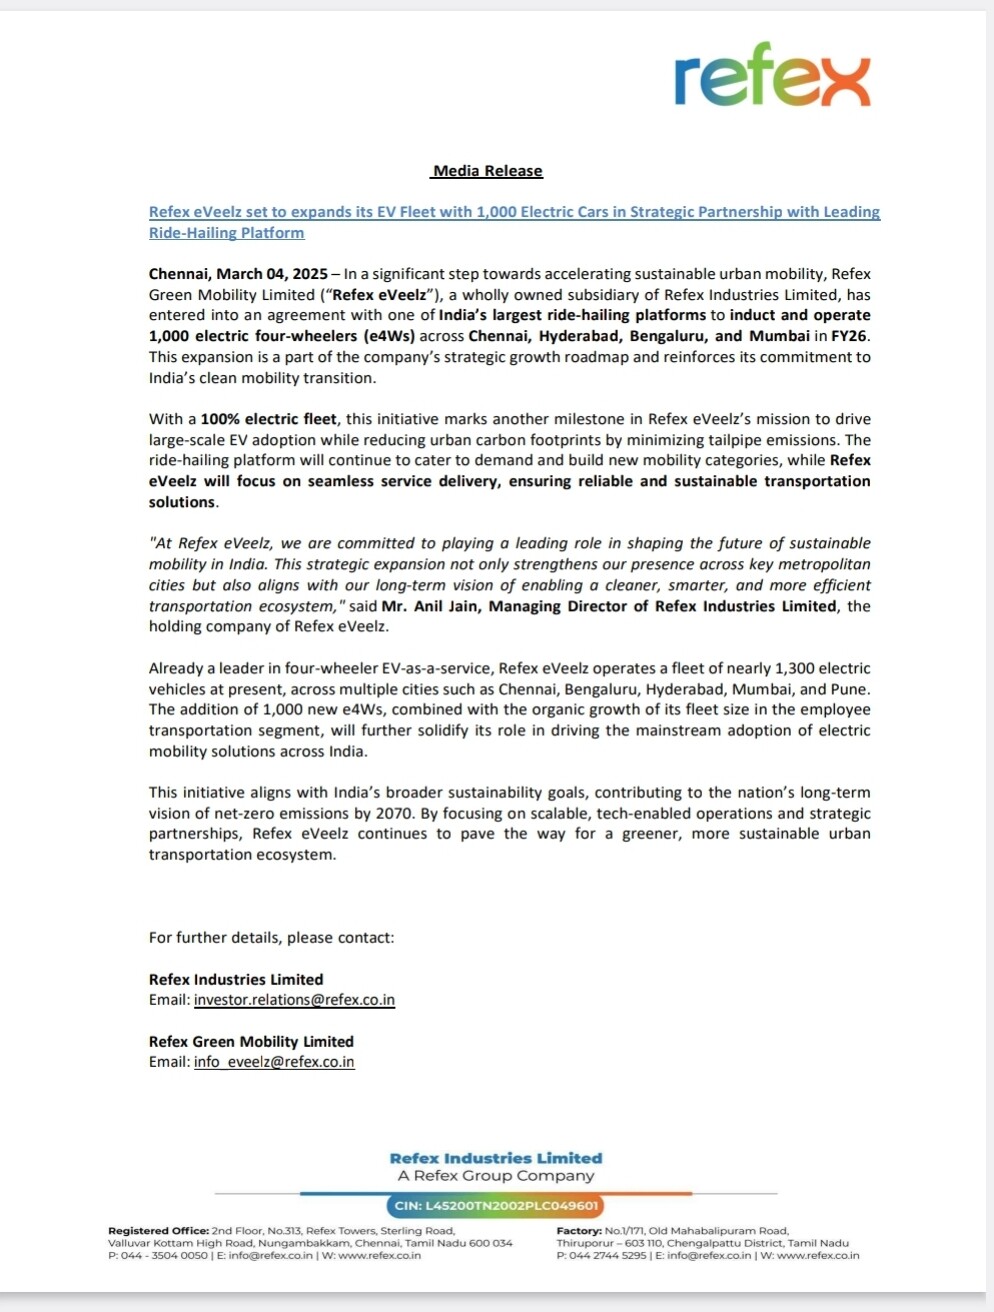
I don’t think refex fits your definition. They’re seemingly very excited about this EV Leasing thing that they have expanded their fleet target to 1000 vehicles. But they don’t seem very comfortable in saying publically that they’re collaborating with BluSmart, maybe they don’t want their name to get associated with BluSmart in the current scenario, but it is really amusing as to why would they have such a big commitment of 1,000 vehicles with BluSmart, when they even fear associating with them in public.
1 Like
Promoters have pledged more than 80% and most of the pledging was done in last 4-5 months. Next victim will be banks/NBFC that gave loan to them. Won’t buy a single share till promoter buys it as claimed in the interview. Poor retail…Don’t know who is buying and why they are buying
1 Like
IREDA loan was for purchase of EVs, they are selling 2997 vehicles to Refex at 315 Crores & I think they own 8300 such EVs.