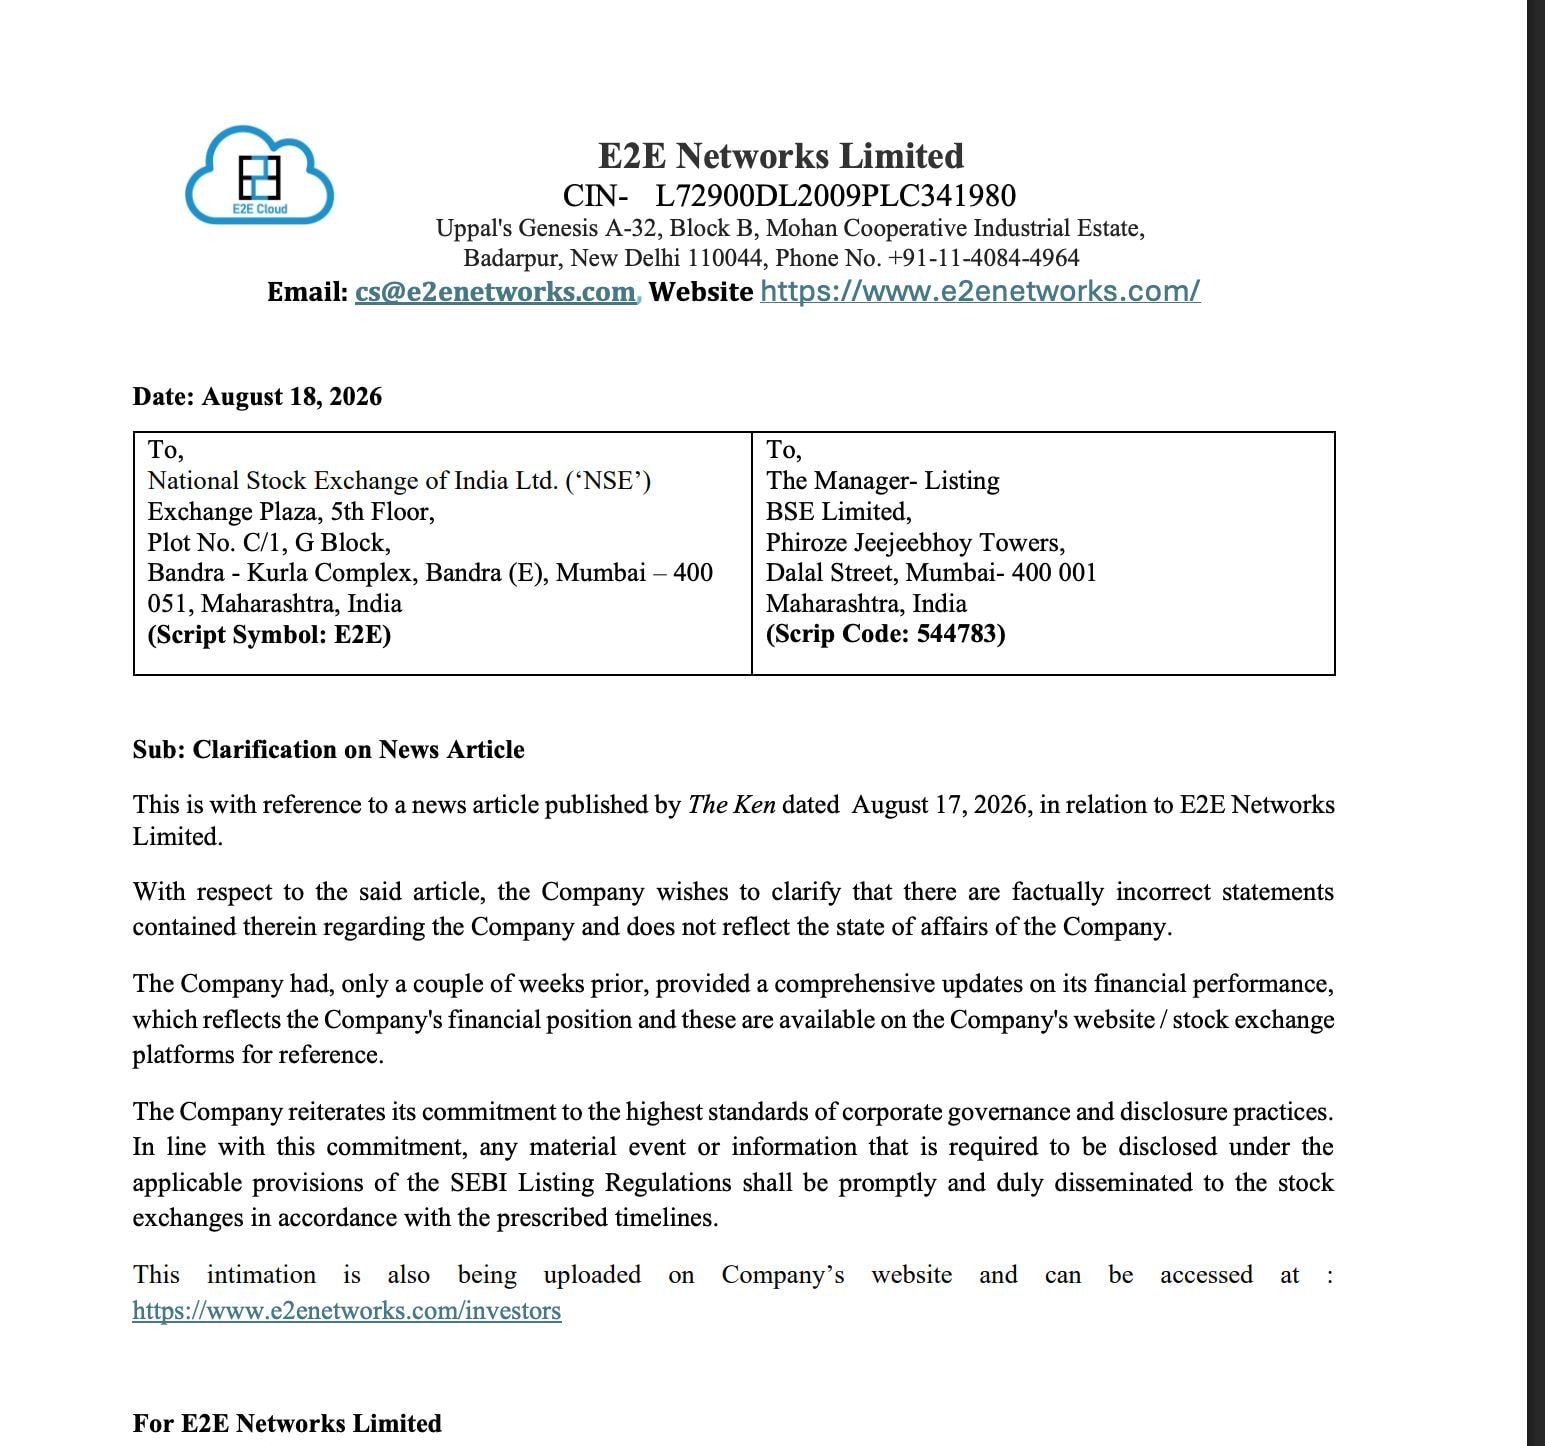
It’s a plain and simple gibberish hit piece, the best takeaway from the posting is the OP not renewing their subscription for Ken. 
And that E2E is worthy enough for a malicious media article.
Disc: invested, biggest holding
It’s a plain and simple gibberish hit piece, the best takeaway from the posting is the OP not renewing their subscription for Ken.
And that E2E is worthy enough for a malicious media article.
Disc: invested, biggest holding
With my limited understanding, the twin IT giants of L&T - LTM & Engineering IT LTTS both have been increasingly focussing on the orchestration layer, AI platforms and AI application layer. It is what they do and where they will play much bigger roles…. curious if L&T did target E2E for this layer, why not use its own companies which already working on it and growing in it? Is the Orchestration / application layer of E2E better or more advanced compared to LTI & LTTS ? Thanks!
"The financial engineering rests on a single reclassification. Graphics processing units (GPUs) have always been treated as equipment that loses value quickly, superseded whenever a faster generation arrives.
Nvidia is effectively asking lenders to treat them instead as long-lived infrastructure, closer to a toll road or a power plant, that can be borrowed against for years.
“These are revenue-generating assets now,” Huang said, describing them as productive, long-lived and transferable between customers."
This is what the biggest players have all agreed upon as the holy grail.
I am invested in Nebius also, tracking Coreweave who have their 2020 dated A100s firmly booked till 2029 at least. And prices are rising just like the hike E2E did recently. Actually every AI cloud platform wants to keep the capacity balance between firm and future commitments, eyeing the price rise trend.
Disc: invested, AI trade in dollars and rupees makes 33% of folio.
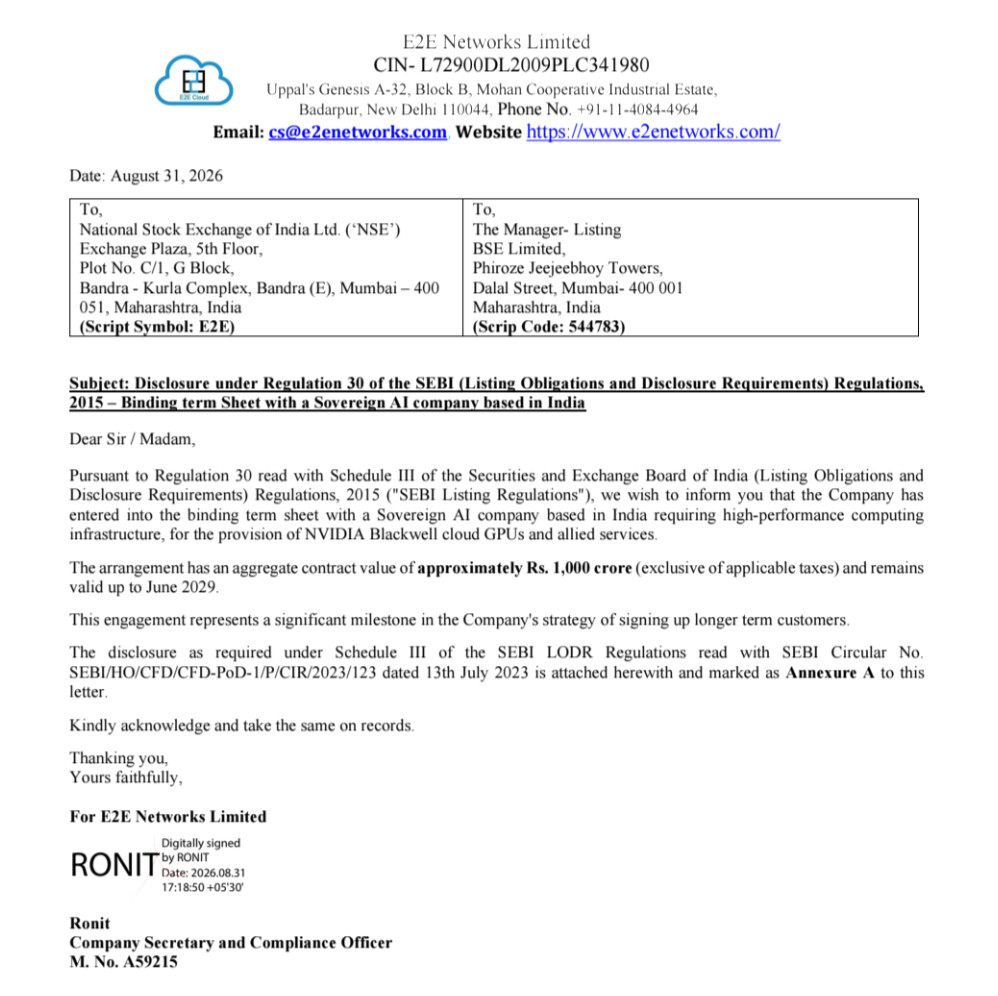
1500 Cr fundraise this month. Means additional 3072 GPUs procurement in plan in short term/ this financial year.. huge runway…Can this make 1200 cr ebitda for fy28?
How much creeping stake L&T going to increase is the question. From recent commentary of E2E management and L&T actions, looks like they are not as euphoric as they were 2 years ago. Lets see.
E2e networks annual report is out. There is a clear emphasis on being integrated AI factory rather than an IaaS player renting out GPUs.
Summary of strategic priorities-
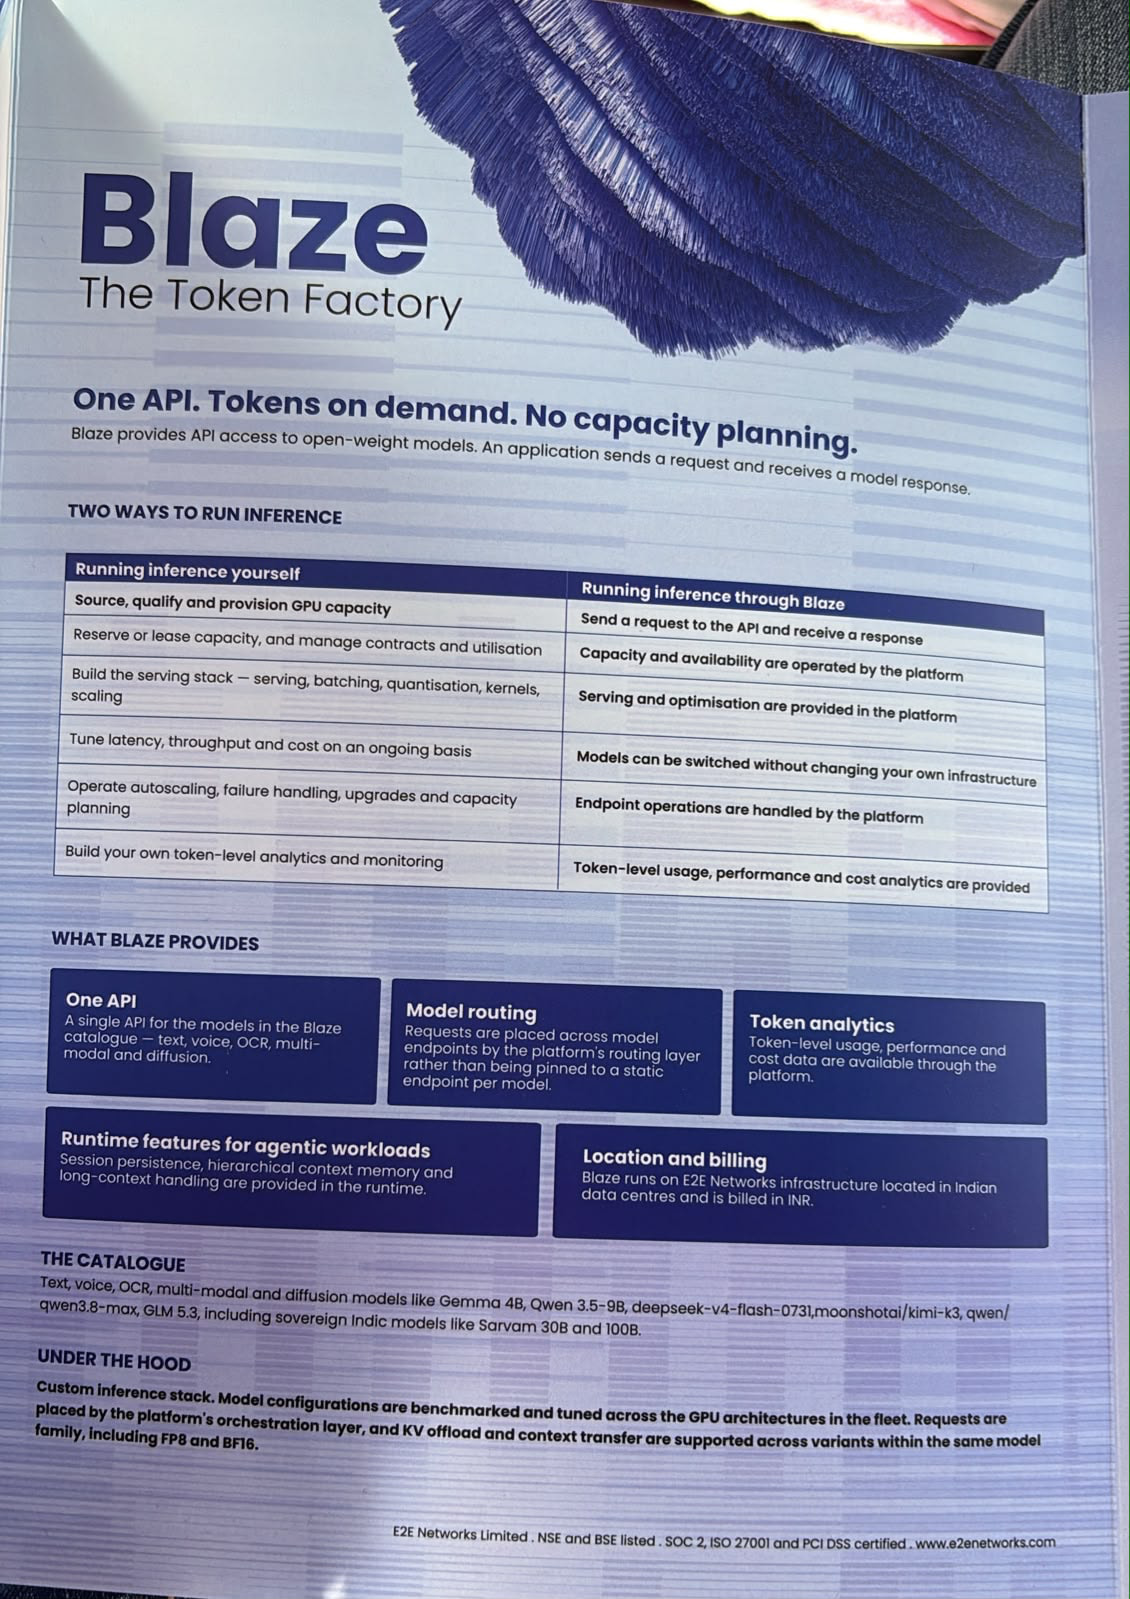
As an aside, company has shared this ‘Build Guide’ intended for BFSI customers. While it appears to be a marketing document, it gives some sense on how E2E is positioning itself and its value proposition to customers.
There’s one question with which you might not agree, how much of your post writing is done by AI and how much is because your own reading.
No offense, just asking for the sake my own decision making  .
Read entire annual report myself. Could make out emphasis on being full stack player vs being just infra provider, this did not need any AI assistance. Took AI help in summarizing strategic priorities, though this is based on my own reading and is not AI copy paste.
Disclosure: Invested and hence may be biased. please do own due diligence.
Hai do u get to rs1200cr pat number for fy28?
Would b helpful to the community of u can share calculations and some notes please
Sorry..I meant 1200 cr ebitda not pat. Corrected now..
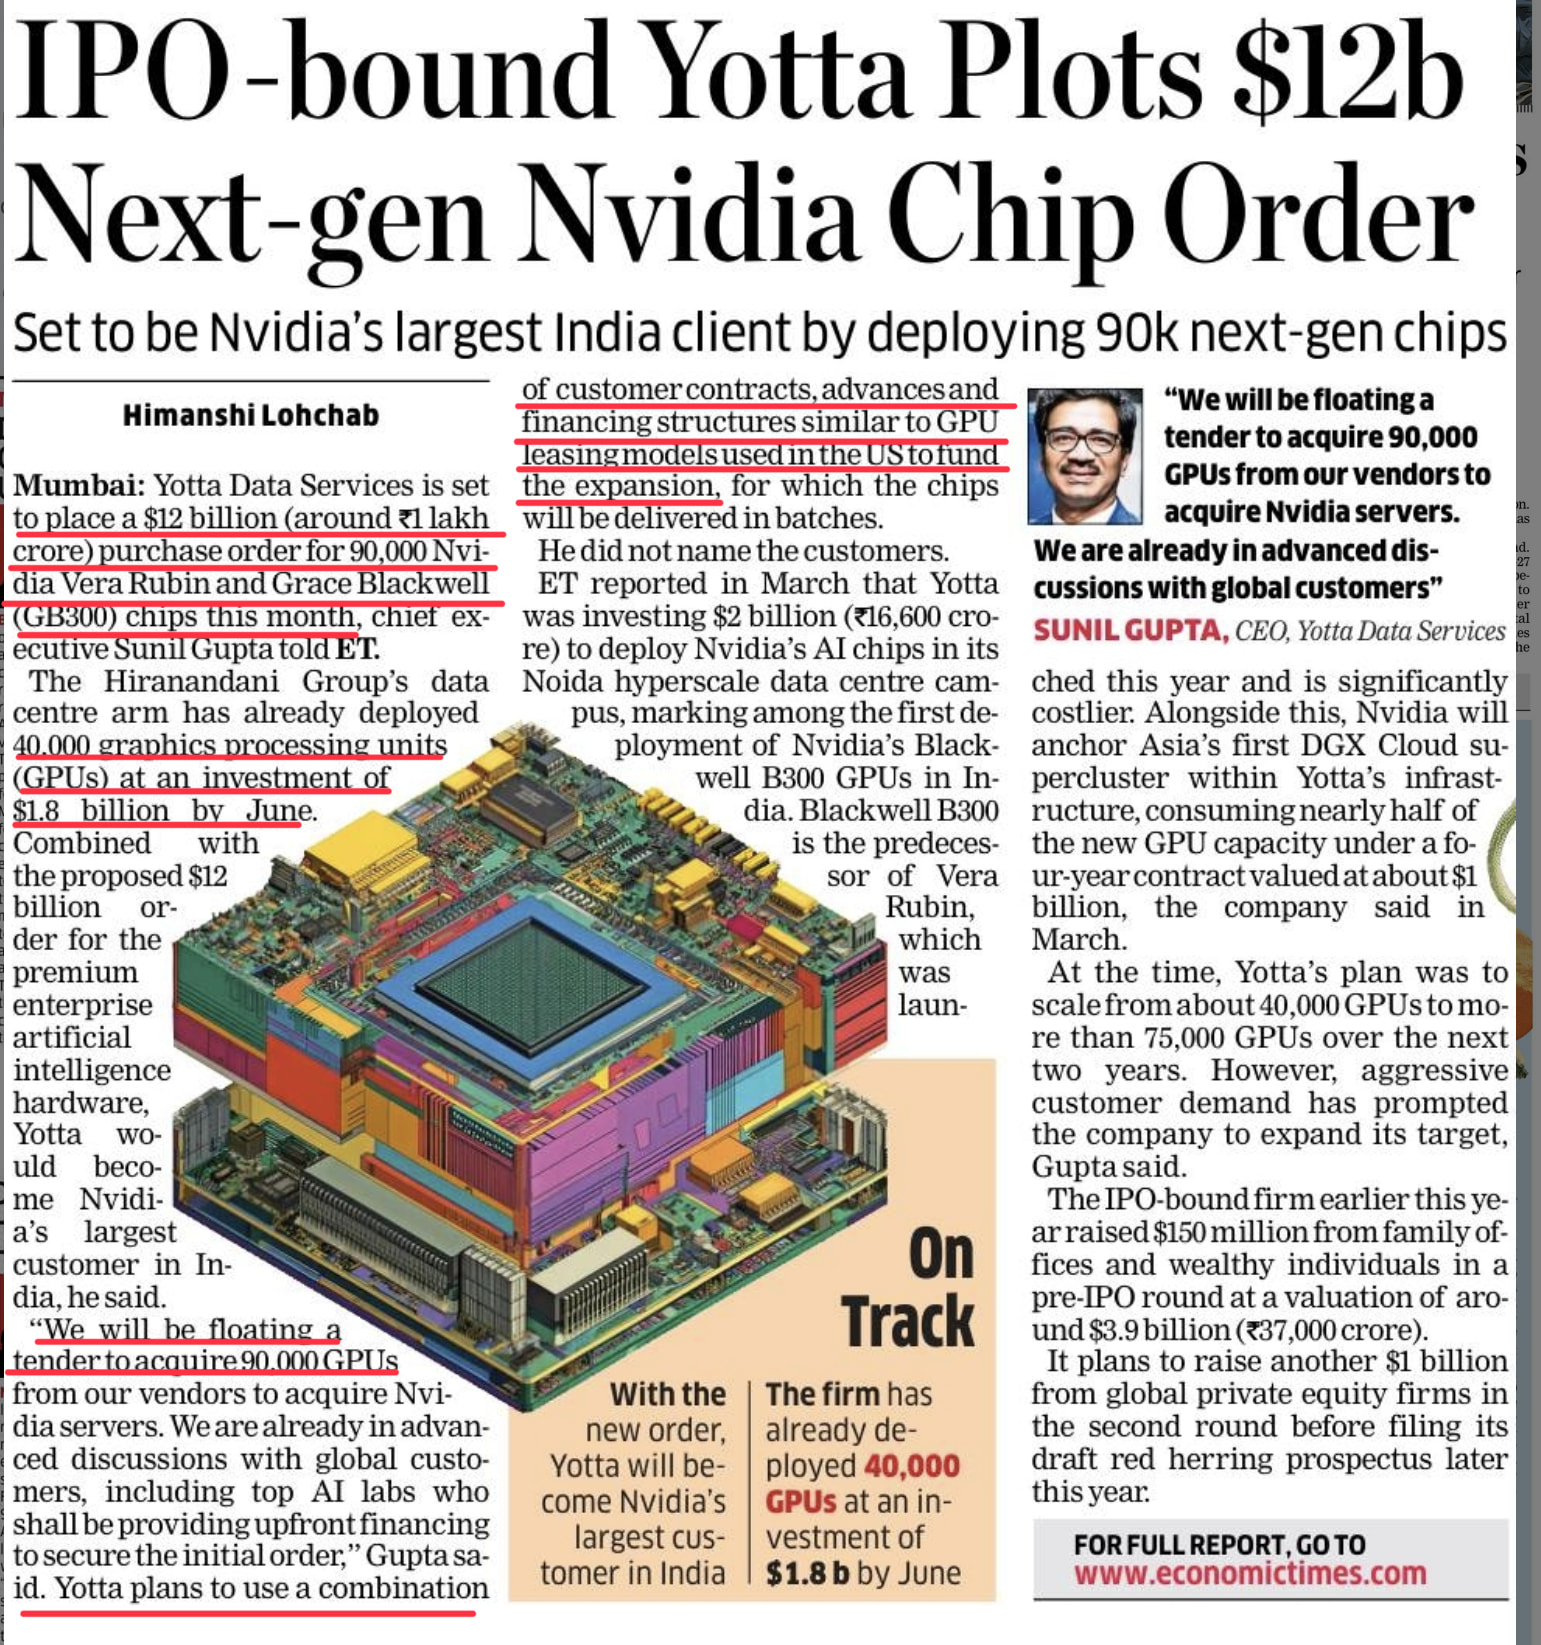
Yotta placing large orders for Vera Rubin and Grace Blackwell. Upfront financing models from customers, institutions and infra players used by global players like Coreweave and Nebius would get experimented here too. Post ESDS blockbuster listing gains Yotta IPO would be keenly watched.
opportunity for E2E. Trailing financials makes E2E look more expensive. On a forward case, things change. E2E needs to scale their software and TIR platform to have a competitive edge over others.