
Company: E to E Transport Infrastructure
Sector: Railway Safety and Intelligence
Exchange: NSE Emerge
Basic Details
• Market Cap: ₹600 crores
• Issue Price: ₹174
• Current Price: ₹354 (as of 11 Sept 2026)
• Listing Date: 2 Jan 2026
Financial Highlights
• Revenue (FY26): ₹380 crores
• Net Profit: ₹17 crores
• ROE: 10.4%
• Debt-to-Equity: 0.9
• Revenue Growth (3-year CAGR): 41%
Business Overview
• What they do:
Railway system Integrator and providing end to end rail engineering solutions. They specialize in design, implementation, and commissioning for signaling and telecommunication across mainline railways, urban transit, and industrial private sidings. Business is highly seasonal with 30% H1 and 70% in H2.
• Key Services:
Signalling and Telecommunication
Overhead Electrification
Engineering Design
Custom Railway projects
Private Sidings for Industries
• Key Customers:
Public Sector : Indian Railways , Metro corporations etc.
Private Industrial : Tata steel , Adani , Siemens, Alstom etc
Management Quality
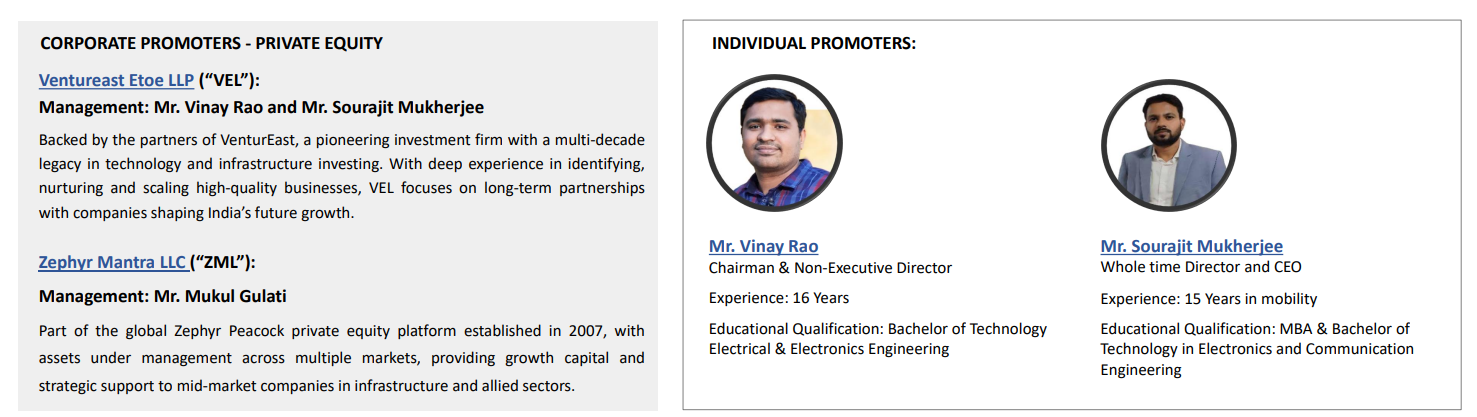
• Promoter Background:
Promoters hold a 32.54% stake in the company, having been backed from an early stage by venture capital partners like Vinay Rao (Ventureast). The stock has gained strong market backing, with veteran investor Mukul Agrawal holding a ~14% stake.
Key Management :
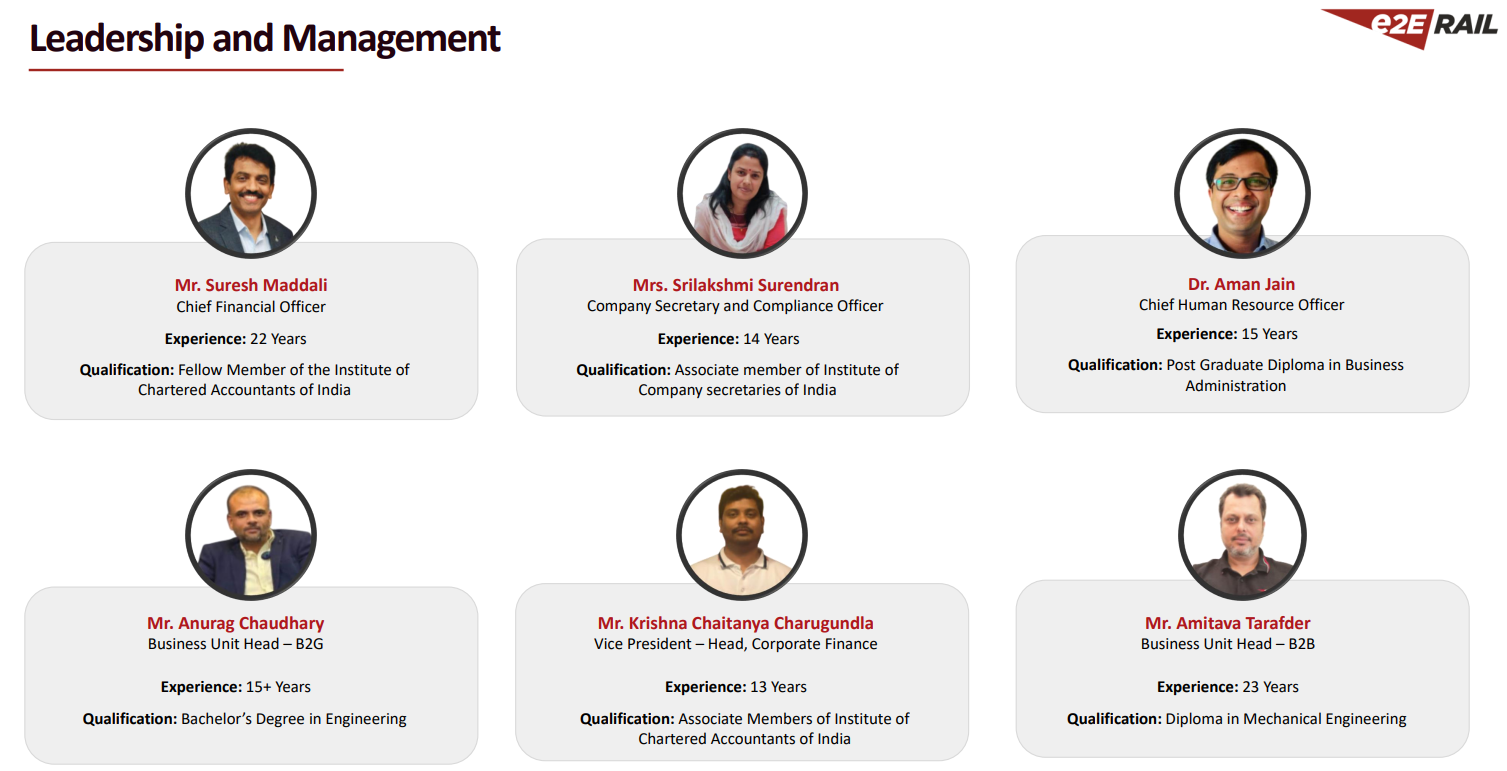
• Promoter Holding: 32%
Investment Thesis
The key thesis here is the company’s shift from a low-margin System Integrator to a high-margin, OEM led end to end solution provider. Historically, e2e operated purely as an integrator executing projects, testing, and deploying systems while relying on third-party hardware, which kept their margins capped.
Now, through its subsidiary Nova Control Technologies, the company is stepping directly into product manufacturing for Kavach and other advanced Train Protection Systems. While most competitors excel at either product development or project execution, e2e is bridging that gap by offering both under one roof giving them a unique, high-margin competitive edge.
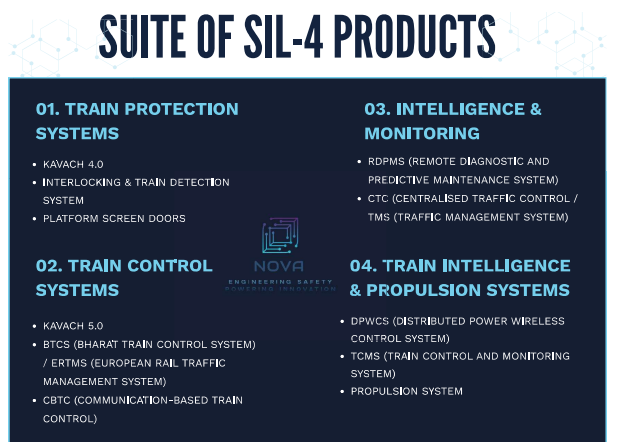
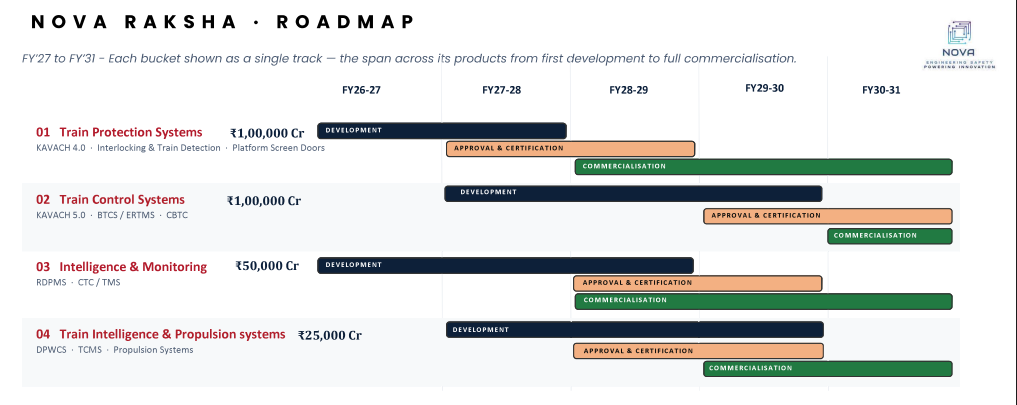
Large TAM and Timelines :
Concerns & Risks:
-
Heavy Dependence on Indian Railways & Government Capex: The company’s growth trajectory is tightly linked to the Ministry of Railways’ budget allocations and modernization mandates. Any shift in government policy, spending slowdowns, or tender delays will directly impact order inflow.
-
Stretched Working Capital & High Receivables: Receivable days remain on the higher side. While management highlights that this is largely seasonal with the bulk of billing and collections occurring in the second half of the fiscal year it still poses a working capital drag typical of government-facing contracts.
-
Execution Dependency on Kavach & Product Approvals: A significant portion of the high-margin thesis hinges on the commercial success of Nova Control Technologies. Any delays in securing certifications and approvals or slower-than-expected Kavach deployment across zonal railways could push back the projected margin expansion.
Valuation
• P/E Ratio: 36
• P/B Ratio: 3
Financials
• Revenue from Operations:
- FY24: ₹172.50 Cr
- FY25: ₹250.80 Cr (+45.4% YoY)
- FY26: ₹379.99 Cr (+51.5% YoY)
• Operating Profit (EBITDA & Margins):
- FY24: ₹19.66 Cr (11.4%)
- FY25: ₹28.82 Cr (11.5%)
- FY26: ₹38.00 Cr (10.0%)
• Net Profit (PAT):
- FY24: ₹10.30 Cr
- FY25: ₹14.00 Cr (+35.9% YoY)
- FY26: ₹16.76 Cr (+19.7% YoY)
Peers
In the train safety space, incumbents like HBL Power, Kernex Microsystems, and Medha hold an early-mover advantage as established Kavach product suppliers. However, these peers mostly focus on manufacturing and rely on third parties for ground execution. E2E Rail sets itself apart by handling both in-house product tech (via Nova Control) and hands-on site deployment, offering a complete end-to-end package.
Disclosures:
Invested and Biased.
Disclaimer
SME stocks carry higher risks due to their smaller size, limited operating history, and relaxed regulatory requirements. This analysis is for educational purposes only and should not be considered as investment advice. Always conduct your own research or consult with sebi registered financial advisors before making investment decisions.