As note of introduction recently joined the forum (Novice Investor)
I have created a Tradingview script for my valuation for individual stocks i try to invest based on the signals and the companies fundamentals strictly focusing on the numbers and the companies actual activities and history .
Based on the script (refer screen shot) :
This script for DCF
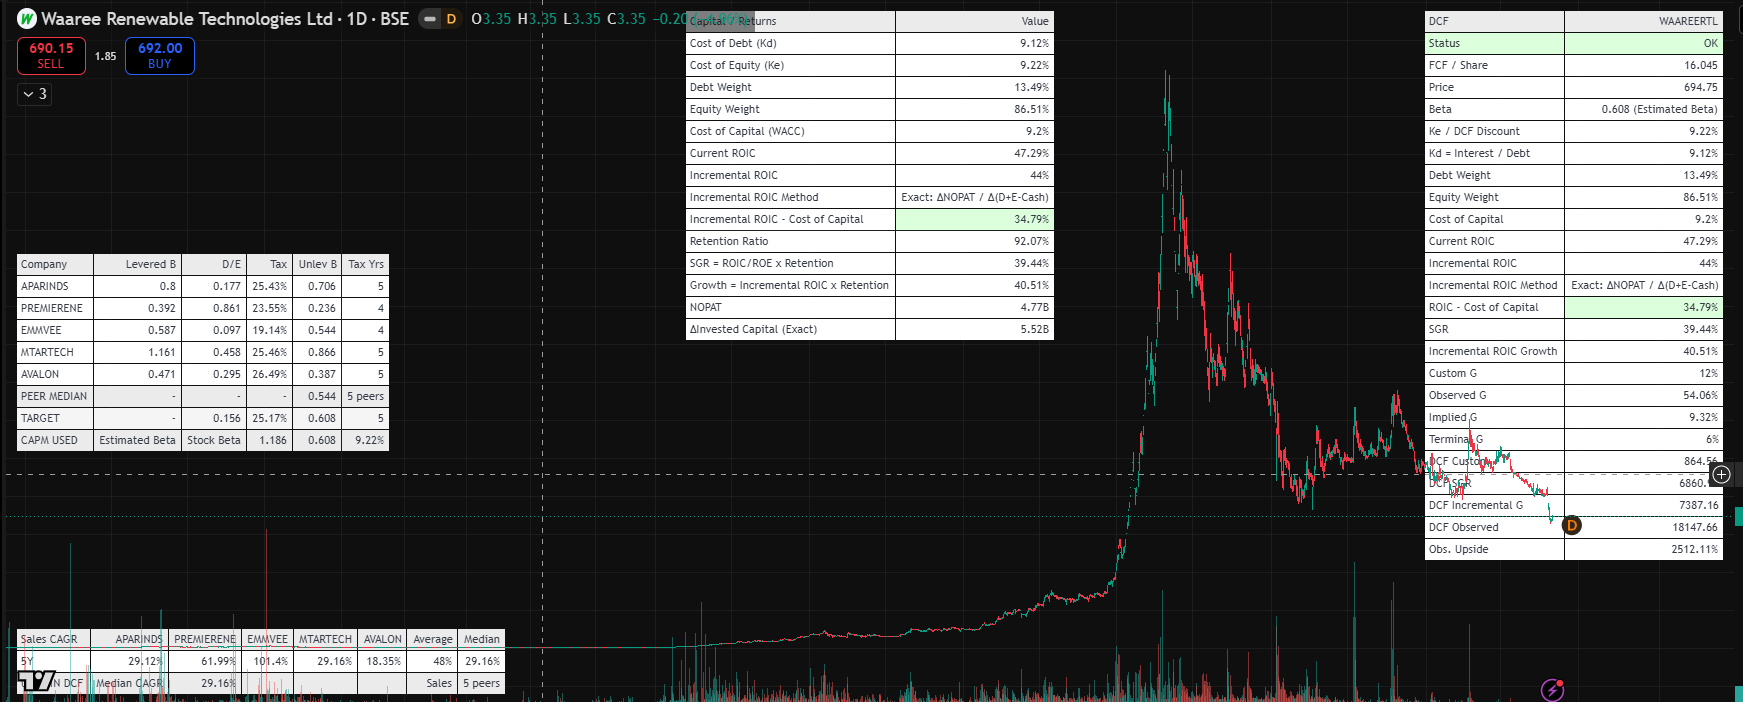
DCF Model – Inputs & Computation
1. Forecast Settings
-
Forecast Period: 10 years
-
Valuation Metric: FCF per Share
-
Custom Growth: 12%
-
Terminal Growth: 6%
-
Minimum WACC–Terminal Growth Spread: 1%
2. Cost of Capital
-
Cost of Equity (Ke): 9.22%
-
Cost of Debt (Kd): 9.12%
-
Debt Weight: 13.49%
-
Equity Weight: 86.51%
-
WACC: 9.20%
-
Beta: 0.608 (Estimated Beta)
-
Tax Rate: 25.17%
3. Growth Inputs
-
Custom Growth: 12%
-
Observed Growth: 54.06%
-
Implied Growth: 9.32%
-
Terminal Growth: 6%
-
Observed Growth Method: Maximum
4. Reinvestment Inputs
-
Reinvestment Return: Average ROIC
-
Retention Metric: Average Retention
-
Current ROIC: 47.29%
-
Incremental ROIC: 44%
-
Retention Ratio: 92.07%
5. Growth Computations
-
Sustainable Growth Rate = Average ROIC × Average Retention
-
Incremental ROIC = ΔNOPAT / Δ(Debt + Equity − Cash)
-
Incremental ROIC Growth = Incremental ROIC × Retention Ratio
-
Observed Growth = Maximum selected historical growth rate
6. DCF Computations
Four valuation scenarios:
-
Custom Growth DCF
-
Sustainable Growth Rate DCF
-
Incremental ROIC Growth DCF
-
Observed Growth DCF
For each scenario:
-
Forecast annual FCF per share.
-
Discount forecast cash flows using WACC.
-
Calculate terminal value using Gordon Growth.
-
Discount terminal value to present value.
-
Sum present values to arrive at intrinsic value per share.
7. Peer Beta Inputs
-
Peer levered betas
-
Peer debt/equity ratios
-
Peer tax rates
-
Peer unlevered beta median
-
Target debt/equity ratio
-
Target tax rate
Beta is estimated by unlevering peer betas and relevering the peer median using target capital structure.
8. Additional Financial Metrics
-
NOPAT: ₹4.77 billion
-
Change in Invested Capital: ₹5.52 billion
-
Current ROIC: 47.29%
-
Incremental ROIC: 44%
-
WACC: 9.20%
-
ROIC − WACC: 34.79%
, Though currently the capital structures have substancially changed based on the acqusition of the transmission company resulting in extreme fluctuation in current year on TTM basis so i have not modified it till i get the annual figure , please refer the TTM analysis for now ,
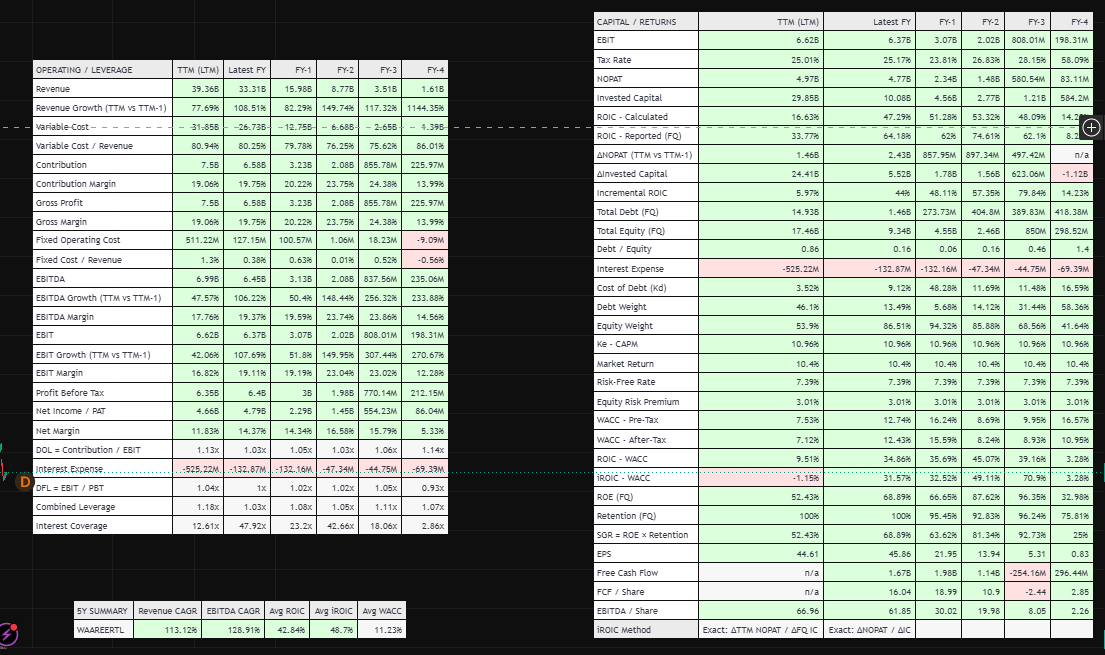
i have made a sizable portion of my small portfolio in this based on the companies performance and current pricing.
The recent concall suggest a temporary flucuation in margin , but the diversfication in adjacent and downstream value chain such as transmission , BESS and power production should have a long term improvement . (Note i had my purchase in september 2026 , my average sits at 874 currently down 20%)
would like an opinion on my view and my methology any tips for improvement is much appreciated.
(Please note I’m not a SEBI registered Research Analyst)