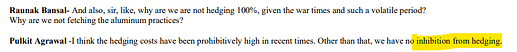Creative Graphics Solutions India Ltd

Hi Aditya,

Here is how I think about the result and here are few questions which I have open to all

Let me just put out the numbers segment wise below plz note they do lot of inter corporate stuff hence there can be few error.

  1. FLEXO

  1. Not much to comment on this segment, there is 3-5% GM compression here, on top of that we have 2.5 to 3% EBITA compression as well (employee cost being the major increase)

  2. This is a 120cr business, with banglore now operational and Oman (yet to soon, functionally ready but not operational yet for known reasons) I think 15-20cr incremental revenue form this segment, with 11-11.5% net margins (just adding EBITA level improvement, lower employee cost as a % also on dep and interest looks achievable with current GM) so 15 - 16cr PAT form here FY27 looks achievalble

  3. WAHREN

  1. Significant GM compression with following reason attributed
    a) Excess order booking to retain customers, with shorter purchasing cycle with customers and longer price commitment, increase in price effected margins
    b) Suppliers not honouring contracts, longer delivery period, repricing form past pricing commitments but not able to do the same with customers
    c) Of cource exxissive increase in RM prices in a very short time

Question to ask = Which reason attributes to what % of total reduction of GM form 28% to 14% almost 14% is anyones guess, becasue if these numbers are known then any impact for A and B looks reversable pretty fast

My take is with new capacity almost live and the learning curve of this situation (as they say in concall) these are bottome GM, any further deterioration form here looks very difficult, in fact a immediate 2-3% improvement looks possible.

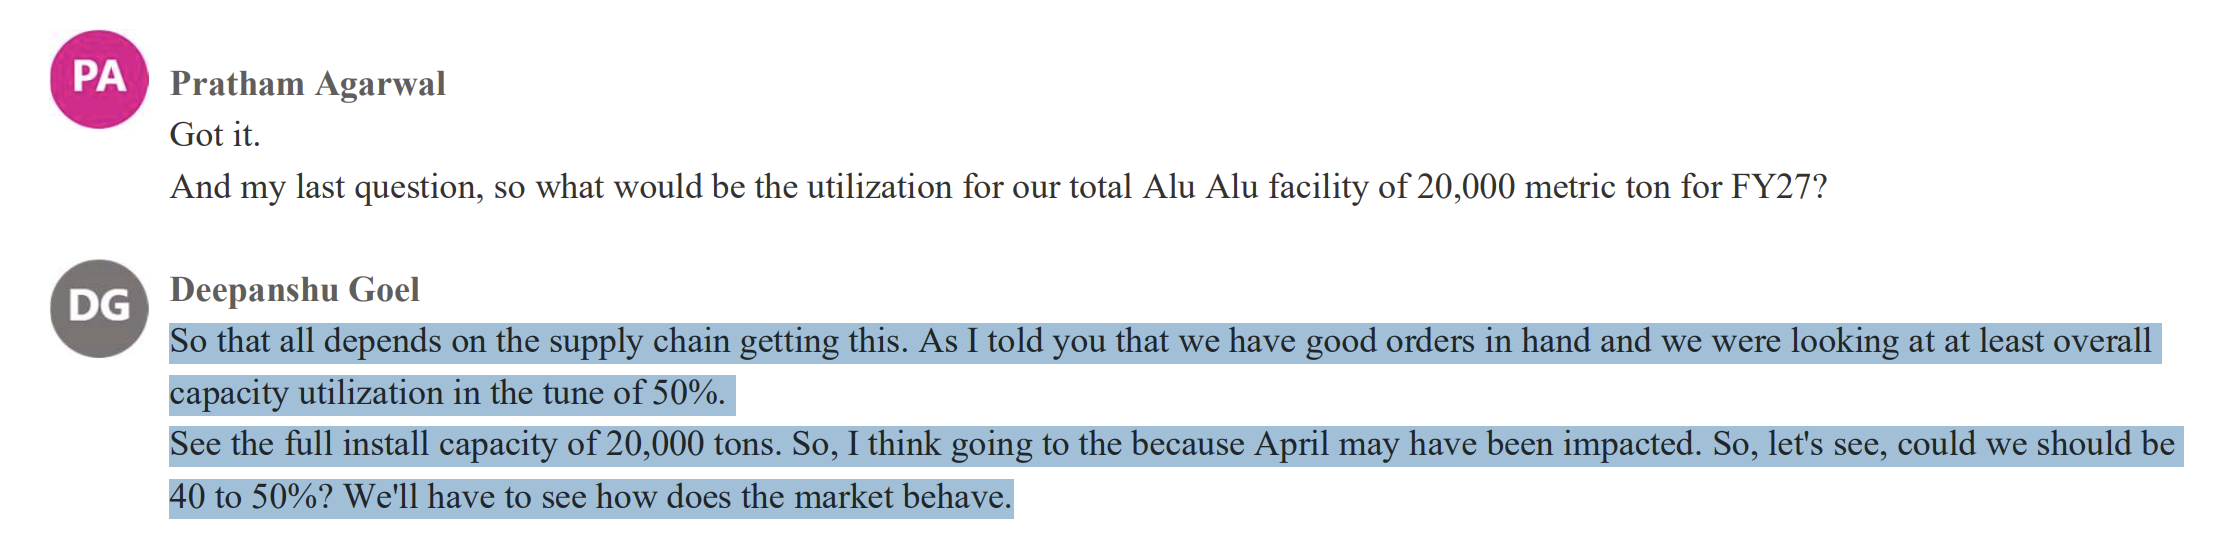
Other triggers form margin improvement are PVDC (Higher GM than alu alu, lesser supply chain disruption than alu alu). Exports of Alu Alu, also look 2-5% GM accretive (Management in the call has said 20-25% export target on incremental capacity of 12000 Mt)

At a post GM level no major impact, slight employee cost increase, but over all economis of scale is visible with 50bps to 1% improvement possible with further scale.

Questions to ask = 1. No Major impact on top line on a HOH basis despite stating supplychain issue and Management stating 80% utilization in H2 for Alu Alu. Also last concall and this concall price hike was taken was stated with 350-360 to 500-550 of price moment in alu alu. So given that we has similar utilization, sales numbers look pretty low

Either volumes are impacted or price pass on effect has not yet reflected

Management has also constantly been stating on no demand side disruption and supply side is what has been impacted.

Over all my take is any further net margin deterioration form these levels look very difficult, infact consedering all the above discussion consedering current environment persist (relif form point A & B and other triggers should lead to 2-3% immediate improvement)

So for the current FY a current environment PAT margin of 3% and a business potential PAT margin of 10% (stedy state) is what the key take aways is

Given that no deamnd side problem a 30% utilization in both PVDC and incremental alu alu should add incremental (160+90 = 250)cr of pharma revenue (450,250) as the respective price assumption.

So 135 flexo 250 incremental pharma 225 current Pharma (this can also increse by 15% if we are assuming 450 as the new price) so 610cr of Revenue consedering current state presist is what they should achieve (this does not include Tandem).

Overall all at the current state the numbers which I am getting is 600-650cr top line and 30-35cr bottome line. Though my personal expectation is slightly higher

Overall as said earlier I would value this company at sales, 700cr looks very much achivalbe this FY so at less than 0.5 PS, in good time I would give them 1.5 to 2 times sales

Disc - Invested, added in last 30days
Below are console numbers incase anybody wants them

4 Likes

Many managements won’t show this honesty till Q1 results. Q4 results have been good for many companies but Q1 would be different with almost 2 war affected months. A small company openly acknowledging issues (most of which are beyond their control) is a breath of fresh air. Kudos to them. I remember export oriented companies like Garware faced a similar situation last year due to US tariffs but came out flying once the clouds dispersed. Once the war is over, CGraphics will do really well. Especially with capacity coming online imminently.

1 Like

my personal reading is and again I can be wrong here. they might have suffered the oversupply of order for 1-2 month max. their topline should have improvement considering the price hike for alu alu.
now there are 2 optionalities both of them are guesses a) they have not been able to pass through price hike b) there is a hit on volume realization

personally I think volume realization is not hit because there needs to be someone who can absorb the supply of cg at same time, it’s more on lack of pricing power from CG which has affected it

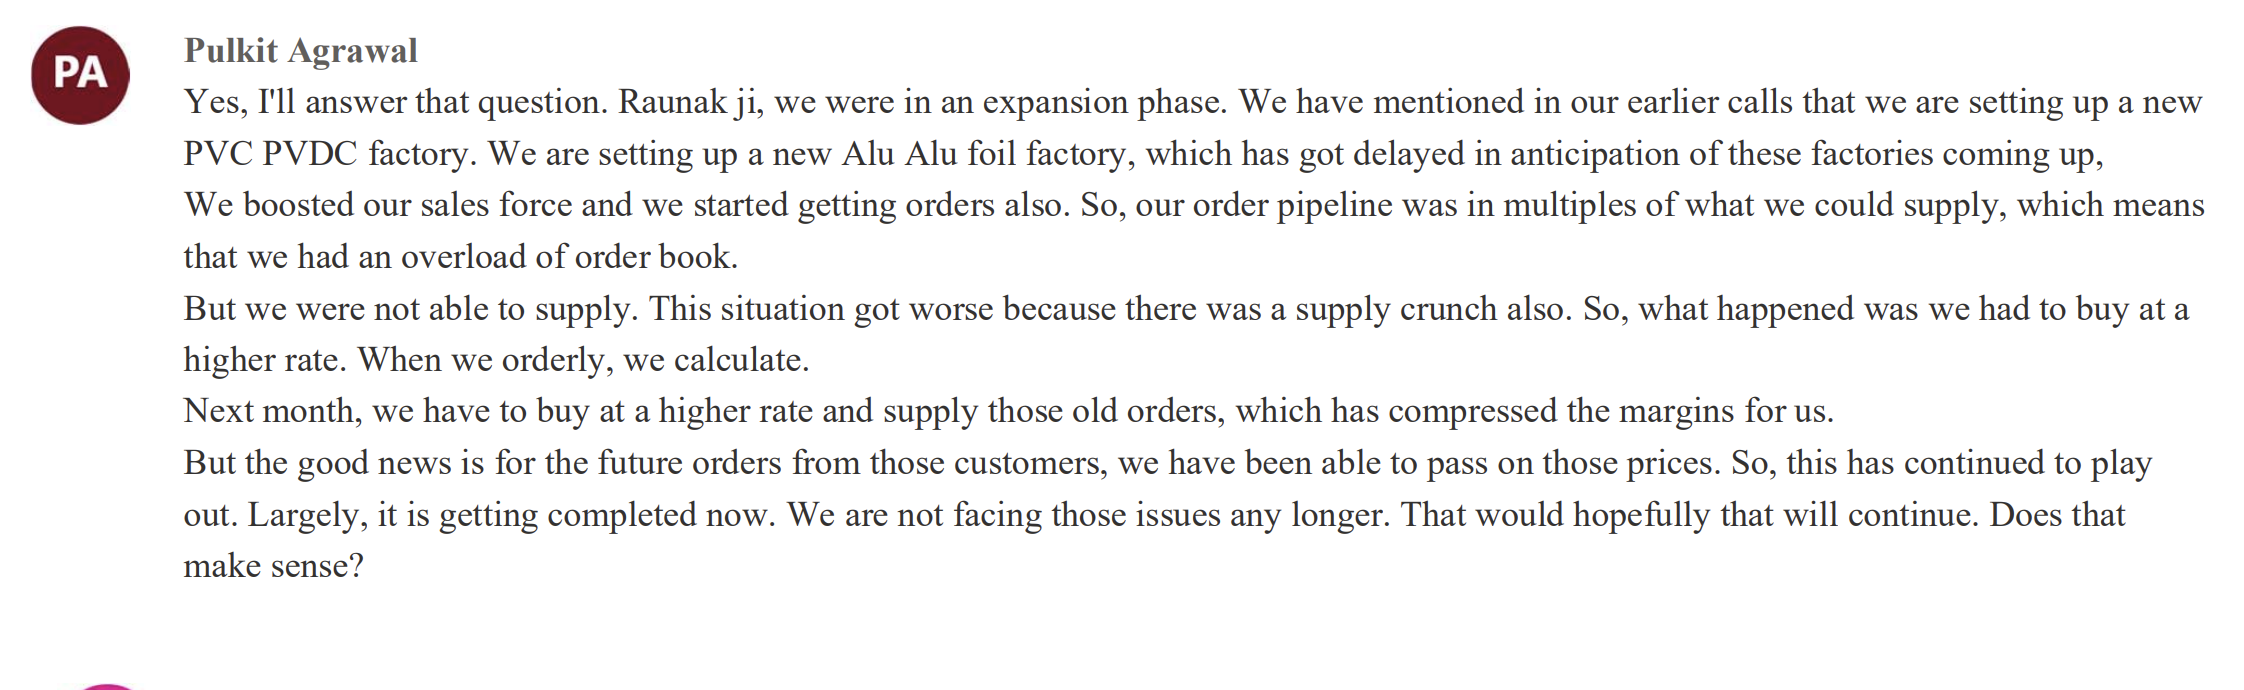
They have said in the concall that they were overflowing with orders which couldn’t be supplied because of raw material shortage. Now, the availability has improved and price hikes have been affected.

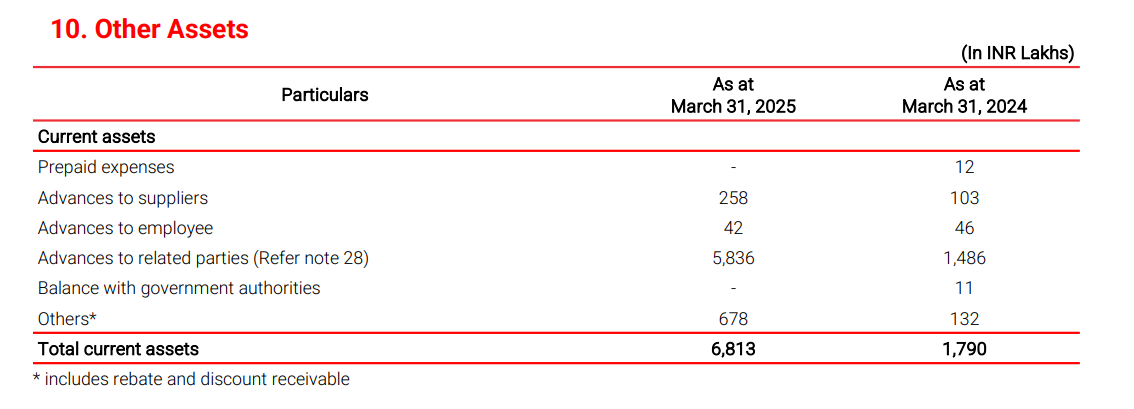
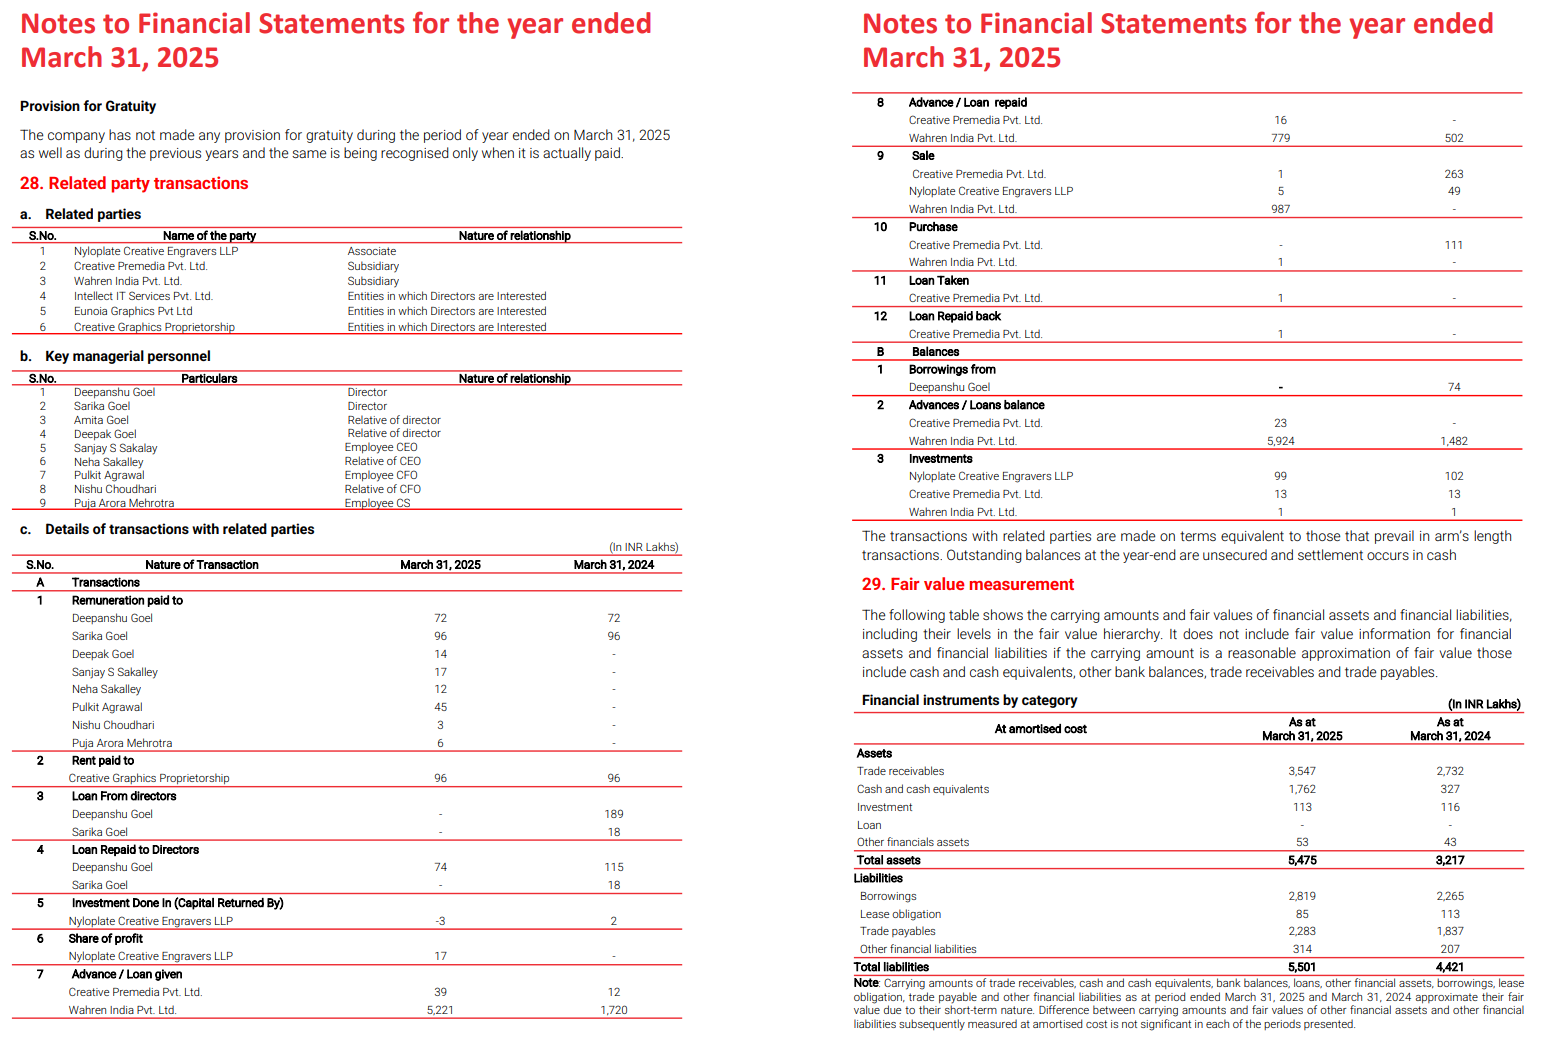
Anyone know what could be these other assets worth 88 cr?

Edit: I checked fy25 annual report and its explained there for previous year 68 cr. Will need fy26 report to get full breakdown because that number looked significant

Yes the overflowing of order occurred because their new capacity couldn’t kick in time and tbey had to adhere to order pricing. But my point was this oversupply shouldn’t have been for more then 1-2 months. Cause within that 1-2 month they would have known that machine is stuck with port and they can’t take more orders.

Also my larger point is with alu alu price increasd the top line should have improved but ch has taken hit to maintain customer relation

Again we don’t know what lead to no topline increase given the increase of alu alu. These are guesses at max

1 Like

Aluminium price rise will impact Creative Graphic margins and demand

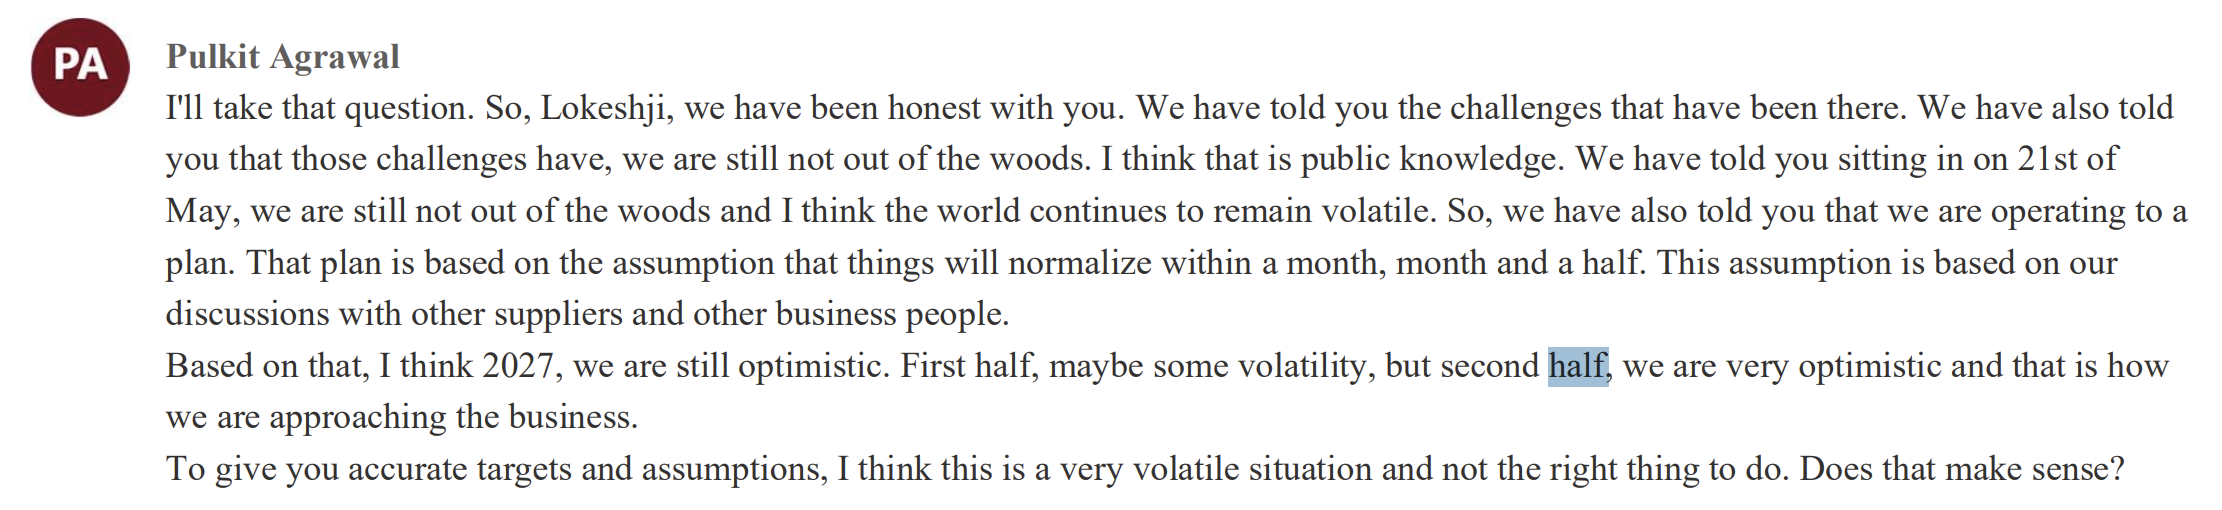
went back to concall again
there are some moving parts but hard to attribute what caused the damage
they also had supply issues of RM which made their util hit, and they clearly mentioned it’s not resolved fully and they have been hit in april and may as well.

so it can be a mix of volume hit because of suppliers defaulting combining with their oversupply of orders with old prices.

thesis is intact for me, but delayed. they have been crused by issues beyond their control and they also came very transparent with it.

disc: invested and added in last 30 days

1 Like

@manhar I went back to your orignal initiation and research, that the industry is net 20% GM in end so the 28% reported is something to be questioned on so from 14% to 20% recovery seems to be in place with their issues of supplies and RM costs

This industry is a 20% GM business but I think wahren books some expense in creative which pumps this GM or there is some misclassification and reclassification possibility this half (though management denied in concall) but with what ever facts we have there is a 10% GM compression.

1 Like

Hi guys long time

Recentrly I got the opportunity to attend InnoPack Pharma Confex which brings together those who matter in pharma packaging under one roo

I did try last year as well but only pharma comanies get to attend this,but somehow made it this time

Before starting a Disclaimer = No exchange sensitive information was discussed, all my learning which I am going to present is around the business and industary structure and these are also form the exp of individuals hence we need to take it with a pinch of salt

Firstly lets see what team Creative Graphics has built

  1. Deepanshu Goel (Founder and MD) Deepanshu Goel - Wahren | LinkedIn
  2. Pulkit Agarwal (CFO) https://www.linkedin.com/in/pulkitagrawal/
  3. Sanjay Sakale (CEO CG PREMIDIA) Sanjay S Sakalley - Creative Graphics Solutions India Limited | LinkedIn
  4. Muhammad Rafeeq M (CEO CGRPAHIC) https://www.linkedin.com/in/grapheeq/
  5. Dhan singh (AVP Wahren) https://www.linkedin.com/in/dhan-singh-0b094735b/
  6. Abhay Raikar (President international BD) https://www.linkedin.com/in/abhay-raikar/
  7. Sanjay Ahuja (BD Manager) https://www.linkedin.com/in/sanjay-ahuja70/
  8. Girish Misal (Head of QA) https://www.linkedin.com/in/girish-misal-916ab827b/
  9. PVDC is being headed by a gentelmen with 20yrs + exp in bilcare

(Bilcare, Amartara and ACG are key PVDC players)

I would request every one to take a moment and have a look at all the profiles above, it is mostly may be - 1 team and there are many more like the gentelment to the right in my photo above has 25+ yrs of exp in SGV foils

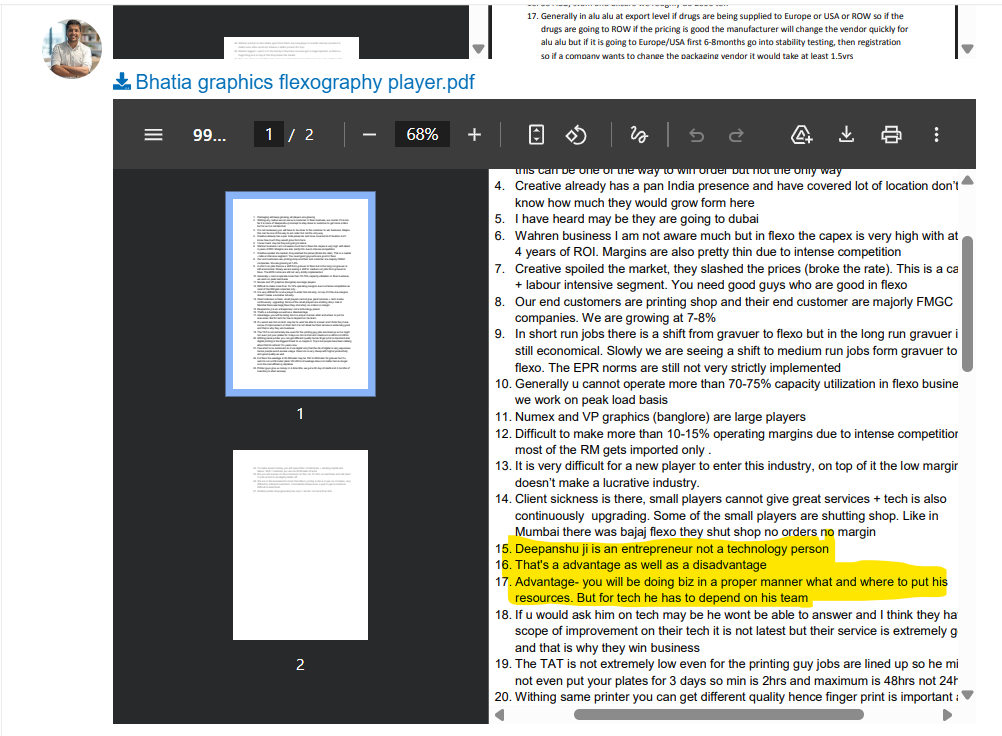
This makes me remember the feedback from a flexo competitor which I have put up in the thread. His characteristic of attaining market leadership in flexo is being reflected in wahren by the kind of team he has built

Also flexo being a 5-10% growth business and a CEO being in place only singnals that wahren would get all the time of the MD

What new Insights I have learn about the industary structure

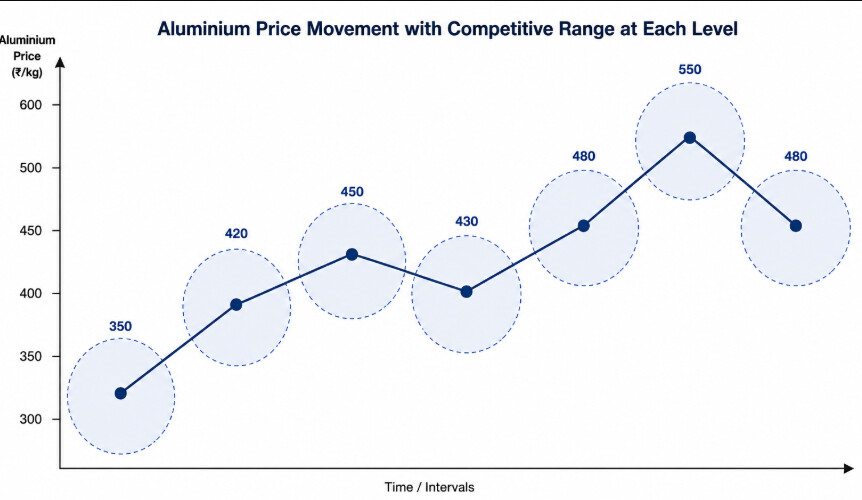
  1. Prices are easily passed on but are competitive at the same time so u can think of it this way that prices are anchored to aluminum prices and any large movement on either side is easily passed on as alu alu as a % of total packging procuriment in paharma companies is very small but around the aluminum linked price there is a large range of price around whcih there is extreme competiion
  2. This competition exist for the following reason
    a) Every Procuriment head increment each year is linked to the savings they do hence they try to squeeze everyting
    b) Every Procuriment guys has vendors who are classified as A B or C (this is generally classified info with only the procuring head of pharma companies) they tend to take maximum material for A more than 60-70% then 10-20% from B and balance form C. This is done cuz non urgent procuriment is routed via C which is checked multiple times when they receive the matererial and urgent, time pressure procuriment done via A & B. Now every time when u go to the negotiating table for selling the procuriment guy has quote form A, B & C with C being the lowest and A & B being pressurised to come down. So this is general industary practice ur quality as a supplier is know to the vendor but on the negiotating table u are squeesed as multiple quotations going around and how u as a manufacturer are classified A B or C is only know to the procuriment pharma team so u are under constant pressure as a manufacturer to sell

So at any point in time there are sellers at 550 and 480 at the same time. You ability to sell at a higher rate is only dependent as to how strong a brand u have in the industary hence ACG, Bilcare and Svam tend to sell at 20-40rs higher than prevaling market rates

And this is one of the reason u would see wahren sponsering majortity of india pharma packging conclaves to create a strong brand in the market

  1. To be price competitve while maintaitnig ur margins in this industary u have to export (must) there are multiple advantage
    a) Your GM are 5 - 10% higher
    b) Your Receivalbe are much shorter due to LC unlike 90-120 days in domestic
    c) U get to have a larger TAM and more diversified clientel
    d) U get duty credit on import duty against the quantum u export. Kindly note chinese pharma grade aluminum prices are 3 -7% cheaper and currently we have a import duty on it (this is one of the biggest advantage) hecne with export u get to import RM at 3-7% cheaper

If u would have seen wahren linkden over the last 12-15 months wahren might have attended over 10-15 international expos and that is what give management the confidence to have 20% export share in thier alu alu capacity as stated in the conference

  1. Majority of south east asian countries, west asia, arab countries, africa and south american countries dont have manufacturing of alu alu packging as it dosent make economic sense and the biggest competitor is china with a better pricing but unreliable supply, supplier being dominant in the relationship and companies wanting to diversify out makes indian supplier the second preffered choice.

Just to give a rough estimate I can be totally off baglades itsel is a 1500-2000 ton market a month so a 10% share there is 150-200 ton a month against 1650 ton per month wahre alu alu capacity that is almost 9-12% so getting to 20-25% export on entire capacity with all the other countries seems quite possible

  1. If u would see another listed competitor called GSM foils (though totally different prodcut but same RM) did not have any GM compression why?

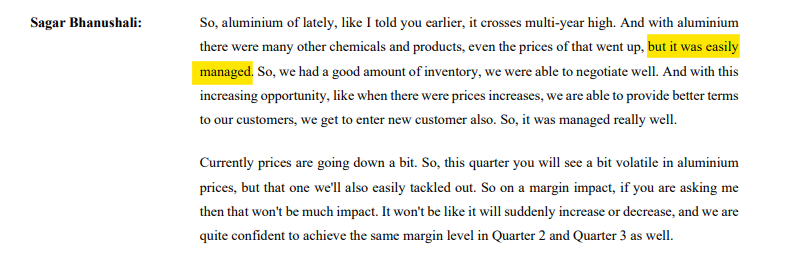
Once management saying easily managed while other one finding a hard time? Is it that Wahren is totally new hence they are laerning?

What I have been able to understand if u see thier team majority are 25+ yrs of exp in this feild so I am sure more of them understand these cycle and how to manage inventory but since taking inventory calls is new for MD and CFO until and unless they experience it, they can be very apprehensive of taking such calls
image
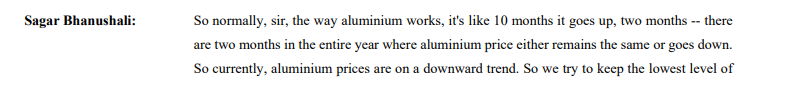
No inension for hedging (synonymously used for inventory management)

As an entrapruner in manufacturing u dont want to trade in ur underlying instead focus on making a sustainable and straighforward business but sometimes u goota understand the pulse of the industary and be at the right time and place (such calls can only be taken when top leadership has experienced it and has comfort) As seen in GSM

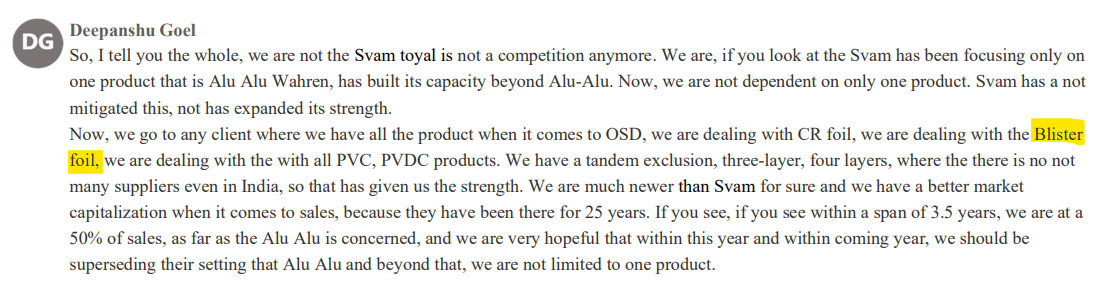
  1. On thier stall I could see they have added 2 other machines as well one is for Blister foils and one I forgot. Also if u would see the latest concall the managment stated dealing in blister, which I think has just happned recently (looks like 2 new product added)

Blister foil is the same prodcut GSM foils is dealing in and with the current problems they are facing (which is very unfortunate) maybe this also helps wahren penetrate this prodcut

All this is qualatative stuff I dont know if it adds any value to fellow memeber but what I conclude the way this business is being built and in an industary where people are starving for sales we have these guys not facing any deamnd issue, looks like something they have cracked.

With they way they are executing and problems which are temporary and beyond management control I see this as an opportunity.

I expect H1 to be weak but that dosent imapact my thesis, with sales capibility being built, I believe once the margins return we would have exponential PAT growth

Disc = I hold a very large stake in this company, I have been continously adding and I have transaction in the last 30days. All my views are extremely biased and I can go horrible wrong

13 Likes

@manhar as you mentioned ACG, Bilcare and Svam tend to sell at 20-40rs higher than prevaling market rates, with wahren at it’s growth and market capturing phase taking hit on margins with lower rates. if new capacity kicks in and they are able to take more market share from svam and are able to get better pricing + plus export mix. the scope of margin expansion increase? also curious to know what were your obersvation for starvation of sales for other people